

The expected move formula
Implied volatility is quoted as an annualized standard deviation of returns. To turn it into a move over a shorter period, scale it by the square root of time:
Expected move = stock price × implied volatility × √(days to expiry / 365)
The square root matters. Volatility does not grow in a straight line with time; variance does. Four times as many days means twice the move, not four times.
The result is one standard deviation. Under the normal distribution that standard option models assume, the stock finishes within that range about 68% of the time, and within two standard deviations about 95% of the time. If you need a refresher on where the volatility input comes from, see what implied volatility is.
Calendar days or trading days
Some traders use trading days over 252 instead of calendar days over 365. Neither is wrong, but the volatility figure and the day count must use the same convention. Calendar days suit a quick check. Trading days suit event work, because weekends carry little information and an earnings report lands on one specific session.
Three numbers people call the expected move
The term is used loosely, and that causes confusion. For the same Company A chain, you may see three different figures:
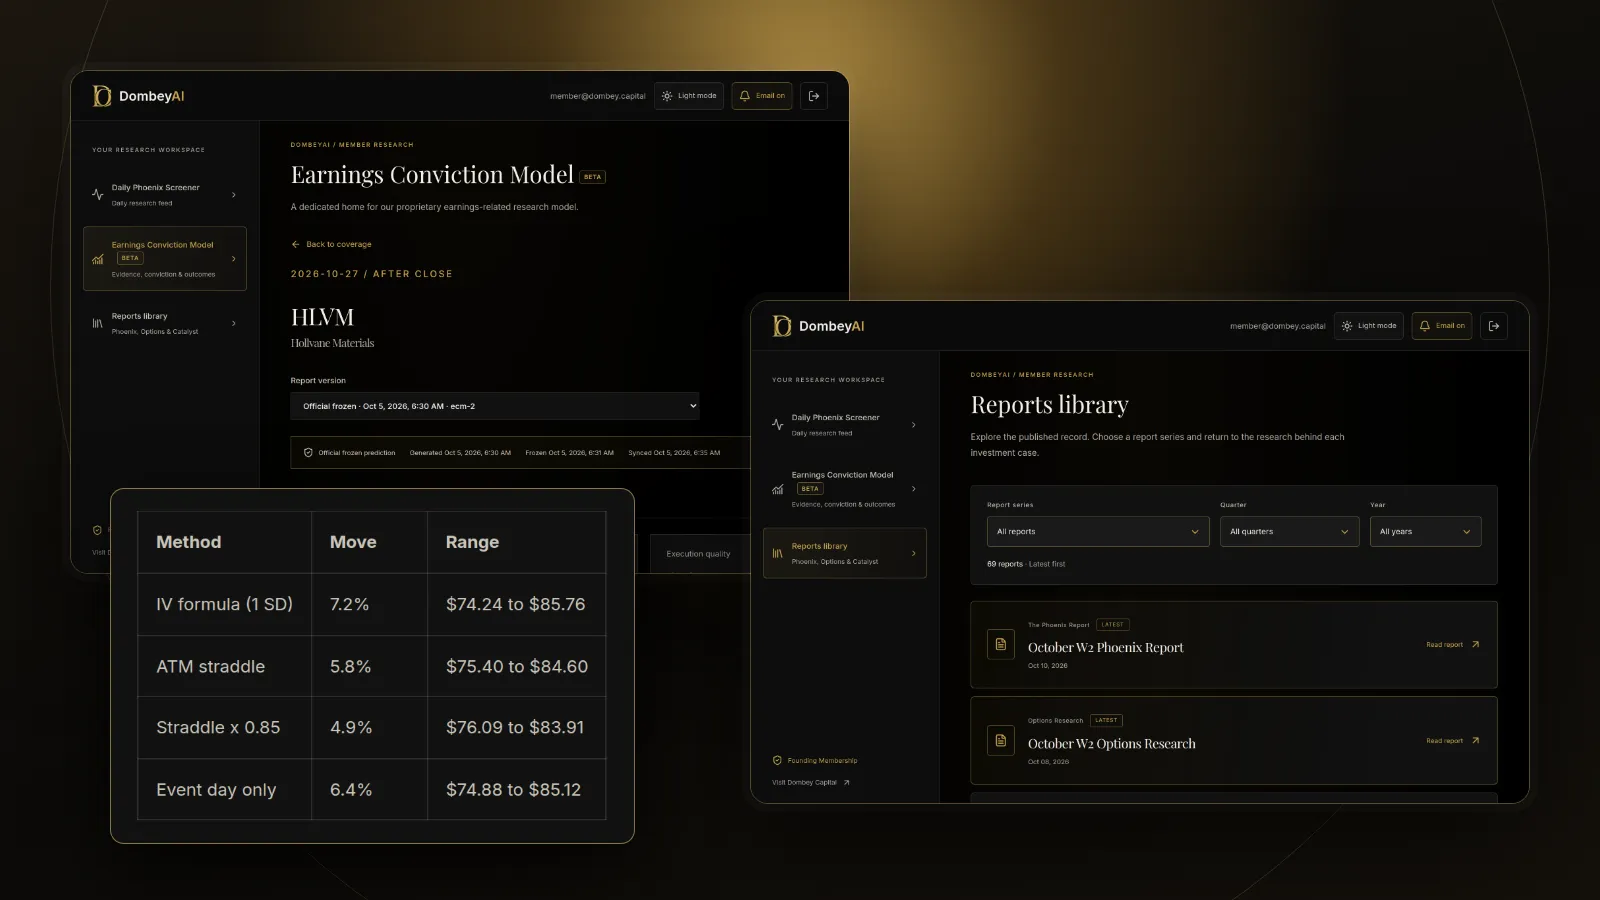
| Method | Calculation | Company A result | What it represents |
|---|---|---|---|
| Volatility formula | Price × IV × √(days/365) | $5.76 (7.2%) | One standard deviation move |
| At-the-money straddle | Call mid + put mid | about $4.60 (5.8%) | Market price of the average absolute move |
| Straddle × 0.85 | Straddle × 0.85 | about $3.91 (4.9%) | Rule-of-thumb estimate used by many traders |
All three come from the same implied volatility. They differ because they answer different questions.
Why the straddle is about 0.8 of one standard deviation
An at-the-money straddle pays the absolute distance between the stock and the strike at expiry, whichever way the stock goes. Its fair value is therefore the average size of the move, ignoring direction.
For a normal distribution, the average absolute value is the standard deviation times the square root of 2 divided by pi, which is about 0.798. So a fairly priced at-the-money straddle is close to 0.8 times the one standard deviation move. For Company A, 0.8 × $5.76 gives about $4.60.
This relationship runs both ways. If you only have the straddle, dividing it by 0.8 (or multiplying by about 1.25) gives an approximate one standard deviation move. A $4.60 straddle points to a one standard deviation move of about $5.75.
Where the 0.85 rule fits
The 0.85 factor is a trading convention, not a result from a pricing model. Traders who apply it to the straddle argue that it strips out some of the premium option sellers charge for event risk. Treat it as one view among several. If a data service shows an "expected move", check whether it is the formula result, the raw straddle or a scaled straddle before comparing it with anything else. The straddle explainer covers the position itself, including breakevens.
Isolating the move priced for one event
Before a scheduled event, the front expiry contains two kinds of days: ordinary trading days and the event day. The straddle and the formula blend them. To estimate the move priced for the event alone, work in variance, which adds across days.
The method:
- Take the front expiry implied volatility and the number of trading days it covers, including the event day.
- Estimate a normal daily volatility for the stock, often from a later expiry that sits further from the event, or from the stock's recent realized volatility.
- Compute total variance: IV squared × days / 252.
- Subtract the variance of the ordinary days: normal volatility squared × ordinary days / 252.
- Take the square root of what is left. That is the one standard deviation move priced for the event day.
The gap looks small here, but it widens as the expiry moves further from the event. With a monthly expiry three weeks out, the ordinary days can make up a large share of the total, and the unadjusted figure overstates the event.
Reading the expected move against history
The math tells you what the options are charging. It does not tell you whether that charge is high or low. For that, compare the event move with the stock's own past reactions to the same kind of event, measured as absolute percentage changes from the close before to the close after.
- If the priced move sits above most past reactions, the options are charging for more uncertainty than usual. Look for a reason: new guidance, a pending deal, a changed business.
- If the priced move sits below most past reactions, the market expects a quieter report than history suggests, or history includes one-off events that no longer apply.
- If the stock has fewer than six or eight comparable reports, the history is too short to say much either way.
The earnings catalyst explainer covers the rest of the preparation around a report, and IV crush explains why implied volatility usually falls once the result is out.
Skew and the shape of the range
The formula produces a symmetrical range. Real option prices often do not. When options skew is steep, out-of-the-money puts trade at higher implied volatility than calls, which means the market is paying more for protection against a fall than for exposure to a rise.
A single at-the-money volatility hides that. If you want a sense of the downside and upside separately, look at the implied volatility of strikes one expected move below and above the stock. A large gap between them tells you the market sees more risk on one side, even though the headline expected move is a single number.
Where this goes wrong
The model assumes returns follow a bell curve. Earnings and other dated events produce fat tails: large moves happen more often than a normal distribution predicts. A stock can finish outside its one standard deviation range far more than 32% of the time around a binary event, and a two standard deviation move is not the rare event the textbook odds suggest.
Option prices include a risk premium. Sellers of event risk usually demand more than the expected size of the move, so implied moves tend to overstate the move a neutral observer would expect. That is one reason traders use the 0.85 rule, though no single factor fits every stock.
Liquidity distorts the inputs. In a thin chain with wide bid-ask spreads, the mid price and the implied volatility derived from it can be off by several points. Many small caps and special situations have few or no listed options, so the method may not apply at all.
Other events can share the expiry. A court ruling, a shareholder vote or an investor day inside the same window adds to the price and inflates the figure you attribute to earnings.
The expected move has no direction. It says how far, not which way. Dombey's published research notes the implied move beside each earnings catalyst where liquid options exist; see the research archive.
The bottom line
The expected move turns implied volatility into a dollar range: stock price times implied volatility times the square root of time gives one standard deviation. The at-the-money straddle is about 0.8 of that figure, and the 0.85 rule scales the straddle down further, so always check which version you are looking at. Before an event, working in variance lets you separate the move priced for the event day from the ordinary days around it. Read the result as the market's price for uncertainty, compare it with the stock's own history, and allow for fat tails that the formula ignores.