

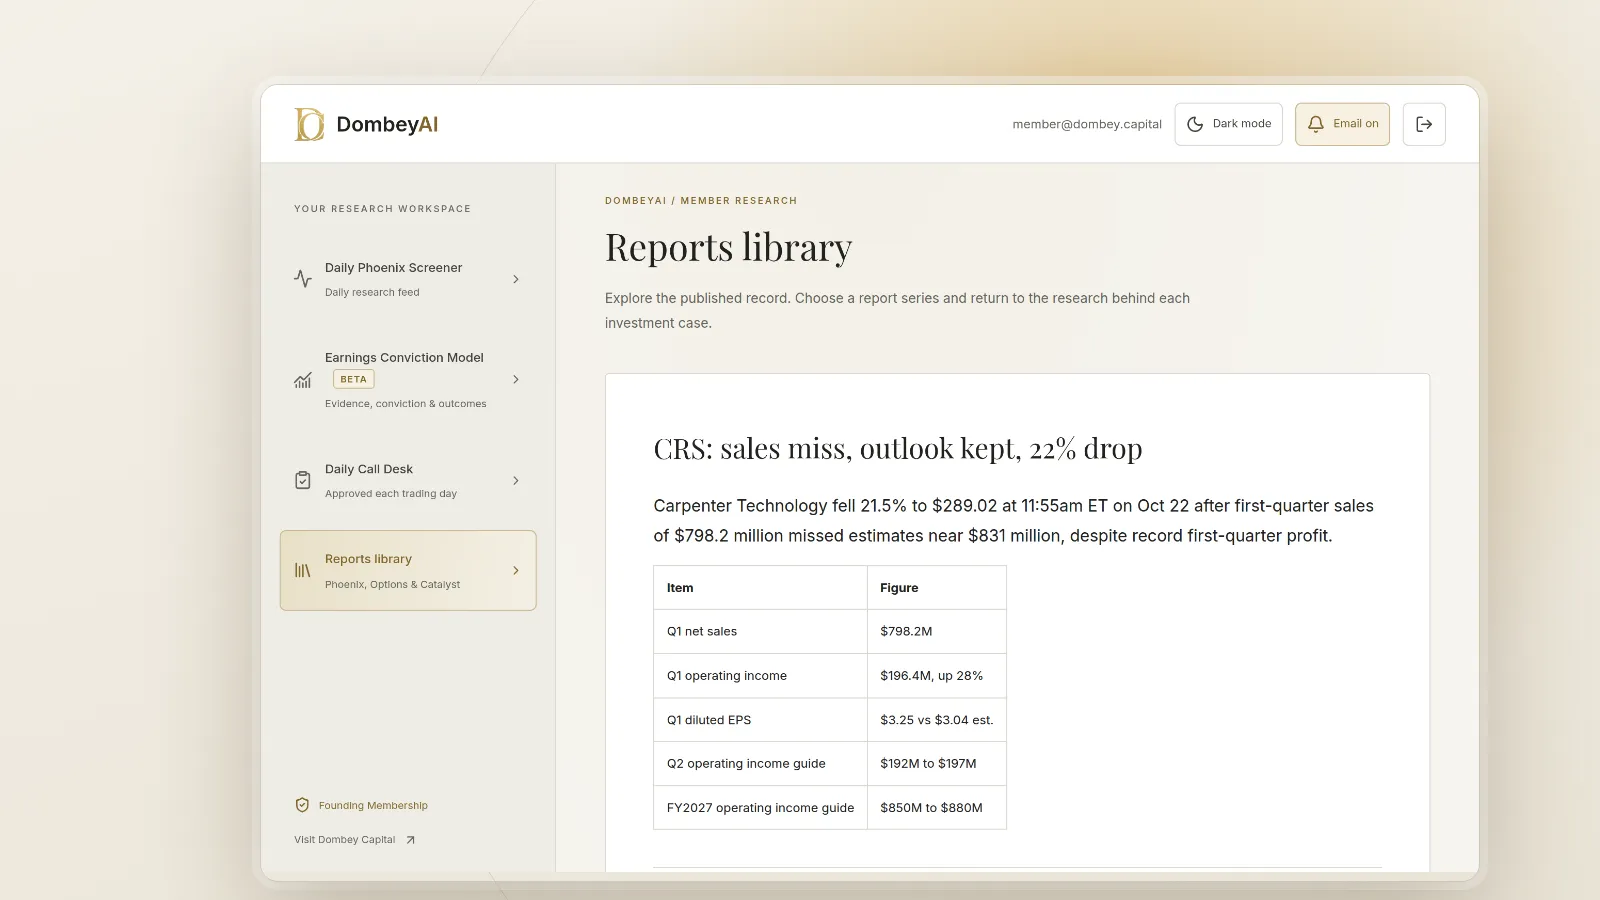
Oct 22, 2026: record profit, a sales miss and a flat quarter ahead
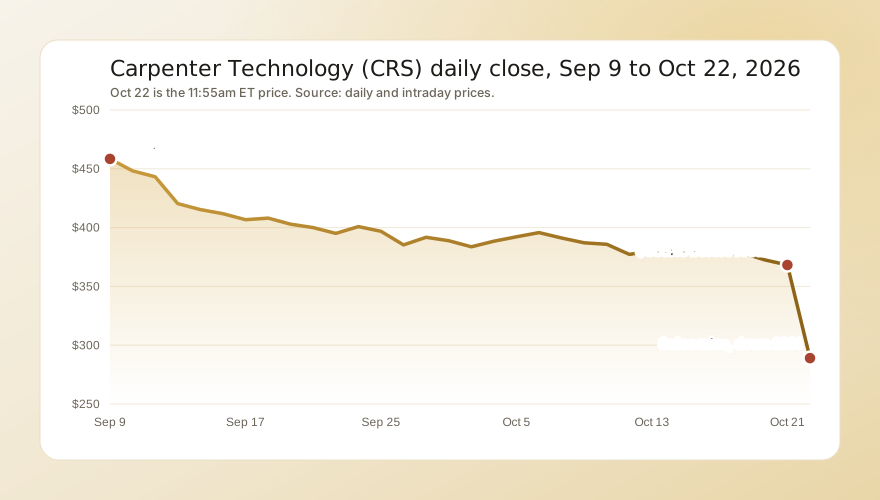
Carpenter released results at 8:00am ET. The shares had barely traded before the release; by 9:00am they had fallen to $313.00, down 15.0%. The stock opened at $330.00, down 10.4%, and that was the high of the session. It slid steadily through the morning to $284.27 at about 11:45am, down 22.8%, and was $289.02 at 11:55am on about 1.3 million shares, 1.9 times its 20-day average volume.
What pushed it down:
- Sales missed. Sales of $798.2 million fell short of a consensus near $831 million. Sales excluding surcharge rose 5% from a year earlier to $634.8 million. Management called the first quarter "nothing special" for maintenance and said it expects future outages to be smaller.
- No growth into the second quarter. Second-quarter operating income guidance of $192 million to $197 million brackets the first quarter's $196.4 million. The full-year range now depends on a stronger second half.
- Cash went out. Operating cash flow was $52.8 million and capital spending $77.7 million, for free cash flow of negative $24.8 million. The company kept its fiscal 2027 free cash flow target of $400 million to $430 million.
- Sentiment. TD Cowen's Gautam Khanna told management "the stock is acting kind of odd." Management acknowledged "a major negative sentiment that has emerged over the last couple of months" and said it could not identify the cause.
From the Oct 21 close, at 11:55am:
| Stock or fund | Oct 21 close | Oct 22, 11:55am | Change |
|---|---|---|---|
| Kaiser Aluminum (KALU) | $153.95 | $120.28 | -21.9% |
| Carpenter Technology (CRS) | $368.16 | $289.02 | -21.5% |
| ATI (ATI) | $180.69 | $157.94 | -12.6% |
| Howmet Aerospace (HWM) | $208.15 | $191.92 | -7.8% |
| SPDR S&P Aerospace & Defense ETF (XAR) | $222.64 | $216.57 | -2.7% |
| iShares U.S. Aerospace & Defense ETF (ITA) | $205.79 | $202.98 | -1.4% |
| SPDR S&P 500 ETF (SPY) | $773.09 | $764.35 | -1.1% |
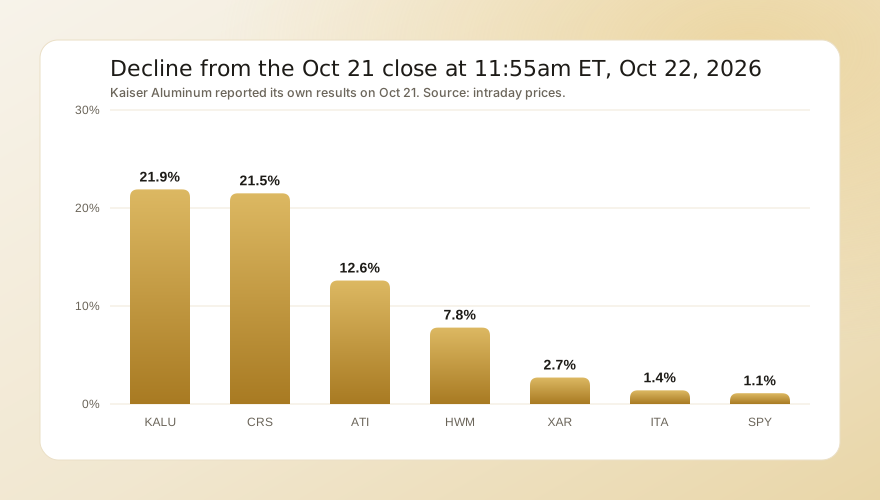
Kaiser Aluminum reported third-quarter EPS of $1.89 against $2.37 expected after the close on Oct 21, so its drop has its own cause. ATI, which had not reported, fell 12.6%, and Howmet 7.8%. That says part of Carpenter's drop is the whole aerospace metals group being marked down on the same morning, not just its own report. The aerospace and defense ETFs fell far less, so the selling is in the suppliers, not in the planemakers and defense primes. For a related name, see our page on GE Aerospace and the rest of today's biggest stock moves.
After the drop, RSI(14) stood at 11, the shares sat 33% below their 50-day average and 35% below their 200-day average, and the stock was 54% below its 52-week high of $625.99.
The numbers
For the quarter ended Sept 30, 2026, the first of fiscal 2027:
| Measure | Q1 FY2027 | Q1 FY2026 |
|---|---|---|
| Net sales | $798.2 million | $733.7 million |
| Sales excluding surcharge | $634.8 million | $603.1 million |
| Operating income | $196.4 million | $153.3 million |
| Diluted EPS | $3.25 | $2.43 |
| Specialty alloys operating margin, adjusted | 37.7% | 32.0% |
| Free cash flow | -$24.8 million | -$3.4 million |
The specialty alloys segment earned $216.3 million, up 27% from a year earlier and down 6% from the fourth quarter. Total liquidity was $658.6 million, including $159.5 million of cash. CEO Tony Thene called it "the most profitable first quarter in the Company's history" and said Carpenter is "working on specific actions and projects to exceed our operating income targets for fiscal year 2027 and fiscal year 2029." Our explainer on how guidance changes move stocks covers why a flat next quarter can outweigh a kept full-year range on the day.
The bull case
- Demand. Management said "demand is accelerating, not declining" and that no customer is talking about slowing down. Distribution and structural bookings rose 23% from the prior quarter and 49% from a year earlier; engine bookings rose 10% and 22%.
- Inventories are falling at customers. Management said most structural and distribution customers report lower inventories, which supports orders.
- Pricing. Recently signed long-term agreements carry higher prices, and margins held at a record level through a maintenance quarter.
- Buybacks. $985 million remains under the repurchase program, about 7% of the company's market value after the drop. Our explainer on buybacks as catalysts covers when that matters.
- Valuation. The average analyst target is about $522, set before the report, with a low of $425.
The risks
- A second-half ramp. The full-year range needs second-half operating income about 18% to 24% above the first-quarter rate.
- Two sales misses. Fourth-quarter fiscal 2026 sales of $851.0 million also fell short of estimates, so the top line has missed twice in a row.
- Defense. Defense bookings fell from both the prior quarter and a year earlier because of delayed federal funding.
- A sector losing favor. The stock was down 20% from its Sept 9 close before the report, and its peers fell with it on Thursday.
What comes next
- Fiscal second-quarter results, expected in late January. Operating income against $192 million to $197 million, and whether the second-half ramp starts to show. Our guide to what to check before an earnings report lists what to line up in advance.
- Free cash flow. The CFO expects cash generation to accelerate as first-quarter inventory is worked down; the $400 million to $430 million target is the test.
- Buyback pace. Another quarter near $134 million would retire about 1% of the shares at today's price.
- Aerospace build rates. Management cited projected 2026 builds of about 1,400 to 1,500 planes against target rates above 2,100.