

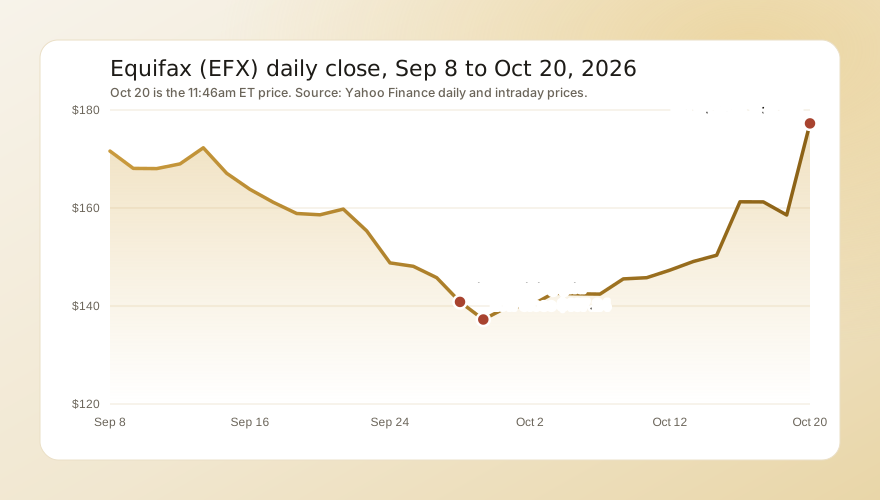
Oct 20, 2026: a soft premarket, then a 12% climb through the call
Equifax released results at 6:30am. Investing.com, in a report on the guidance, said the shares "edged down 1.01% in pre-market trading following the announcement." The earliest recorded trade, at 6:40am, printed at $158.56, a cent below Monday's close. Buyers took over within minutes. The stock traded at $164.00 by 7:05am, $166.18 by 7:15am and $170.00 at 8:40am, up 7.2%, as the 8:30am call got under way. It slipped back to $166.00 at 9:00am.
It opened at $166.72 and dipped to the day's low of $166.11 in the first five minutes, still 4.8% above Monday's close. It reached $175.61 by 9:45am, spent the next hour between about $172 and $176, then pushed to a high of $177.80 at about 11:35am. At 11:46am it was $177.26, up 11.8%, on 1.6 million shares, 0.8 times its 20-day average daily volume.
What pushed it up:
- Earnings held while mortgage revenue fell. The company cut its full-year revenue midpoint by $84 million, to $6.661 billion, almost all from mortgage, but adjusted EPS guidance moved only from $8.39 to $8.69 to $8.45 to $8.55. Begor said AI-driven cost savings "should allow us to principally recover the gross margin impact from lower Mortgage revenue." Our explainer on why guidance changes move stocks covers why the EPS line can matter more than the revenue line.
- VantageScore is gaining in mortgages. Begor said lenders are "moving to implementation mode" and that adoption should "continue to accelerate in 2027." He called FHFA's move to one pricing grid "important to really put on parity Vantage versus FICO." Equifax will hold its $1 price through 2028, and full conversion would add about $35 million of margin.
- No two-bureau decision. Begor said "everything we know is the FHFA has not made a decision to go to BiMerge" and argued that "the tri-merge credit report is essential to expanding consumer access to credit."
- Margins. Adjusted EBITDA margin excluding FICO mortgage royalties was 35.2%, up 130 basis points from a year earlier, and the company raised its full-year margin expansion target on that basis to 100 basis points from 75.
The move was concentrated in the credit bureaus. At about 11:46am, against the Oct 19 close:
| Stock or fund | Oct 19 close | Oct 20, 11:46am | Change |
|---|---|---|---|
| Equifax (EFX) | $158.57 | $177.26 | +11.8% |
| TransUnion (TRU) | $73.12 | $78.42 | +7.3% |
| S&P Global (SPGI) | $427.83 | $436.65 | +2.1% |
| Fair Isaac (FICO) | $781.07 | $793.77 | +1.6% |
| SPDR S&P 500 ETF (SPY) | $766.48 | $769.23 | +0.4% |
| Moody's (MCO) | $481.26 | $482.12 | +0.2% |
| Industrial Select Sector SPDR (XLI) | $166.68 | $166.46 | -0.1% |
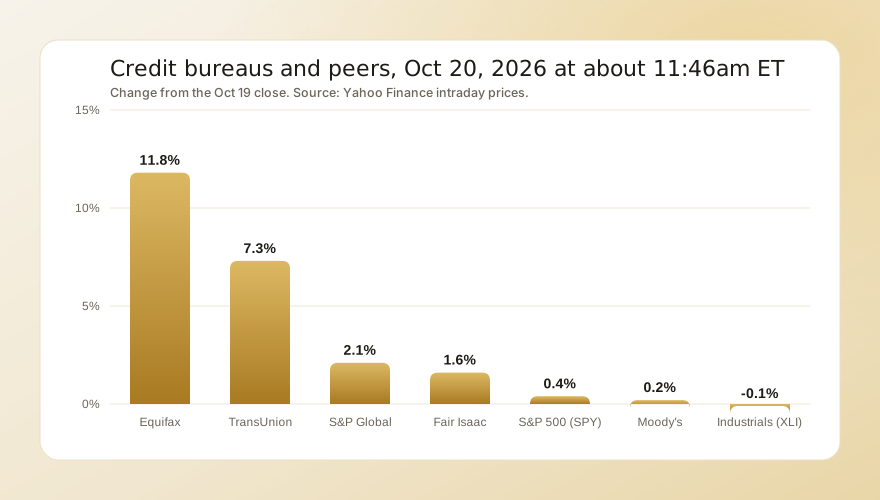
We found no TransUnion release on Oct 20. Its 7.3% gain reads as sympathy: it shares the mortgage exposure, part-owns VantageScore and faces the same two-bureau risk. It reports on Oct 27. Fair Isaac rose only 1.6%. More of today's biggest stock moves are on our market page.
After the gain, RSI(14) stood at 71, the shares sat 6% above their 50-day average and 1% below their 200-day average, and the stock was 26% below its 52-week high of $238.94.
How the stock got here
Credit-score policy drove the selling into the report. On Sep 4, Investing.com reported, FHFA Director Bill Pulte directed Fannie Mae and Freddie Mac to approve all lenders using VantageScore and accused the three bureaus of overcharging consumers; Equifax fell 6.4% that day to $177.05. On Sep 28, Pulte said on X that the two agencies were "moving to ONE PRICING GRID" for Classic FICO and VantageScore 4.0, removing a 20-point adjustment that had applied to VantageScore, HousingWire reported. Fair Isaac fell 26.5% the next day, and Equifax fell 3.4% to $140.83, then to a low close of $137.24 on Sep 30. On Oct 2, Investing.com reported, citing Bloomberg, that FHFA was weighing a rule letting lenders use only two of the three bureaus, and Equifax was indicated down 3.4% before the open.
The stock started recovering before the report, closing at $161.26 on Oct 15, up 7.3% that day. Monday's close of $158.57 was still below early September levels, so the beat landed on a stock that had priced in a lot of bad news. Our explainer on regulatory decisions as catalysts covers how to weigh a pending agency decision.
The numbers
| Q3 2025 | Q3 2026 | Change | |
|---|---|---|---|
| Revenue | $1,544.9M | $1,692.5M | +10% |
| Workforce Solutions | $693.9M | +7% | |
| USIS | $599.1M | +13% | |
| International | $399.5M | +9% | |
| Adjusted EPS | $2.04 | $2.26 | +11% |
| GAAP diluted EPS | $1.29 | $1.79 | +39% |
| Adjusted EBITDA margin | 32.7% | 33.1% | +0.4 pts |
| Guidance | July | Oct 20 | Consensus |
|---|---|---|---|
| FY 2026 revenue | $6.710B to $6.780B | $6.646B to $6.676B | |
| FY 2026 adjusted EPS | $8.39 to $8.69 | $8.45 to $8.55 | $8.49 |
| Q4 2026 revenue | $1.605B to $1.635B | $1.682B | |
| Q4 2026 adjusted EPS | $2.07 to $2.17 | $2.18 |
U.S. mortgage revenue rose 15%, but only about 1% excluding FICO royalties, which Equifax passes through at no margin. Begor said "we do not make any money today when we sell a FICO score." The company now expects mortgage revenue about $20 million lower in the third quarter, about $60 million lower in the fourth and about $80 million lower for the year than it guided in July. Gamble said the company expects mortgage transactions in 2027 to fall by a high single-digit percentage on average from 2026, and that "we are not going to give 2027 guidance" yet.
The bull case
- The non-mortgage business is growing. Diversified Markets revenue rose 8%, led by Workforce Solutions verification revenue outside mortgage, up 13%, and talent solutions, up more than 20%. The new product Vitality Index reached a record of over 17%.
- VantageScore economics. Begor cited "the substantial $1 billion annual savings opportunity for mortgage originators and consumers." FHA loans through Ginnie Mae begin accepting VantageScore on January 1, 2027.
- Cash returns. Equifax returned $158 million in the quarter, $92 million in buybacks and $66 million in dividends, and Begor said excess free cash flow "substantially ends up in buyback." Our explainer on buybacks as catalysts covers when repurchases matter.
- Valuation. The forward P/E is 18, and the consensus price target is $202.31, with a range of $148 to $245. Our piece on forward versus trailing P/E explains why the forward figure fits here, with GAAP earnings weighed down by acquisition amortization.
The risks
- A two-bureau rule. The decision rests with FHFA, and Pulte has used public posts to move these stocks before. A bi-merge rule would cost about $80 million of revenue a year at 2026 levels, by the company's estimate.
- Mortgage rates. At about 7.5%, rates are well above the 6.6% the company planned for in July, and the fourth-quarter guide already assumes the weak market continues.
- A sharp run. The stock is up 29% from the Sep 30 low, and RSI(14) at 71 suggests much of the relief is already in the price.
What comes next
- TransUnion results on Oct 27. Its mortgage commentary and VantageScore numbers will test whether Equifax's trends hold across the group.
- Any FHFA statement on bi-merge or score pricing. This is the single largest swing factor for the stock.
- The Círculo de Crédito deal. Equifax expects to close the $750 million Mexican credit bureau acquisition in the fourth quarter.
- Fourth-quarter results around February 3, 2027. The company will report against $2.07 to $2.17 of adjusted EPS and is likely to give its first 2027 outlook.