

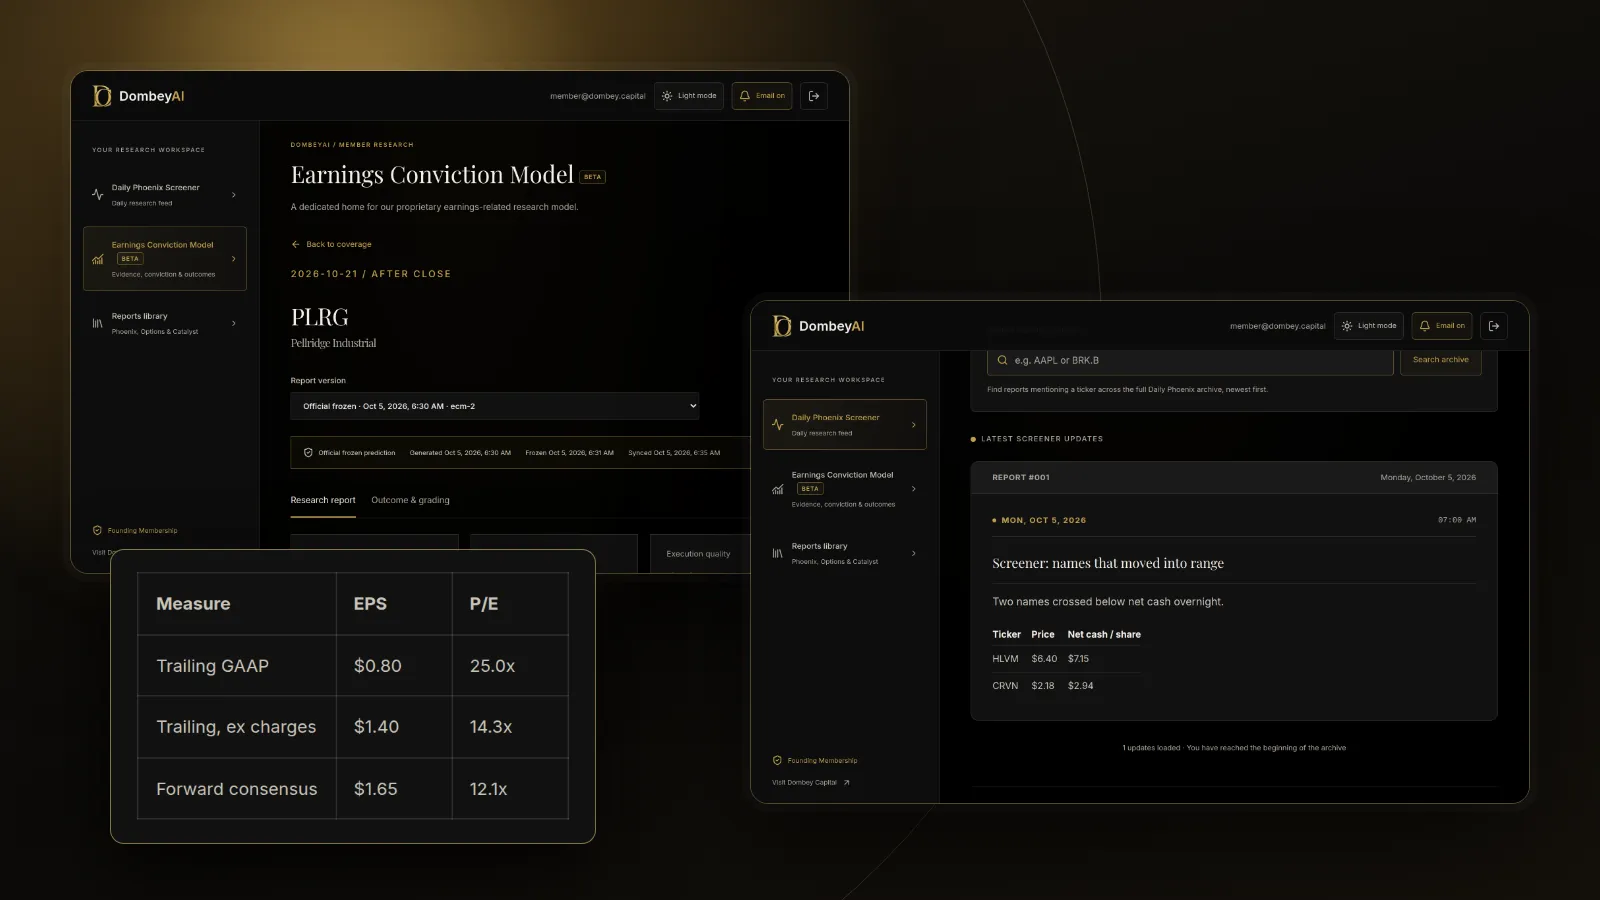
How each ratio is built
Trailing P/E = share price / diluted EPS for the last twelve months (TTM)
Forward P/E = share price / estimated EPS for the next twelve months (NTM) or the next fiscal year
Trailing EPS comes from filings. Add diluted EPS for the last four reported quarters, or take the last fiscal year from the 10-K and roll it forward with the year-to-date figures in the latest 10-Q. Our explainer on the 10-Q and how it differs from a 10-K shows where those numbers sit.
Forward EPS comes from estimates. Most data sites use a consensus of sell-side analyst forecasts. Some use the company's own guidance. A few blend the current fiscal year and the next one to produce a rolling twelve-month figure. These choices are rarely shown on the page, which is why the same stock can carry three different forward P/E figures on three different sites.
Two details change the answer more than most investors expect:
- Diluted or basic shares. Use diluted EPS. Options, convertible notes and restricted stock add to the share count, and basic EPS overstates what each share earns.
- GAAP or adjusted earnings. Many forward estimates are built on adjusted earnings that exclude items such as stock compensation, amortization of acquired intangibles or restructuring charges. Trailing figures on the same site may be GAAP. Comparing one with the other mixes two different measures.
Quick reference
| Trailing P/E | Forward P/E | |
|---|---|---|
| Earnings used | Last 12 reported months | Next 12 months or next fiscal year, estimated |
| Source | 10-Q and 10-K filings | Analyst consensus or company guidance |
| Main strength | Based on reported results | Reflects expected change |
| Main weakness | Stale, distorted by one-off items | Estimates are often wrong, usually optimistic |
| Best for | Stable, mature businesses | Turnarounds, fast growers, post-restructuring |
| Fails when | The past year was unusual | The estimate has no visible mechanism |
When trailing P/E is the better tool
Trailing P/E works best when the last twelve months are a fair picture of what the business earns in a normal year. That usually means a mature company with steady demand, no recent acquisitions or disposals, and no large one-off charges.
Its strength is that the earnings happened. They were reported in filings that carry legal liability, and the annual figures were audited. Nothing in the denominator depends on someone's forecast.
Trailing P/E is also the right baseline even when you end up relying on forward P/E. Before accepting an estimate, you should know what the company actually earned. If the forward figure implies earnings 60% above anything the company has reported, the trailing number tells you that the estimate is a bet on change, not an extension of the past.
When forward P/E is the better tool
Forward P/E earns its place when the past year is plainly not the future. Common cases:
- A completed restructuring. Severance, plant closures and write-downs depressed reported earnings, and the cost savings land next year.
- A disposal or spin-off. The company sold or separated a business, so trailing earnings include profits or losses it no longer owns. The guide to sum-of-the-parts valuation covers how to value the pieces separately.
- A one-year cost shock. A spike in freight, energy or input costs that has already reversed.
- Rapid growth. A company growing earnings quickly can look expensive on the past year and reasonable on the next.
- Emergence from bankruptcy. Fresh-start accounting can make historical earnings close to meaningless. Our piece on post-bankruptcy equities explains why.
In each case, the useful forward figure is one you can explain. You should be able to say where the extra earnings come from: which costs fall away, which revenue remains, what the new share count is. If you cannot, the forward P/E is someone else's opinion with a decimal point.
Reading the gap between the two
The ratio of trailing P/E to forward P/E tells you how much earnings change the market already expects.
- If forward P/E is much lower than trailing P/E, the price assumes earnings rise. The question is whether that rise is already in the price.
- If forward P/E is close to trailing P/E, the market expects earnings to hold roughly flat.
- If forward P/E is higher than trailing P/E, the price assumes earnings fall. Look for the reason: a contract ending, a patent expiring, a one-off gain dropping out of the base.
The gap is most useful around dated events. Before an earnings report, a forward P/E tells you what consensus expects. After the report, watch how the estimate moves. Our explainer on preparing for an earnings catalyst covers what to write down beforehand, and the earnings call transcript tools roundup covers where to read what management said about the next year.
Worked example
Company A reported net income of $40 million over the last twelve months, or $0.80 per diluted share. Trailing P/E is 25. That year included $30 million of after-tax restructuring charges from closing two plants. The closures finished last quarter, and the company disclosed annual savings of $15 million after tax. Without the charges, the base business earned $70 million, or $1.40 per share. Add the savings and next year's earnings could reach about $85 million, or $1.70 per share. Consensus sits at $1.65. Forward P/E is about 12.
Company B reported net income of $90 million, or $1.80 per share, for a trailing P/E of about 11. That figure includes a $35 million after-tax gain on the sale of a building. Its main supply contract, about a fifth of revenue, ends in March. Consensus forward EPS is $1.10, a forward P/E of about 18.
On trailing P/E, Company B looks less than half the price of Company A. On forward P/E, the order reverses. The right answer depends on which year represents the business. Company A's restructuring has a date and a disclosed savings figure, so the forward number has a visible mechanism. Company B's trailing number is flattered by a one-off gain and a contract that is about to end, so trailing P/E overstates what it will earn.
This is the comparison to run whenever a screen sorts by either ratio. Dombey's published research works through this kind of normalization before each catalyst; see the research archive.
Which to use: a decision guide
- If the business is mature and the last year had no unusual items, use trailing P/E and treat forward P/E as a check.
- If the last year included restructuring charges, write-downs or one-off gains, rebuild trailing EPS without them before using either ratio.
- If the company sold, closed or spun off a business, use forward earnings for what remains, or rebuild trailing earnings on a pro forma basis.
- If the forward estimate is well above anything the company has reported, find the mechanism in the filings before relying on it.
- If the company has large debt or cash, read both ratios next to enterprise value multiples, because P/E ignores the balance sheet.
- If earnings are negative in both periods, stop using P/E and use price-to-sales or an asset-based measure.
Adjusted earnings and the SEC rules
Forward P/E often rests on adjusted earnings, and companies report those figures under SEC rules on non-GAAP measures. The SEC's Corporation Finance interpretations say that when a company presents a non-GAAP measure, it must present the most directly comparable GAAP measure with equal or greater prominence and give a quantitative reconciliation between the two. For forward-looking non-GAAP measures, such as adjusted EPS guidance, the rules allow a company to leave out the quantitative reconciliation in some cases, provided it discloses that it is relying on that exception and identifies the information that is unavailable.
In practice, that means:
- Read the reconciliation. For trailing figures, the earnings release shows what was excluded. Large, recurring exclusions, the same "one-time" charge every year, are costs of running the business.
- Treat forward adjusted EPS with care. If guidance excludes items the company cannot yet quantify, the gap between adjusted and GAAP earnings next year is unknown.
- Match like with like. Compare adjusted forward EPS with adjusted trailing EPS, and GAAP with GAAP.
Where this goes wrong
Both ratios have limits that no adjustment fully fixes.
- Estimates drift. Forward estimates for a fiscal year often start high and fall as the year goes on. A forward P/E taken early in the year can look cheaper than it ends up being.
- Thin coverage. Small companies may have one or two analysts, or none. A consensus of one is a single forecast.
- Stale trailing data. Trailing P/E can be up to a quarter old between reports, and much older if the business has changed since.
- Cyclical traps. For cyclical companies, trailing P/E is lowest at the peak of the cycle, when earnings are highest, and highest at the bottom. A low trailing P/E on a cyclical can mean the good years are behind it.
- Share count changes. Buybacks, rights offerings and conversions change the denominator. A forward EPS estimate built on last year's share count will be wrong after a large issuance.
- Balance sheet blindness. Neither ratio sees debt or cash. Two companies on the same P/E can carry very different risk.
Common mistakes:
- Comparing one site's forward P/E with another's trailing P/E. The inputs may differ in period, share count and GAAP treatment.
- Taking consensus on trust. Read how the estimate was built, or rebuild it from disclosed savings and remaining revenue.
- Ignoring the gap. A big difference between the two ratios is the market's forecast. It should prompt a question, not a shrug.
- Using P/E on losses. A negative or tiny denominator produces numbers that mean nothing.
The bottom line
Trailing P/E uses earnings that happened, and forward P/E uses earnings someone expects. Start with trailing P/E as the fact base, then switch to forward P/E only when you can name why the next year will differ and point to the mechanism in the filings. Check whether each figure is GAAP or adjusted, and read both next to enterprise value when debt or cash is large. The gap between the two ratios is the market's forecast, and testing that forecast is most of the work.