

Oct 23, 2026: FICO holds its mortgage price and the stock drops after hours
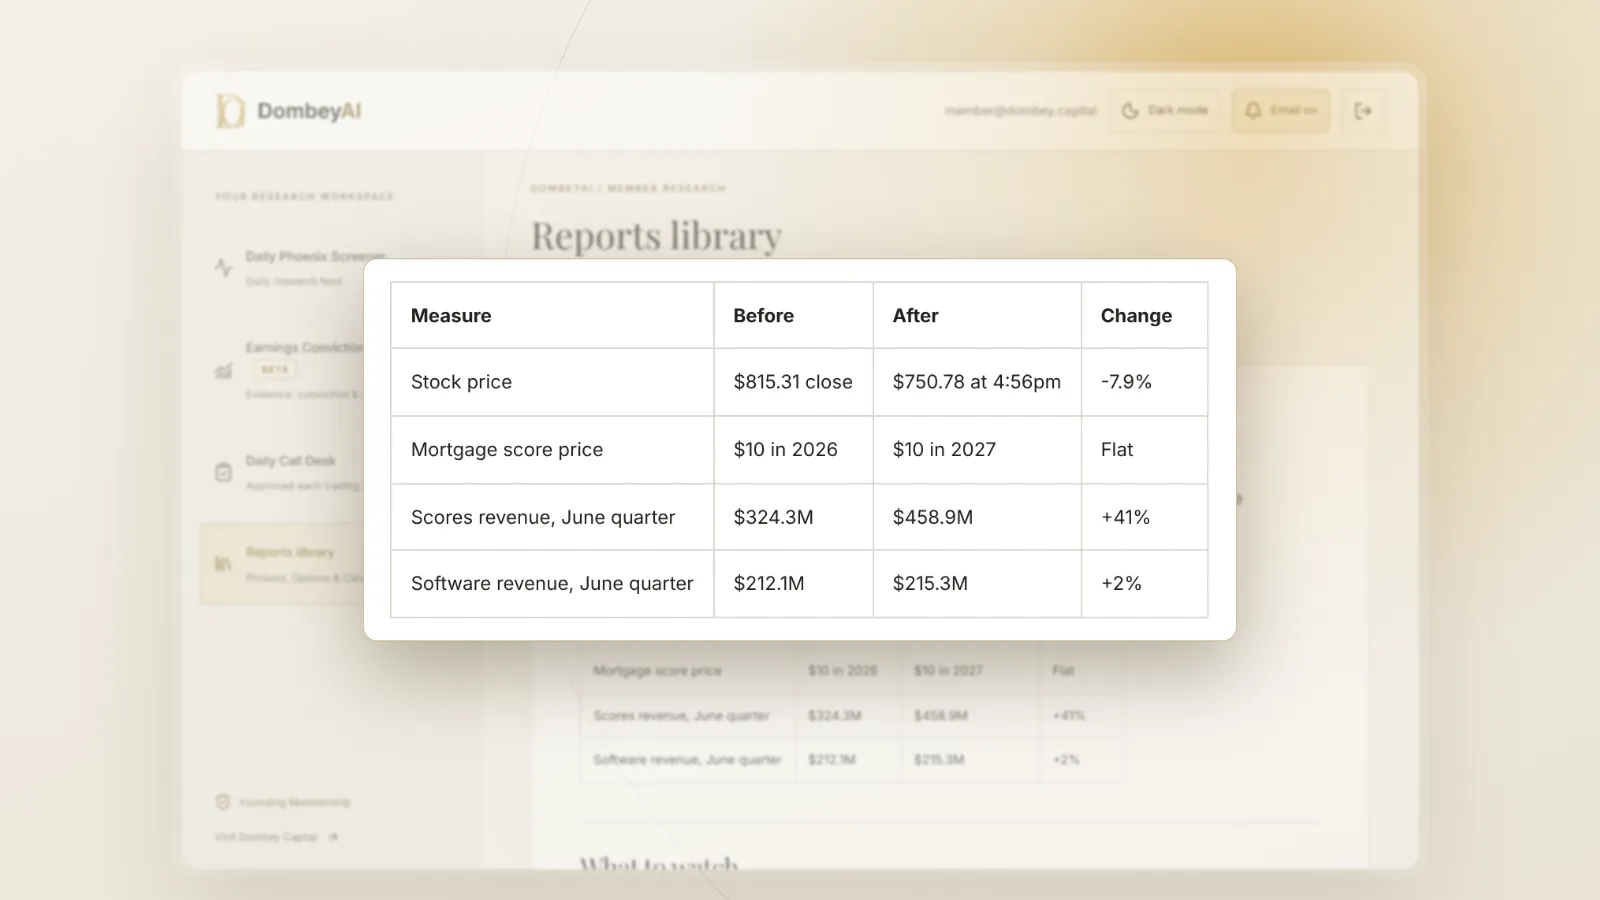
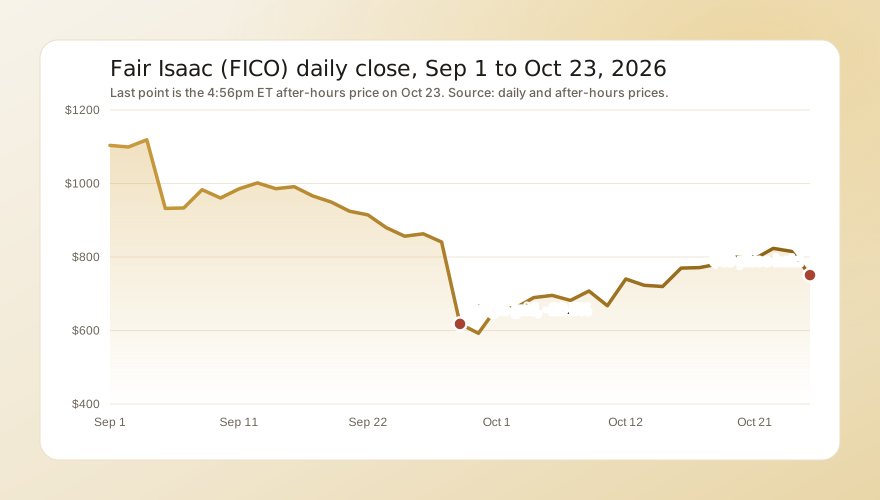
The regular session was quiet. Fair Isaac opened at $818.29, traded between $805.14 and $828.62, and closed at $815.31, down 1.0%, on about 0.4 million shares, a third of its 20-day average. Equifax closed down 2.6% and TransUnion down 2.4%, against a 0.5% loss for the S&P 500 fund SPY. Two days earlier, on Oct 21, FICO had set its fourth-quarter report for Nov 4.
The release came at 4:15pm. The first trade after it printed at $750.00, and the stock fell as low as $717.19 within about ten minutes before settling near $750. At 4:56pm it was $750.78, down 7.9%. The other two bureaus split: Equifax traded at $184.78 at 4:39pm, up 1.3% from its close, and TransUnion at $80.07 at 4:46pm, down 1.7%.
What pushed it down:
- No price increase for 2027. The release says the $10 price is "flat year-over-year" for lenders in the Preferred Program. FICO raised the mortgage price for 2025 and again for 2026, and the June-quarter 10-Q says the 41% rise in Scores revenue came "primarily" from "a higher mortgage origination scores unit price."
- A defensive bundle. FICO now includes FICO Score 10T in the same $10. CEO Will Lansing said the bundle gives lenders "the trusted and predictive tools they need." Read against the September rule changes, it looks like a price held to keep lenders from switching, not a price set from strength.
- Conditions attached. The $10 applies to lenders "who have committed to FICO" through participating resellers. The release gives no enrollment numbers and does not say what other lenders pay.
After the drop, the shares sat about 18% below their 50-day average of $912.23 and 34% below their 200-day average of $1,146.08, and about 60% below the 52-week high of $1,858.91. At the close, before the release, RSI(14) was 52.
Why price matters so much to FICO
FICO has two segments, and one of them does nearly all the growing. In the quarter ended June 30, 2026, total revenue rose 26% to $674.2 million. Scores revenue rose 41% to $458.9 million, about 68% of the total, and Scores operating margin rose to 91% from 88%. Business-to-business scores revenue, which holds the mortgage scores, rose 49%. Software revenue rose only 2%, to $215.3 million. FICO raised its fiscal 2026 guidance in July to $2.53 billion in revenue and $42.43 in non-GAAP EPS, and the stock was above $1,100 in early September.
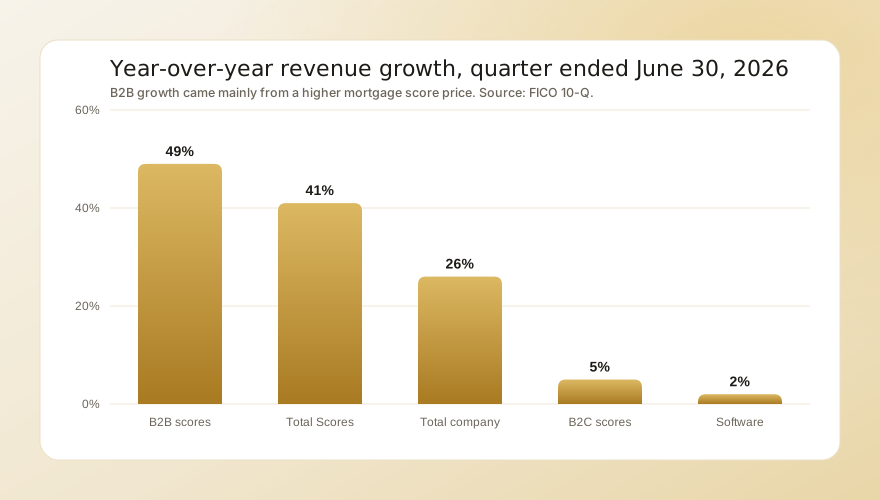
Each dollar of mortgage price falls almost straight to operating income at a 91% segment margin, which is why the price decision matters more to the stock than any software metric. For how a single number in an outlook can reset a stock, see why guidance changes move stocks.
The price has been contested for a year. In October 2025, FICO launched a direct license program with a $4.95 royalty per score plus a $33 fee per borrower at loan closing, or $10 per score through tri-merge resellers, HousingWire reported. Since then the regulator has moved against FICO. On Sept 28, FHFA Director Bill Pulte said Fannie Mae and Freddie Mac would use one pricing grid that accepts VantageScore alongside the Classic FICO Score. The stock fell 26.5% the next day, its worst day since 1989, Barron's reported, and closed at $592.47 on Sept 30. On Oct 6 FICO said it would cut about 15% of its workforce, with a $27 million pretax charge in the fourth quarter.
The bull case
- The stock is no longer expensive. At $750.78 it trades at about 15 times the fiscal 2027 consensus EPS of $48.92. The consensus price target is about $1,140, though the lowest target is $700.
- The 2026 increase stays in place. Holding $10 is not a cut. FICO keeps the price that drove the 49% gain, and because its fiscal year starts Oct 1 while mortgage prices run by calendar year, the quarter ending Dec 31, 2026 should still compare against 2025 pricing.
- Costs are coming down. The 15% staff cut should lift margins in fiscal 2027, and FICO raised its 2026 outlook as recently as July.
- The stock had already recovered. It rose 37.6% from the Sept 30 low to Friday's close, a sign buyers see value below $600.
The bear case
- The growth engine is flat. With no mortgage price increase in 2027, growth has to come from loan volume, consumer scores and a software segment that grew 2%. The fiscal 2027 consensus of $2.77 billion in revenue, up 9.5%, was set before today.
- VantageScore is gaining fast. Equifax said on Oct 20 that about 2,000 mortgage lenders now use VantageScore, up from about 300 in April, that it scored about 5% of loans securitized in September, and that it will keep a $1 price through 2028. The Wall Street Journal reported that Rocket Mortgage made VantageScore its preferred model and that United Wholesale Mortgage pulls both scores and uses the higher one.
- The regulator is not done. The Journal reported that Pulte has more changes planned, including to long-standing credit report requirements.
- The balance sheet leaves little room. Long-term debt was $5.28 billion at June 30, against a stockholders' deficit of $4.10 billion,.
- Short sellers are positioned. Short interest is 10.8% of the float, so a weak outlook on Nov 4 meets an existing short base rather than surprised holders. See short interest and squeeze risk.
What comes next
FICO reports fourth-quarter fiscal 2026 results on Nov 4 after the close, with a call at 5:00pm ET. The quarter itself should look strong, since it ran entirely at 2026 pricing. The number that matters is the fiscal 2027 outlook, and whether management says how many lenders have joined the Preferred Program and what share of mortgage volume they represent. Read how to prepare for an earnings report before the call, and compare forward and trailing P/E before treating 15 times next year's earnings as cheap for a company whose pricing power is now in question. TransUnion reports its own third-quarter results on Oct 27 and will say how fast VantageScore is growing on its side. For more of the day's moves, see today's biggest stock moves. Dombey's published research on special situations is in the research archive.