

Oct 20, 2026: a beat, a raised outlook and a 52-week high
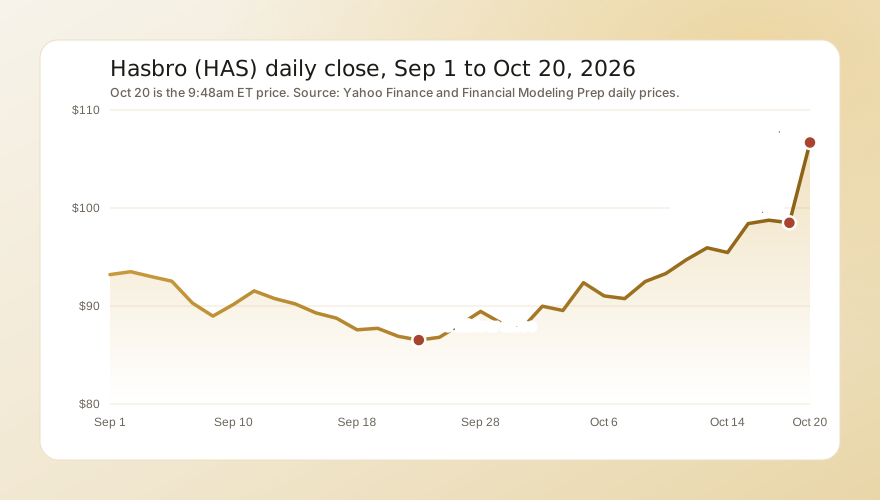
Hasbro reported before the open. Reuters said the shares were up about 1% in premarket trading, so the market did not rush in at first. The stock opened at $102.40, fell to a low of $101.50 in the first minutes, then climbed through the first half hour to a high of $108.30. At 9:48am it was $106.68, up 8.3%, on 1.8 million shares. For a longer view of how results move stocks, see our guide to what an earnings catalyst is.
What lifted it:
- Revenue and profit beat by wide margins. Revenue of $1,595.3 million was up 15% from $1,387.5 million a year ago. Net earnings were $394.5 million, or $2.77 a share, against $233.2 million, or $1.64, last year. Adjusted operating profit rose 52% to $541.2 million, a 33.9% margin.
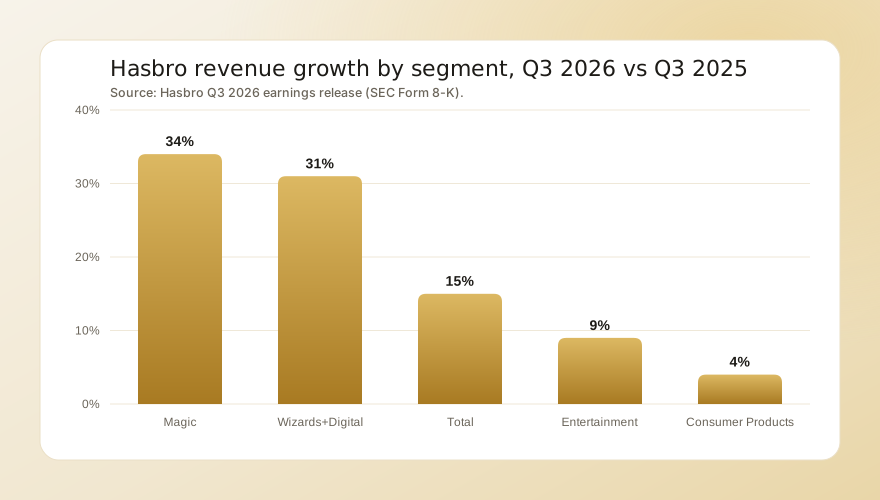
- Magic set a record. Wizards of the Coast and Digital Gaming revenue rose 31% to $747.2 million, and Magic: The Gathering alone rose 34% to $616.1 million. Reuters noted the segment has now grown for seven straight quarters.
- The outlook went up. Hasbro now expects 2026 revenue to grow 7% to 9% in constant currency, up from 5% to 7%, and an adjusted operating margin of 27% to 28%, up from 25% to 26%. The midpoint of the new adjusted EBITDA range is $1.6 billion, 8.5% above the old midpoint of $1.475 billion. Our page on why guidance changes move stocks explains why a raise often matters more than the quarter itself.
- Cash returns went up. Hasbro said it doubled its 2026 share repurchase target. The release did not give a dollar amount. The quarterly dividend stays at $0.70 a share, payable Dec 2 to holders of record on Nov 18. See when buybacks matter as catalysts.
What held it back:
- Tariff refunds helped the quarter. Adjusted operating profit included about $55 million of tariff refunds. Without them, profit was about $486 million, still up roughly 37% from last year by our arithmetic, but the extra $55 million is not a run rate.
- Toys grew slowly. Consumer Products revenue rose 4% to $827.9 million, helped by Marvel, K-Pop Demon Hunters and Transformers collectibles, Reuters reported. That segment is 52% of revenue. Entertainment revenue was $20.2 million, up 9%.
CEO Chris Cocks said in the release, "Inspiring a lifetime of play is our superpower, and this quarter showed what it can do." An eMarketer analyst told Reuters the company's investment strategy "is paying off."
At 9:48am, from the Oct 19 close:
| Stock or fund | Oct 19 close | Oct 20, 9:48am | Change |
|---|---|---|---|
| Hasbro (HAS) | $98.49 | $106.68 | +8.3% |
| Mattel (MAT) | $16.88 | $17.26 | +2.3% |
| Jakks Pacific (JAKK) | $28.37 | $28.75 | +1.3% |
| Consumer discretionary ETF (XLY) | $114.46 | $115.00 | +0.5% |
| S&P 500 ETF (SPY) | $766.48 | $765.42 | -0.1% |
| Funko (FUN) | $8.31 | $8.17 | -1.7% |
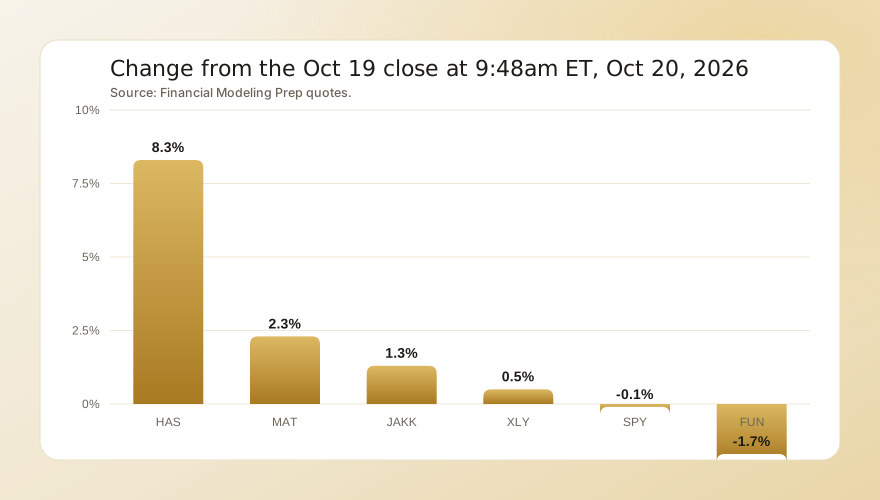
Hasbro rose about four times as much as Mattel and far more than the market, and the other toy makers gave it little help. That points to a company event, not a sector move. For other names moving today, see today's biggest stock moves.
After the jump, RSI(14) stood at 81, the shares sat 15% above their 50-day average and 17% above their 200-day average, volume by 9:48am was already close to its 20-day average of 1.9 million shares, and the stock was 1.7% below its 52-week high of $108.30.
The numbers behind the beat
Revenue by segment, with growth from a year ago:
| Segment | Q3 2026 revenue | Change |
|---|---|---|
| Magic: The Gathering | $616.1 million | +34% |
| Wizards of the Coast and Digital Gaming | $747.2 million | +31% |
| Consumer Products | $827.9 million | +4% |
| Entertainment | $20.2 million | +9% |
| Total | $1,595.3 million | +15% |
Hasbro has beaten the earnings and revenue estimates in each of its last five reported quarters. This one stands out for size: adjusted earnings of $2.90 were 56% above the $1.86 estimate, and revenue was 8% above the Reuters average. The outlook raise is large too. Full-year revenue growth of 7% to 9% on last year's $4,701.3 million implies $5.03 billion to $5.13 billion for 2026. Revenue for the first nine months was $3,735.1 million, so the outlook leaves $1.30 billion to $1.39 billion for the fourth quarter, against $1,445.9 million a year ago. Constant-currency growth ignores exchange rates, so that is an approximation, but it points to a guide that leaves room.
The case for the stock
- Magic is the profit engine. Wizards and Digital Gaming revenue grew 31% to $747.2 million, nearly as large as the $827.9 million Consumer Products segment, and the company's adjusted operating margin reached 33.9%.
- Estimates should rise. The consensus for 2026 revenue was about $5.06 billion before the report, and the midpoint of the new outlook, about $5.08 billion, sits just above it, with margin guidance higher too.
- Capital returns. The doubled buyback and a $0.70 dividend give holders a floor of demand.
- A beat pattern. Hasbro beat earnings and revenue estimates in each of its last five quarters, so a cautious fourth-quarter implied guide fits its history.
The risks
- The price already reflects a lot. The consensus target of $107.60 (range $90 to $123, median $110) was set before today's report, but the stock is already there. Targets will rise, and the stock may need them to.
- One-time help. Tariff refunds were about 10% of adjusted operating profit. Reuters and Hasbro both flag them, and they do not repeat on a schedule.
- Toys are still the larger business. Consumer Products grew 4% and is half of revenue. A weak holiday season would hit the fourth quarter that the outlook already treats cautiously.
- Overbought signals. An RSI of 81 and a price 17% above the 200-day average mean a pullback is common even after good news. We state levels as context, not as buy or sell signals. For how crowded trades can reverse, see short interest and squeeze risk.
What comes next
Mattel is expected to report third-quarter results around Nov 5, which will show whether the toy side of Hasbro's strength is shared. Hasbro pays its dividend on Dec 2 and is expected to report fourth-quarter results on Feb 9, 2027. At the Oct 19 close, the stock traded 8% below the consensus target; the question now is how fast analysts raise it. A view on the cash side also helps: our explainer on free cash flow yield shows how to check whether earnings turn into cash. Dombey's published work on event-driven stocks is in the research archive.