

How goodwill arises in an acquisition
When one company buys another, accounting rules require the buyer to record every identifiable asset and liability of the target at fair value on the closing date. That includes assets the target never carried on its own books, such as customer relationships, trademarks and developed technology. These become "other intangible assets" on the buyer's balance sheet.
Whatever part of the price is left after that exercise becomes goodwill. It is a residual: it captures expected cost savings, the assembled workforce, market position and any overpayment, without separating them.
Two points follow. First, a cash acquisition does not change total book value at closing: $500 million of cash is replaced by $500 million of net assets. Second, it lowers tangible book value by $280 million, the goodwill plus the intangibles, because those assets are excluded from tangible equity.
Other intangible assets are amortized over their useful lives, which produces a steady earnings charge. Goodwill is treated differently.
How US GAAP tests goodwill (ASC 350)
Under ASC 350, public companies in the US do not amortize goodwill. They carry it at its original amount and test it for impairment. Private companies can elect an alternative that lets them amortize goodwill, generally over ten years or less, so the rules below describe public filers.
Where the test happens
Goodwill is assigned to reporting units, which are operating segments or one level below. The test compares the fair value of each reporting unit with its carrying amount, including the goodwill assigned to it. A company with several segments can impair goodwill in one unit while the others pass.
When the test happens
- Annually, on a date the company chooses and keeps consistent, often in the fourth quarter.
- Between annual dates when a triggering event makes it more likely than not that a unit's fair value has fallen below its carrying amount. Common triggers include a sustained decline in the share price, a loss of a key customer, adverse regulation, a planned sale of a unit, or results well below the acquisition plan.
How the test works
A company may first run a qualitative assessment, sometimes called step zero. If the facts suggest fair value is comfortably above carrying amount, it can stop there. Otherwise it runs the quantitative test: it estimates the unit's fair value, usually from discounted cash flows, market multiples or both, and compares it with the carrying amount.
Since the FASB simplified the test in ASU 2017-04, the impairment equals the amount by which the carrying amount exceeds fair value, capped at the goodwill assigned to that unit. The earlier second step, which required a hypothetical purchase price allocation, was removed.
What an impairment does to each statement
The charge touches all three statements, but only one of them in a way that involves money leaving the company.
| Item | Effect of a goodwill impairment | Why |
|---|---|---|
| Goodwill | Falls by the charge | The asset is written down |
| Book value (equity) | Falls by the after-tax charge | The loss flows through retained earnings |
| Tangible book value | No change | Goodwill was never included |
| Reported net income | Falls in the period | The charge is an operating expense |
| Adjusted earnings | Usually unchanged | Most companies exclude the charge |
| Operating cash flow | No change | The charge is added back as non-cash |
| Cash balance | No change | The cash was spent at the acquisition |
| Tax paid | Usually no change | Much goodwill is not deductible for tax |
On the income statement, the impairment is usually its own line within operating expenses. Net income can swing to a large loss in a quarter where the business itself performed normally.
On the balance sheet, goodwill falls and retained earnings fall with it. Book value per share drops, which mechanically raises the price-to-book ratio even if the share price does not move. Our price-to-book ratio explainer covers why that ratio needs this kind of adjustment.
On the cash flow statement, the charge appears as an add-back in the operating section. The cash consequence of the deal happened in the investing section on the day it closed.
Tax treatment depends on how the deal was structured. Goodwill from a stock acquisition is often not deductible, so the impairment brings no tax benefit and the full charge reduces equity. Where goodwill is deductible, part of the charge may be offset by a change in deferred taxes. The income tax note in the 10-K shows which applies.
Worked example: before and after
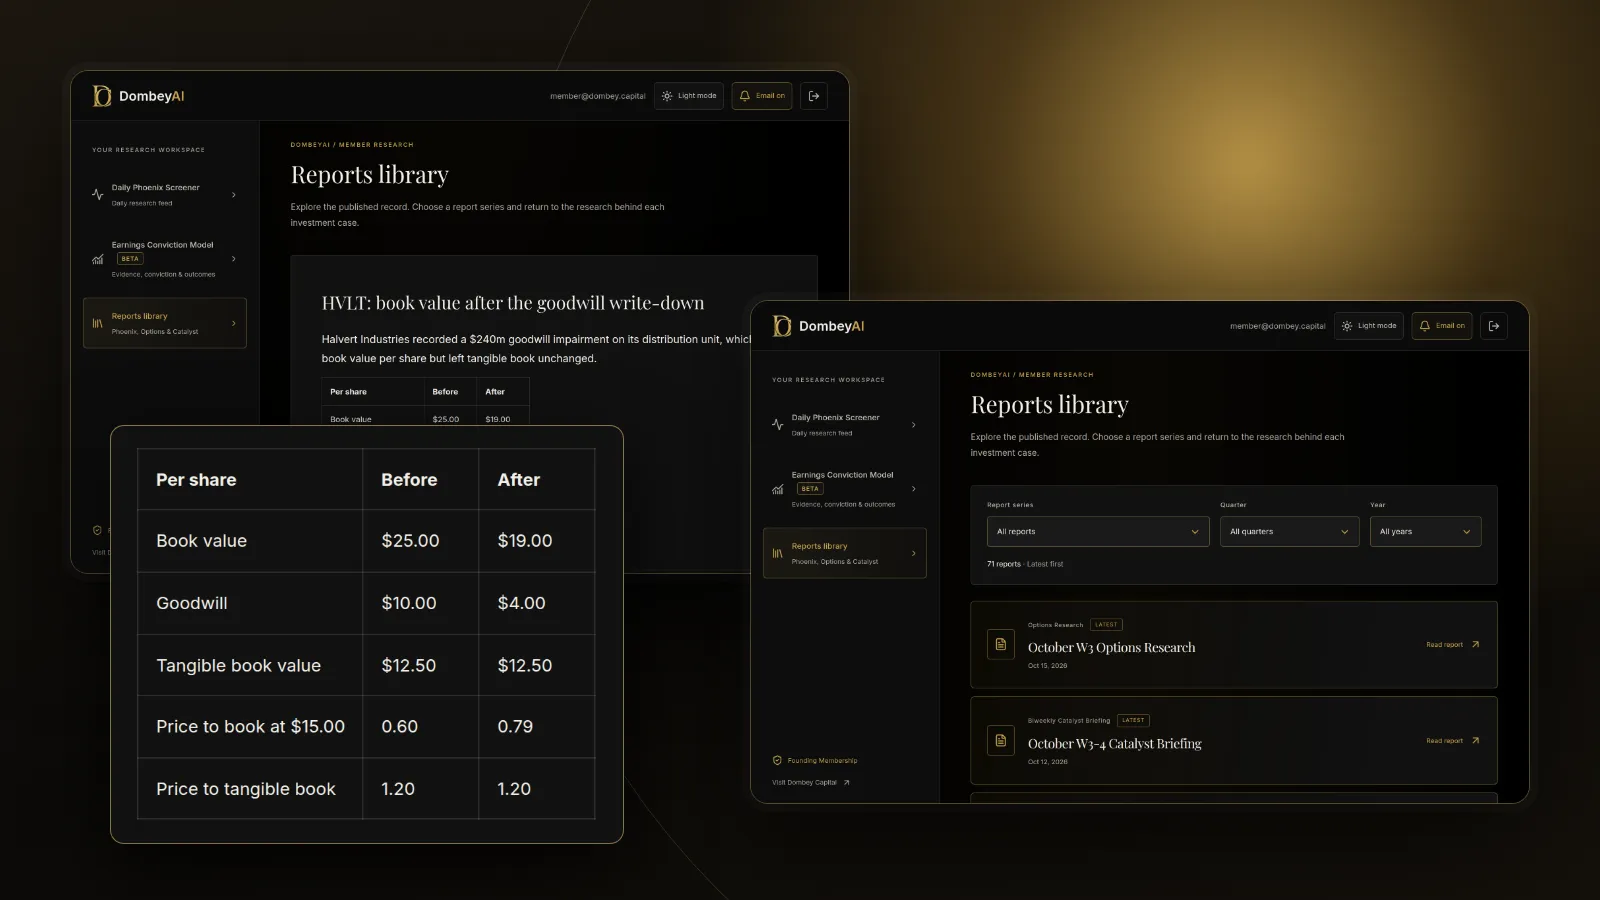
One of Company B's acquired units misses its plan for two years. At the annual test, the unit's fair value comes in $240 million below its carrying amount, so Company B records a $240 million impairment. Assume the goodwill is not tax-deductible.
- Goodwill falls from $400 million to $160 million.
- Book value falls to $760 million, or $19.00 per share.
- Price to book rises from 0.60 to about 0.79 at the same $15.00 share price.
- Tangible book value stays at $500 million, or $12.50 per share.
- Cash, debt and operating cash flow are unchanged.
The screen that flagged Company B at 0.60 times book was measuring a discount that rested on goodwill. Price to tangible book was 1.20 before the charge and is 1.20 after it. The impairment did not change what Company B owns in separable assets. It changed the accounting to match what the market had already concluded.
Why markets often price it in first
An impairment is a lagging signal. The test responds to weaker cash flow forecasts and lower market values, and both usually appear in public data before the charge.
- Results come first. The acquired unit's revenue and margins, often disclosed in segment reporting, decline over several quarters before the annual test.
- The share price comes first. A company whose market value sits below its book value for an extended period is signaling that its assets are worth less than carried. A sustained decline is itself a common triggering event.
- Management warns first. Companies often disclose that a reporting unit's fair value exceeds its carrying amount by only a small margin, sometimes called headroom. That disclosure in the 10-K is a warning that a charge may follow.
When a public company concludes that a material impairment is required, Item 2.06 of Form 8-K requires a filing within four business days, unless the conclusion is made in connection with a periodic report that discloses it on time. Many impairments are therefore announced with quarterly results.
The share price moves on the charge when it brings new information. A write-down paired with a guidance cut, a covenant problem or a change in strategy can matter. A write-down that only confirms known weakness often does not. Our 10-K guide shows where the goodwill note and the critical accounting estimates sit.
How to read goodwill as an investor
Treat goodwill as a record of past capital allocation, then decide how much weight to give it.
- If goodwill is a large share of equity and the acquired units are underperforming, value the company on tangible book and cash flow, not reported book.
- If the 10-K says a reporting unit has thin headroom, assume the impairment is coming and check whether the share price already reflects it.
- If the company has just recorded a large charge, compare the new fair value assumptions with the original deal model to judge how far management's estimates were off.
- If the company keeps making acquisitions after impairing earlier ones, discount its future deal economics.
- If the business is a bank or insurer, use tangible book, because regulators deduct goodwill from common equity tier 1 capital and it does not absorb losses.
Dombey's published research checks goodwill and tangible book for each below-book name before a catalyst; see the research archive. For the broader method, our guide on how to value a company below book walks through the full asset review.
Where this goes wrong
Goodwill analysis can mislead in both directions.
- No impairment is not proof of value. Fair value estimates rely on management's forecasts and discount rates. A reporting unit can pass the test on optimistic assumptions for years.
- Aggregation hides problems. A failing acquisition folded into a large, healthy reporting unit may never trigger a charge, because the healthy business supports the combined fair value.
- Timing is a choice. Companies sometimes take large charges in a weak year or after a management change, so a charge can say as much about timing as about the asset.
- A charge does not mean the business is worthless. It means the price paid was too high relative to today's estimate. The acquired unit may still earn a reasonable return on its current value.
- Excluding goodwill can understate acquisitive businesses. Some acquired businesses earn well above their tangible assets. Tangible book treats them like any other, which can make a sound company look expensive.
- Low price to book can be a trap. If the discount rests on goodwill that is about to be written down, the stock was not as cheap as it looked. Our article on value traps covers this and other warning signs.
The bottom line
Goodwill is the premium paid for an acquisition above its identifiable net assets, and US GAAP requires public companies to test it for impairment rather than amortize it. An impairment cuts earnings and book value but uses no cash and leaves tangible book value unchanged. The charge usually arrives after the market has already marked the stock down, so it rarely tells you something new about the assets. When goodwill is a large part of book value, compare price with tangible book and read the headroom disclosures before relying on a low price-to-book ratio.