

Oct 20, 2026: a second manufacturing approval lifts the stock before the open
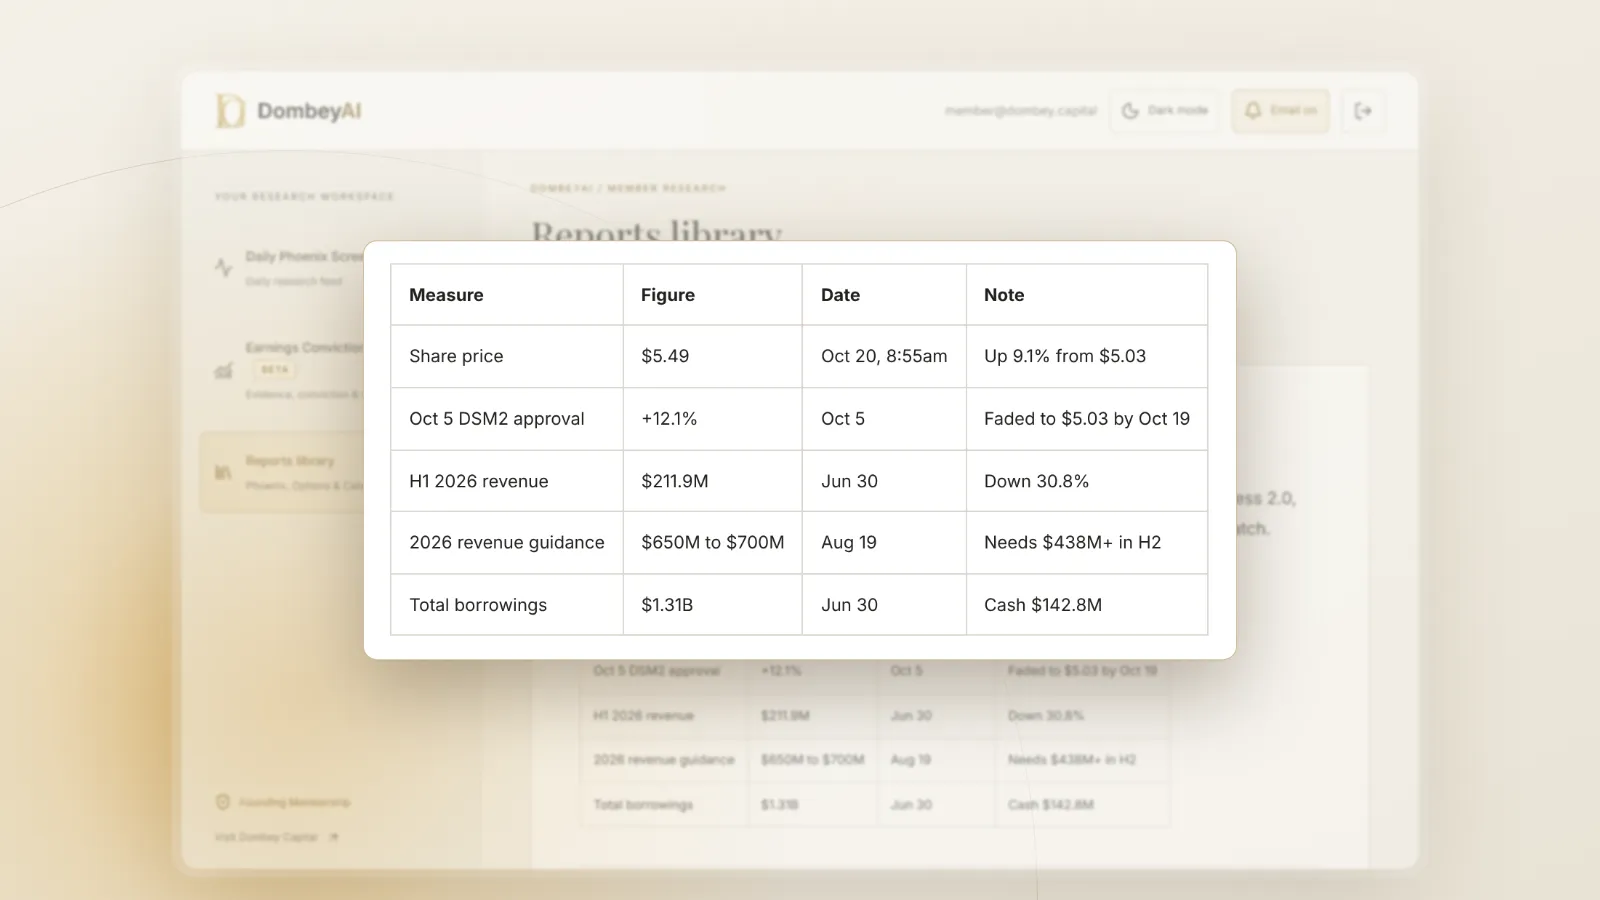
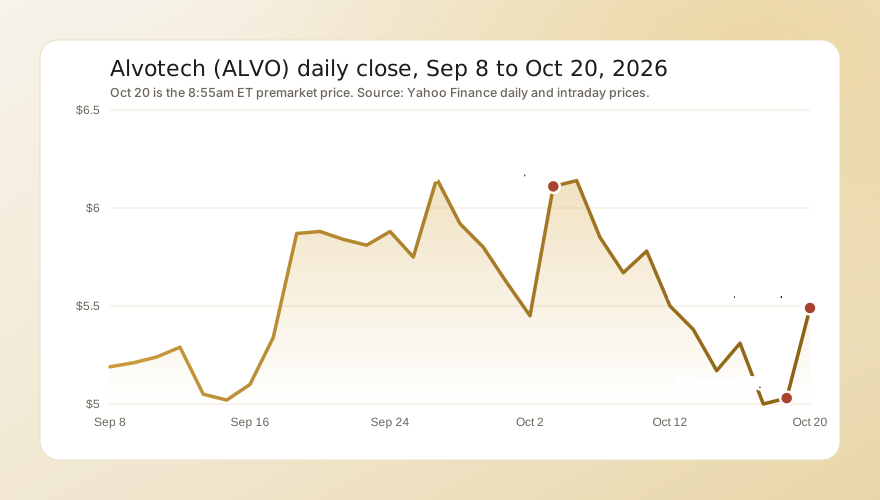
Premarket trading began at $5.19 at 4:30am, and the stock climbed quickly once the release was out. It reached $5.57 at about 5:20am, its high before the open, and held between $5.34 and $5.54 through the rest of the morning. It was $5.45 at 8:43am and $5.49 at 8:55am, up 9.1%.
What lifted it:
- Process 2.0 was approved. The FDA cleared the new process for adalimumab drug substance in the DSM2 suite. Alvotech said comparability with the previously approved process was shown, with product quality, safety and efficacy maintained. Chief Operating Officer Joseph McClellan said it "allows us to manufacture the same quantity of drug substance in fewer batches," freeing capacity for other products.
- It follows the Oct 5 approval. That FDA decision let Alvotech make Simlandi drug substance for U.S. supply in DSM2 as well as DSM1. CEO Lisa Graver said then that adding DSM2 "effectively doubles the drug substance manufacturing capacity available to support U.S. supply."
- More supply is coming. On Oct 6, Alvotech signed a long-term agreement with LOTTE Biologics to make drug substance for several biosimilars at its 40,000-liter site in Syracuse, New York.
The move was specific to Alvotech. Before the open, peers and health care funds moved less than 1%:
| Stock or fund | Oct 19 close | Latest premarket | Change |
|---|---|---|---|
| Alvotech (ALVO) | $5.03 | $5.49 at 8:55am | +9.1% |
| Teva (TEVA) | $41.31 | $41.64 at 8:51am | +0.8% |
| Health Care Select Sector SPDR (XLV) | $175.65 | $176.99 at 8:50am | +0.8% |
| Amgen (AMGN) | $424.94 | $427.62 at 6:05am | +0.6% |
| Viatris (VTRS) | $18.26 | $18.30 at 7:07am | +0.2% |
| SPDR S&P Biotech ETF (XBI) | $147.86 | $147.18 at 8:37am | -0.5% |
Investing.com noted that S&P 500 futures were down 0.2% and Nasdaq futures down 0.6% at the time. For the rest of the morning's movers, see today's biggest stock moves.
Going into the session, RSI(14) stood at 42, the shares sat 2.6% below their 50-day average and 19.5% above their 200-day average, Oct 19 volume ran 0.8 times its 20-day average, and the $5.03 close was 41% below the 52-week high of $8.53.
Why the stock trades near $5
The low share price is the result of a year of plant trouble, not of anything wrong with the products themselves.
- The rejection. On Nov 2, 2025, the FDA issued a complete response letter for AVT05, the proposed Simponi biosimilar, citing deficiencies from its July 2025 inspection of the Reykjavik facility. The FDA named no other problems with the application. The stock fell from $7.65 to $5.03 the next day.
- The guidance cut. In the same release, Alvotech lowered 2025 guidance to $570 million to $600 million of revenue and $130 million to $150 million of adjusted EBITDA, citing a temporary production slowdown while it fixed the facility.
- The slowdown hit 2026. Product and service revenue fell 48% in the first half, to $105.9 million from $204.7 million, and total adjusted revenue fell 30.8% to $211.9 million. The net loss for the half was $65.8 million, against a profit of $141.7 million a year earlier.
- The dilution. In June, Alvotech sold 26.1 million shares in a public offering and 17.8 million in a private placement, all at $3.75, for about $165 million, and added a $75 million term loan. The stock fell 8.7% on June 16, and it touched its 52-week low of $2.94 on June 3. Our explainer on dilution covers why new share sales weigh on a stock.
The repair has since moved forward. Alvotech resubmitted the AVT05 and AVT06 applications on June 4, the FDA closed its April to May inspection with a Voluntary Action Indicated classification, and the stock had climbed back from $3.06 on July 24 to $6.14 on Oct 6. For how these timelines tend to play out, see regulatory approvals as catalysts.
The numbers that matter for the next report
The guidance math is the main test.
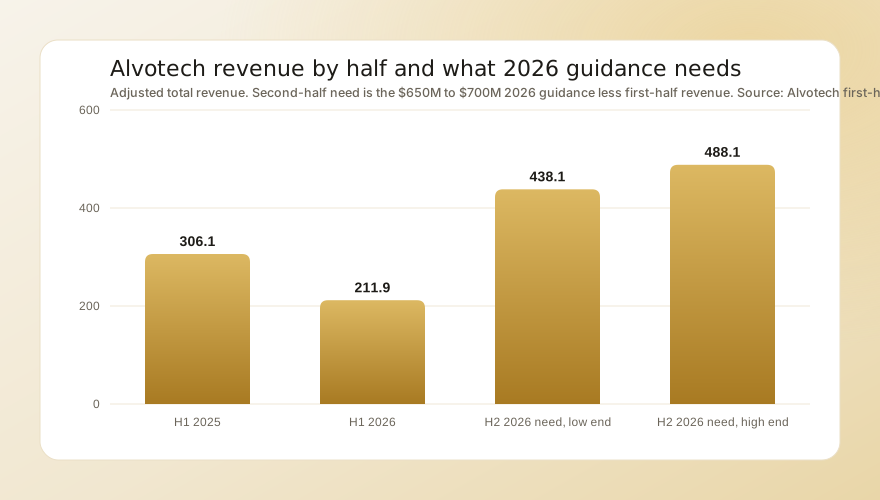
To reach $650 million for the year, the second half must bring in at least $438.1 million, 2.1 times the first half. The company reaffirmed the range on Aug 19 and said demand "remains strong, both in the U.S. and Europe." When a company needs that steep a ramp, the next report decides whether the outlook survives; our guide to guidance changes explains why a cut usually costs more than the miss itself.
The balance sheet at June 30:
| Item | June 30, 2026 |
|---|---|
| Total borrowings | $1,306.0 million |
| Cash and cash equivalents | $142.8 million |
| Total equity | -$191.5 million |
| First-half net loss | $65.8 million |
With equity below zero, the usual debt-to-equity ratio does not apply, and lenders look at cash flow instead. At $5.03, the market value was about $1.79 billion. The forward P/E is 23 and the price-to-sales ratio is 4.4. Short interest is low at 3.7% of the float, and the average analyst target is $7.25.
The bull case
- The plant looks fixed. The November 2025 rejection rested only on the Reykjavik inspection findings. Since then the FDA has closed a new inspection as Voluntary Action Indicated and approved two manufacturing supplements in 15 days.
- Four decisions are due. AVT05 (Simponi), AVT06 (Eylea), AVT03 (Prolia and Xgeva) and AVT16 (Entyvio) all have U.S. applications under review, and Alvotech expects decisions for the first three in the fourth quarter. Our page on FDA decision dates covers how these dates move stocks.
- Capacity is no longer the limit. DSM2, Process 2.0 and the LOTTE site in Syracuse together lift supply well beyond what held back the first half.
The risks
- Revenue has to more than double. Capacity does not create orders, and the low end of guidance already excludes new U.S. launches.
- The last rally faded. The stock rose 12.1% on Oct 5 and fell 17.7% over the next ten sessions, to $5.03.
- Debt and cash. $1.31 billion of borrowings against $142.8 million of cash leaves a thin cushion if approvals slip. Our guide to estimating cash runway shows how to test it.
- Each application stands alone. Alvotech says every pending application remains subject to its own FDA review.
What comes next
- Third-quarter results, expected around November 11. Watch revenue against the $438 million second-half need, product revenue against the $105.9 million first half, and whether guidance holds.
- FDA decisions on AVT05, AVT06 and AVT03, expected in the fourth quarter. The six-month reviews began with the June 4 resubmissions.
- The AVT16 decision. The FDA accepted the Entyvio biosimilar application, and its goal date will set the next catalyst after these.
- Whether the stock holds today's gain. A second fade like early October would say the market wants revenue, not capacity.