

Oct 22, 2026: the FDA accepts the resubmission, and the stock gives back half the gain
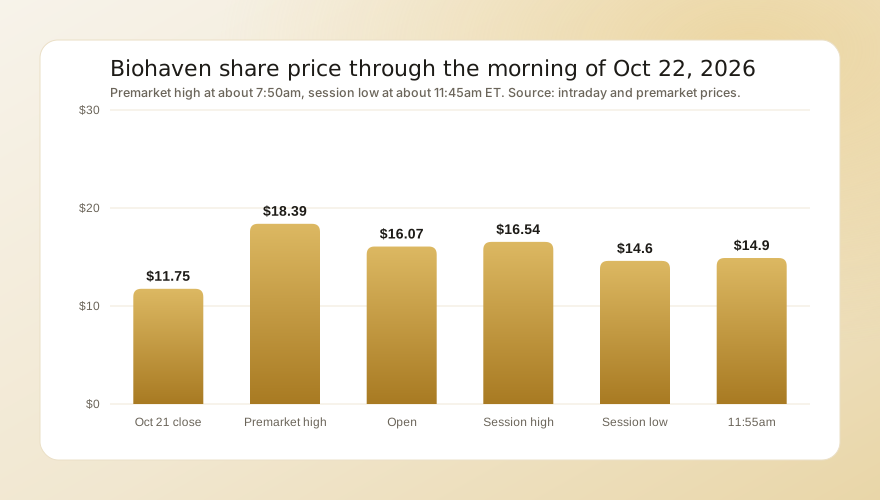
The 8-K came out before the open. The stock traded at $11.60 at 4:00am, reached $18.39 at about 7:50am, up 56.5%, and was $16.09 just before the bell. It opened at $16.07, touched $16.54 at about 9:35am, up 40.8%, and drifted lower all morning to $14.60 at about 11:45am. At 11:55am it was $14.90, up 26.8%. BioSpace reported the shares at $15.41 at 10:40am.
What lifted it:
- The filing is back under review. The FDA considers the resubmission a complete response to the Nov 4, 2025 action letter and assigned a goal date in the first quarter of 2027. Our explainer on how PDUFA dates work covers what that date does and does not promise.
- New analyses. The resubmission "included new positive supportive analyses." Biohaven has not described them publicly.
- An analyst who still likes the drug. William Blair wrote that "the Vyglxia AdCom will be the most de-risking event here" and said it continues to see the risk and benefit as favorable in a disease with no approved therapy, BioSpace reported.
What held it back:
- An advisory committee. The FDA wants outside input before deciding, which keeps the outcome open. The date has not been set.
- The same evidence question. BioSpace reported that the 2025 rejection cited "issues that can be inherent to real-world evidence and external control studies including potential bias," and that FDA feedback before the filing called for a large treatment effect to overcome the biases of an externally controlled trial. Biohaven says its results met that bar.
The path of the day:
| Point | Price | Change from Oct 21 close |
|---|---|---|
| Oct 21 close | $11.75 | |
| Premarket high, about 7:50am | $18.39 | +56.5% |
| Open, 9:30am | $16.07 | +36.8% |
| Session high, about 9:35am | $16.54 | +40.8% |
| Session low, about 11:45am | $14.60 | +24.3% |
| 11:55am | $14.90 | +26.8% |
| SPDR S&P Biotech ETF (XBI), 11:55am | $152.15 | -0.4% |
For other biotech names moving on FDA news, see our pages on Disc Medicine, Rapport Therapeutics and today's biggest stock moves.
After the move, RSI(14) stood at 65, the shares sat 10% above their 50-day average and 23% above their 200-day average, volume ran 12.8 times its 20-day average of 1.9 million shares, and the stock was 20% below its 52-week high of $18.57.
The history: a rejection, a cost cut and two licensing deals
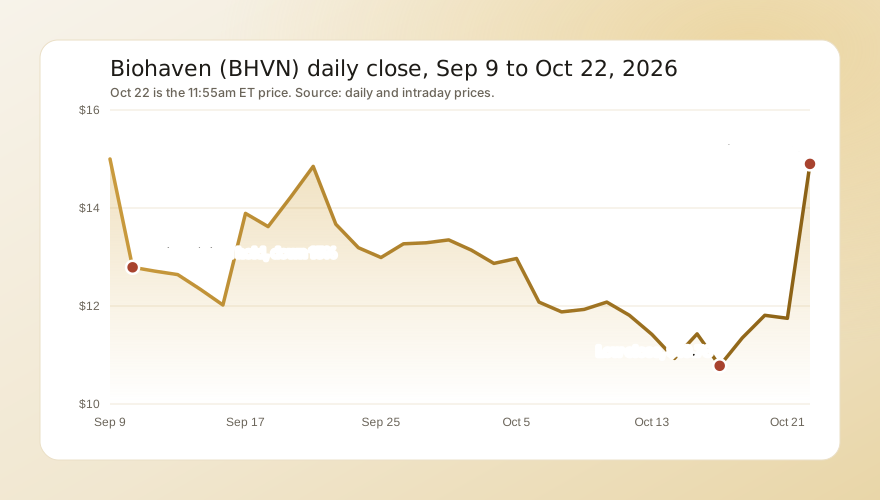
Troriluzole's evidence comes from a three-year study that compared treated patients with a natural history database. BioSpace reported that the Phase 3 study missed its primary endpoint on a modified ataxia rating scale, while comparisons with the natural history controls showed 50% to 70% slower decline at the 200 mg dose. After the Nov 4, 2025 rejection the shares fell nearly 45% to $7.60, and Biohaven cut research spending.
Since then:
- Aug 26, 2026: Biohaven licensed its Kv7 epilepsy drug opakalim (BHV-7000) to SK Biopharmaceuticals for $400 million upfront, $350 million at closing and $50 million a year later, plus up to $150 million in milestones. Closing needs antitrust clearance.
- Sept 4, 2026: The FDA placed a partial clinical hold on BHV-7000 that pauses new enrollment until more animal data on a metabolite are in. The stock fell 14.7% on Sept 10, the day the 8-K was filed, and RBC cut its rating to Sector Perform on Sept 8.
- Oct 8, 2026: Biohaven licensed its IgG degrader portfolio in Japan and parts of Asia to Ono Pharmaceutical for $80 million at closing and $20 million on a later milestone.
Cash, equivalents, marketable securities and restricted cash were about $270.5 million on June 30, 2026. Second-quarter research spending was $100.8 million and general and administrative costs $24.1 million. Our guide on how to estimate cash runway shows how to set those numbers against the cash coming in.
The bull case
- No approved therapy. Spinocerebellar ataxia has no FDA-approved treatment, and advisory committees weigh unmet need.
- A formal path. Acceptance as a complete response means the FDA will rule within a set window, with outside experts heard first.
- Cash on the way. The two licensing deals bring $430 million at closing, more than the cash on hand in June.
- Analyst targets. The average target is about $24.67, set before Thursday, with a range of $11 to $48.
The risks
- Same kind of evidence. The new material is supportive analyses, not a new controlled trial, and the FDA's stated concern was bias in that design.
- An open-ended committee. Without a date, the stock carries the event risk for weeks or months. Our explainer on probability-weighted valuation for binary events shows how to price that kind of yes or no outcome.
- Spending. Quarterly operating costs above $120 million in the second quarter mean the licensing cash matters, and the larger deal has not closed.
- The price already moved. The shares have nearly doubled from the post-rejection low, and the day's fade shows sellers waiting near $16 to $18.
What comes next
- The advisory committee date and briefing documents. The FDA's own review posted before the meeting is usually the first clear read on its view.
- The committee vote.
- The FDA decision, in the first quarter of 2027.
- Third-quarter results, expected around Nov 9. Cash, the status of the SK Biopharmaceuticals closing and spending plans.