

Nov 4, 2026: a second guidance cut and a CFO change
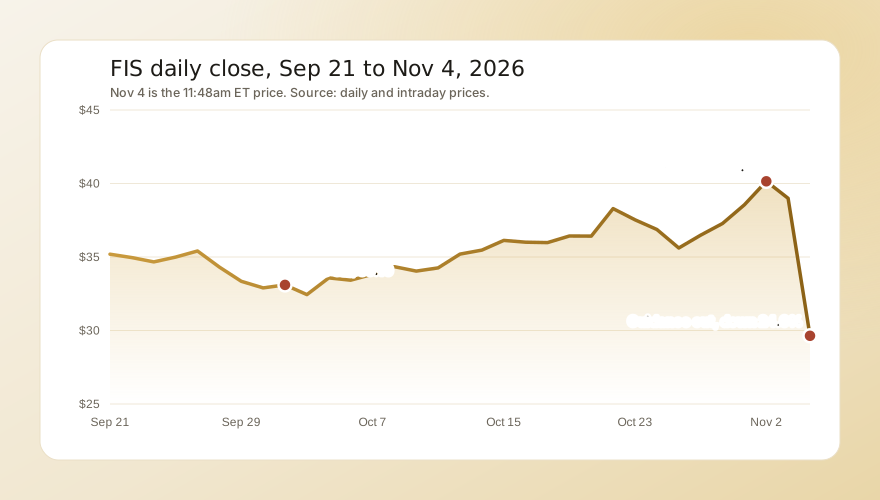
FIS had rallied into the report, from $33.10 on Oct 1 to $40.15 on Nov 2, before closing Nov 3 at $38.99. It released results at 7:30am ET and held its call at 8:30am. Premarket trading ranged from $29.88 to $40.09 as the results came out. The stock opened at $30.58, reached $32.40 at 9:30am and slid to $29.39 at 11:30am. At 11:48am it was $29.64, down 24.0%, on about 16.7 million shares.
What moved the stock:
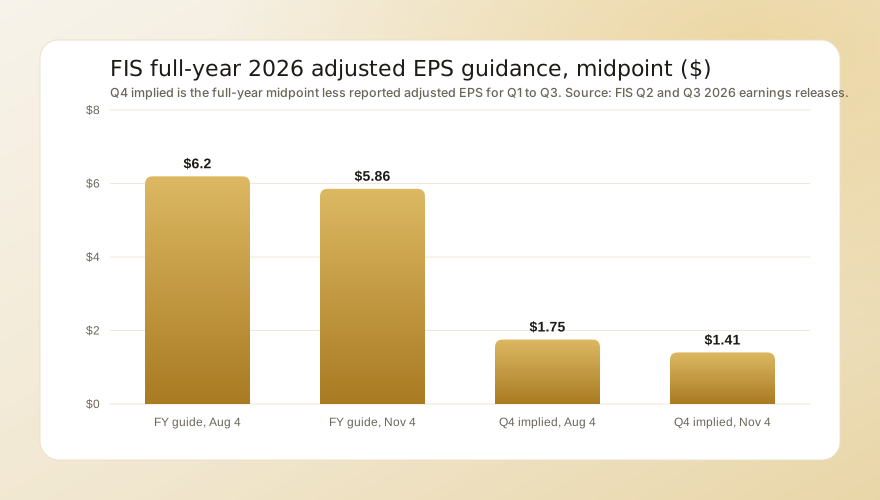
- The outlook came down again. Adjusted EPS growth for 2026 is now 1.2% to 2.4%, against 7.0% to 8.5% in August. Pro forma adjusted EBITDA growth is now 2.9% to 3.6%, down from 5.9% to 6.9% in August and 7.2% to 8.4% before that.
- The fourth quarter looks weak. With $4.45 of adjusted EPS earned in the first three quarters, the new range leaves about $1.37 to $1.44 for the fourth quarter, down from $1.68 a year earlier.
- The CFO is changing. FIS announced a chief financial officer transition and named Alexandra Brooks interim CFO, with the strategic portfolio review still under way.
- Peers did not follow. Global Payments was down 1.2% and Jack Henry up 10.1% at 11:48am, so the selling was about FIS.
Chief executive Stephanie Ferris said FIS is investing in "security and innovation" to build "a more recurring, predictable revenue base." At 11:46am RSI(14) stood at 32, the shares sat 19.4% below their 50-day average and 31.8% below their 200-day average, volume was 2.8 times its 20-day average, and the stock was 56.8% below its 52-week high of $68.37. The rest of the session's movers are in today's biggest stock moves.
The numbers
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $3,454 million | $2,717 million | +27% |
| Pro forma revenue growth | +3.7% | ||
| Banking Solutions revenue | $2,548 million | $1,811 million | +41% |
| Capital Market Solutions revenue | $823 million | $799 million | +3% |
| Adjusted EBITDA | $1,482 million | $1,135 million | +31% |
| Adjusted EPS | $1.61 | $1.51 | +6.6% |
| Free cash flow | $862 million | $798 million | +8% |
Reported growth is inflated by the Total Issuing Solutions acquisition. On a pro forma basis, which treats the business as owned in both years, revenue grew 3.7% and recurring revenue only 2.5%. The adjusted EBITDA margin widened to 42.9%. FIS returned $248 million to shareholders, $227 million of it as dividends and $21 million as buybacks, and sold a non-core prepaid business on Oct 20 for more than $100 million. Our guide to guidance changes covers why a second cut usually hurts more than the first.
The bull case
FIS is cheap on any measure that assumes the outlook holds. At about 5 times guided adjusted EPS and with a free cash flow target equal to about 14% of its market value, the stock prices in a lot of further damage. Margins are rising, free cash flow grew 8% in the quarter, and the dividend continues. The strategic review could also produce sales of non-core businesses that pay down debt faster, which would let buybacks resume. Our page on EV/EBITDA shows why the debt matters when judging a low earnings multiple like this one.
The risks
The core risk is credibility. FIS has now cut its pro forma growth outlook twice in three months, and the implied fourth quarter is well below last year. A CFO change during a strategic review raises the chance of more resets, and our explainer on CEO and management departures covers how markets treat a finance chief change at a moment like this.
The balance sheet limits the options. With $20.8 billion of debt and buybacks on hold, FIS cannot shrink its share count to support per-share earnings, and our guide to debt-to-equity ratios explains why leverage makes small earnings misses matter more. Our page on post-earnings announcement drift covers why stocks that gap down on a guidance cut often keep drifting.
What comes next
The fourth-quarter report and the 2027 outlook are the next real test, likely in late February. Before then, watch for the name of a permanent CFO, any news from the strategic review, and whether the stock holds the $29.39 low set on Nov 4. A close back above $32.40 would undercut the Bearish case.