

Oct 20, 2026: Salesforce buys Braze and Klaviyo is re-rated
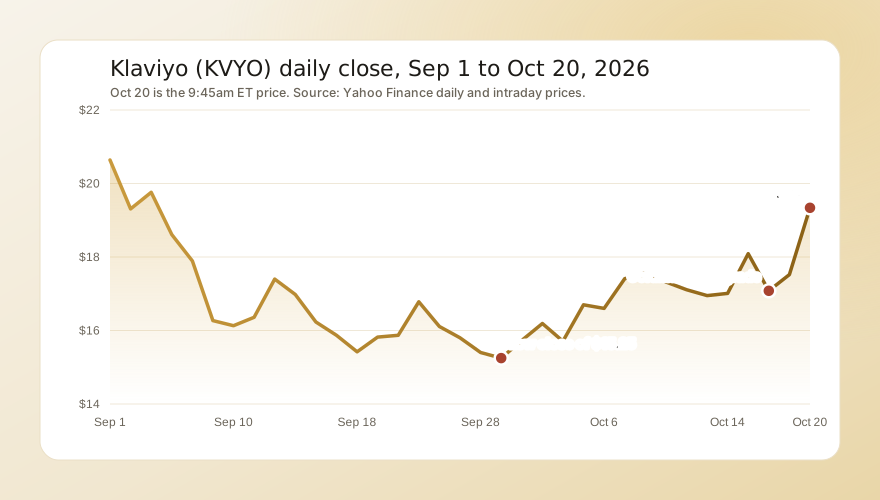
Klaviyo traded at $17.50 when premarket trading opened at 4am and sat near $17.55 until about 7:45am. At 8:00am it jumped, and it touched $20.19 at 8:09am, up 15.2%. It faded to $19.45 by 9:00am and opened the regular session at $18.97. It traded between $18.60 and $19.52 in the first 15 minutes and stood at $19.34 at 9:45am, up 10.4%, on 2.7 million shares.
What lifted it:
- A $5.66 billion deal for its closest rival. Salesforce and Braze said Salesforce will pay $47.50 in cash per Braze Class A share. The agreement was signed Oct 19 and announced Oct 20, according to Braze's 8-K. Braze serves about 2,770 customers, including Canva, Instacart and Venmo.
- A higher benchmark for the group. Investing.com wrote that the deal sets a high transaction multiple for pure-play customer engagement software and could lead analysts to re-rate Klaviyo. That is the outlet's reasoning, not a quote from an analyst.
- Less overlap than it looks. Investing.com also said Braze has shifted toward large legacy accounts, which could leave more of the mid-market online retail business to Klaviyo. Klaviyo reported more than 205,000 customers at June 30.
- Takeover talk. Investing.com said Klaviyo is now the main standalone public name in retention marketing and noted speculation that a cloud giant could bid. No offer or report of talks exists. It is speculation.
What held it back:
- The gain faded. The shares gave up $0.85 from the premarket high to the 9:45am price, which suggests buyers did not chase the news.
- Salesforce got stronger. After the deal Salesforce owns a larger share of the market Klaviyo sells into, although the deal is not expected to close until Salesforce's fiscal year 2028, and it needs Braze shareholder and regulatory approval.
- A downgrade four days earlier. Goldman Sachs analyst Callie Valenti cut Klaviyo to Neutral from Buy on Oct 16 with a $20 price target, citing less visibility on when AI agents will add to growth. The stock is now close to that target.
At 9:45am, from the Oct 19 close:
| Stock or fund | Oct 19 close | Oct 20, 9:45am | Change |
|---|---|---|---|
| Braze (BRZE) | $30.04 | $45.37 | +51.0% |
| Klaviyo (KVYO) | $17.52 | $19.34 | +10.4% |
| HubSpot (HUBS) | $234.63 | $243.19 | +3.6% |
| Sprout Social (SPT) | $11.66 | $12.05 | +3.3% |
| Shopify (SHOP) | $171.06 | $172.78 | +1.0% |
| Zeta Global (ZETA) | $32.50 | $32.71 | +0.6% |
| Salesforce (CRM) | $242.45 | $241.37 | -0.4% |
| iShares software ETF (IGV) | $105.99 | $105.17 | -0.8% |
| Invesco Nasdaq-100 ETF (QQQ) | $718.36 | $710.49 | -1.1% |
| Twilio (TWLO) | $257.29 | $250.80 | -2.5% |
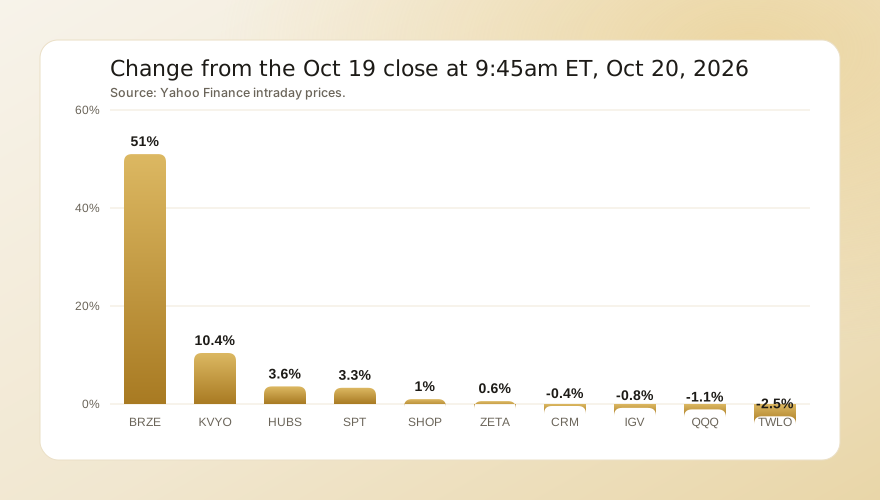
Klaviyo moved about three times as much as HubSpot, the next best gainer, and it rose while the software ETF and the Nasdaq fell. That gap says the market treated Braze's sale as news about Klaviyo's value, not as a sector rally. Braze itself trades at $45.37, 4.7% below the $47.50 offer, which is the market's price for the time and risk before the deal closes. For how that spread is read, see how to calculate a merger arbitrage spread.
After the jump, RSI(14) stood at 64, the shares sat 10.7% above their 50-day average and 5.2% above their 200-day average, volume by 9:45am was 2.7 million shares against a 20-day average of 5.5 million, and the stock was 42% below its 52-week high of $33.35.
What the Braze deal terms say
The terms matter for Klaviyo because they show how a buyer priced this business. The $47.50 price is 58% above the $30.04 close, a large premium; what a takeover premium is explains how to read one. Braze will owe Salesforce a $191.39 million termination fee if its shareholders vote the deal down or its board takes a better offer, and Salesforce will owe Braze $300 million if regulators block it or the deal misses the outside date, according to the 8-K. The outside date is Oct 19, 2027, and it can be extended by up to two 90-day periods. The agreement has no go-shop period, so Braze cannot shop for a higher price. Our guide to reading a merger agreement explains each of these terms.
Salesforce did not disclose Braze's revenue or annual recurring revenue in the release, so we cannot state the multiple it paid. It said the deal does not change its fiscal 2027 guidance.
The numbers behind Klaviyo
Klaviyo reported second-quarter revenue of $370.6 million on Aug 5, up 26% from a year earlier. Non-GAAP operating income was $50.9 million, a 14% margin, and free cash flow was $82.9 million. Customers generating more than $50,000 of annual recurring revenue rose 36% to 4,477, and net revenue retention was 109%. Management raised 2026 revenue guidance to $1.526 billion to $1.534 billion, growth of 24%.
The guide for the third quarter is slower: revenue of $377 million to $381 million, growth of 21.5% to 22.5%, and non-GAAP operating income of $40 million to $43 million, a margin of 10.5% to 11%, down from 14% in the second quarter. Chief financial officer Amanda Whalen said the company closed the quarter at a nearly $1.5 billion annualized run rate and was continuing to invest in growth.
The forward P/E is 18, the price-to-sales ratio is 4.0 and short sellers hold 18.2% of the float. The average analyst target is $26.86, from 22 analysts, Investing.com reported. Stifel kept a Buy rating and a $22 target on Oct 14 and expects another beat.
The bull case
- A buyer paid a premium for the nearest rival. A 58% premium for Braze gives Klaviyo holders a reference point, and the shares have already moved to price some of it in.
- Growth and cash are intact. Revenue grew 26% in the second quarter, the company raised guidance, and it produced $82.9 million of free cash flow in one quarter.
- The stock was depressed before the news. Even after today's jump it trades 42% below its high of $33.35 and below the $26.86 average target. A high short float of 18.2% can add to a rally if results are good.
The risks
- Slower growth is already guided. Third-quarter growth of 21.5% to 22.5% is down from 26%, and the operating margin guide drops to 10.5% to 11%. A miss on a number that is already lower would be hard on the stock.
- Goldman's concern is unresolved. The firm said it sees less visibility on when new products, including AI agents, will contribute, and that small businesses may prefer general tools before adding more applications.
- The move is a read-through. Nothing in Klaviyo's own results changed on Oct 20. A sympathy gain can fade, and the stock gave back $0.85 from its premarket high within two hours.
- Salesforce is a bigger competitor. Once the deal closes, Braze's product will sit inside a company with far more sales reach.
What comes next
Klaviyo reports third-quarter results on Nov 4, 2026. We will watch revenue against the $377 million low end of guidance, the fourth-quarter outlook against the 24% full-year growth guide, and any change in the $212 million to $218 million operating income range. Braze shareholders vote on the deal later, and a filing of the proxy statement is the next dated step; our guide to tracking a merger through approval covers that process. For how to prepare for a report, see what an earnings catalyst is. The short interest figure matters too, and what short interest and days to cover mean explains how it can amplify a move. For another software name that moved on sector news, see why Wix fell in a software selloff. Dombey's published research covers other dated catalysts; see the research archive.