

Nov 4, 2026: a beat and a plan held after a year of doubt
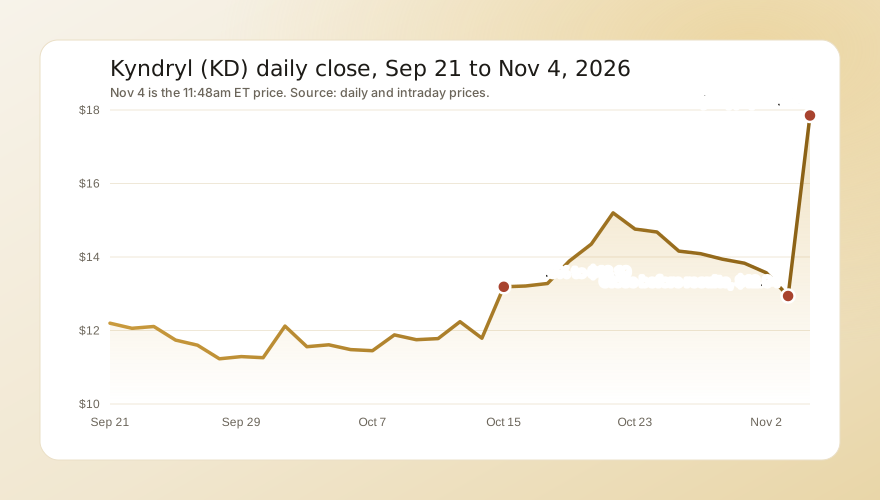
Kyndryl closed Nov 3 at $12.94, its eighth straight lower close, down 14.9% from $15.20 on Oct 22. It reported at 7:00am ET and held its call at 8:30am. Premarket trading ranged from $13.27 to $15.00. The stock opened at $14.91, made its low of $14.62 at 9:30am and rose most of the morning to $17.93 at 11:00am. At 11:48am it was $17.85, up 37.9%, on about 7.3 million shares.
What moved the stock:
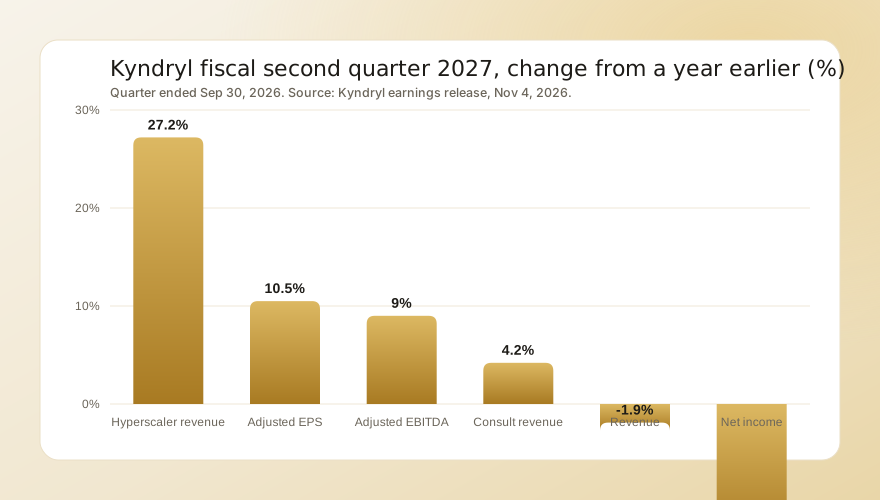
- A beat on profit. Adjusted pretax income rose to $150 million from $123 million and adjusted EBITDA to $699 million from $641 million, even as revenue fell 0.8% in constant currency.
- The outlook held. Kyndryl reaffirmed adjusted pretax income of $600 million to $700 million, free cash flow of $400 million to $500 million and revenue flat to down 2% in constant currency. Chief executive Martin Schroeter said strong signings "reinforce our confidence in our fiscal 2027 outlook."
- Signings stayed strong. Kyndryl signed $4.1 billion of contracts in the quarter, including 11 deals worth more than $50 million each, and $15.5 billion over twelve months.
- The peers rose less. DXC Technology was up 7.7%, Accenture 4.2% and IBM 2.6% at 11:48am, in a broad market rally.
At 11:46am RSI(14) stood at 75, the shares sat 38.2% above their 50-day average and 33.6% above their 200-day average, volume was already 1.8 times its 20-day average, and the stock was still 38.1% below its 52-week high of $28.83. The rest of the session's movers are in today's biggest stock moves.
The numbers
| Measure | Q2 fiscal 2027 | Year earlier |
|---|---|---|
| Revenue | $3.7 billion | down 1.9% |
| Adjusted EBITDA | $699 million | $641 million |
| Adjusted pretax income | $150 million | $123 million |
| Adjusted EPS | $0.42 | $0.38 |
| Net income | $59 million | $68 million |
| Free cash flow | -$34 million | $22 million |
GAAP net income fell to $59 million, or $0.27 a share, because workforce charges doubled to $38 million from $19 million. Kyndryl expects about $200 million of such charges in fiscal 2027, and $190 million came in the first half, so the second half should carry little of that cost while the savings begin. Operating cash flow was $172 million, up from $147 million. Our page on free cash flow yield shows how to weigh a cash target like this against the price.
The bull case
The bull case is cash. Kyndryl is valued at about $3.9 billion and expects $400 million to $500 million of free cash flow this fiscal year, with most of its job-cut charges already behind it. The savings it expects, $400 million to $500 million a year from fiscal 2028, are as large as this year's cash flow target. Its growth lines are working: Kyndryl Consult revenue grew 8.1% over twelve months, Consult signings grew 19.1%, and hyperscaler revenue reached $2.1 billion over twelve months, up 38.5%. A company priced for decline that holds its plan often rerates, which our guide to guidance changes explains.
The risks
The cash flow target needs a big second half. Free cash flow was negative $34 million in the quarter, so Kyndryl has to produce most of the $400 million to $500 million between October and March. Interest costs will rise, since the new notes pay about 7.8% to 7.9% against the 2.05% notes they replaced. Our explainer on debt maturity walls covers what higher refinancing costs do to equity value.
Revenue is still shrinking, and the guide allows for a 2% decline. A 38% jump in a day also pulls forward gains, and the average analyst target of about $14.67 is below the price, so analysts will have to raise numbers for the move to hold. Our guide to analyst upgrades and downgrades covers how targets tend to follow a move like this.
What comes next
The fiscal third-quarter report, for the quarter ending Dec 31, is the next test; last year's came on Feb 9. Before then, watch for analyst target changes after the call and whether the stock holds the $14.91 opening price. Free cash flow for the year to March 31, 2027, is the number that decides whether today's move was the start of a rerating or a one-day reprieve.