

Nov 4, 2026: profit runs ahead of the plan
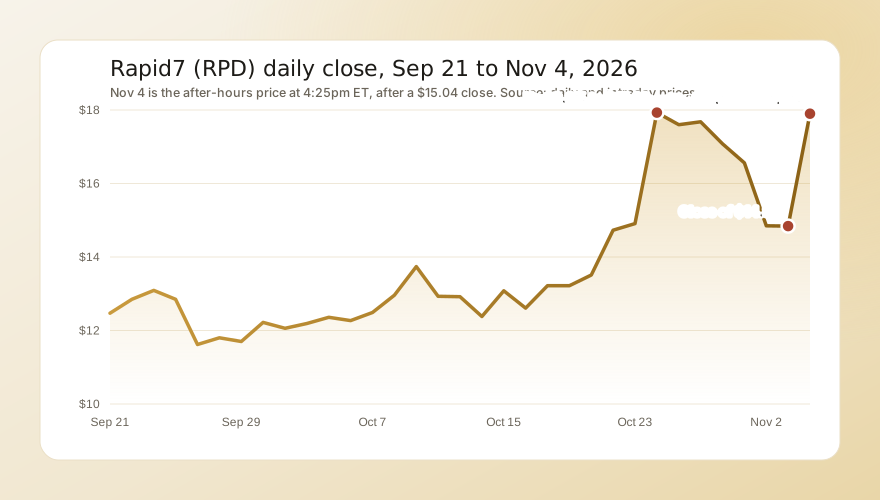
Rapid7 closed Nov 3 at $14.84. Premarket trading was thin, between $14.80 and $15.15. The stock opened at $14.65, made its low of $14.58 at 9:33am and its high of $15.83 around 10:17am, then closed at $15.04, up 1.3%, on about 1.8 million shares. That matched the rest of the group: Tenable rose 0.7%, Qualys 0.2%, SentinelOne 1.6% and the First Trust cybersecurity fund CIBR 0.1%, while CrowdStrike fell 1.5%. At the close, RSI(14) stood at 54, the shares sat 15.1% above their 50-day average and 58.5% above their 200-day average, volume was 0.9 times its 20-day average, and the stock was 19.0% below its 52-week high of $18.56.
The release came out at 4:05pm, ahead of a 4:30pm call. Within minutes the stock traded above $17, and at 4:25pm it was $17.90, with an after-hours range so far of $15.04 to $18.14. More of today's biggest stock moves are on our movers page.
What moved the stock:
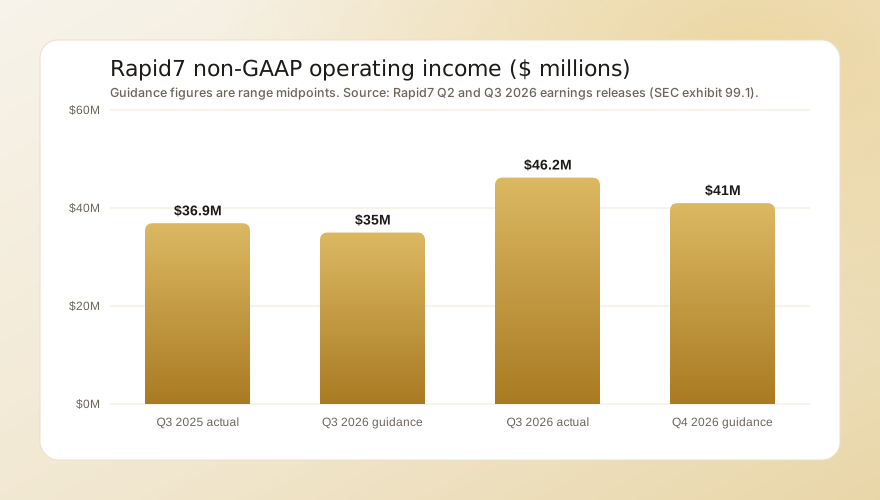
- Profit beat the guide by a wide margin. Non-GAAP operating income of $46.2 million compares with $36.9 million a year earlier and a guide of $34 million to $36 million. The non-GAAP operating margin rose to about 21.8% from about 16.9%, as the restructuring that began in the second quarter, which affected about 12% of staff, came through in costs.
- Earnings and the full-year guide went up. Non-GAAP earnings were $0.60 a share against $0.57 a year earlier and about $0.46 expected. The full-year guide now calls for non-GAAP operating income of $140 million to $142 million, up from $129 million to $133 million, and earnings of $1.94 to $1.96 a share, against a consensus of about $1.80 before the report.
- ARR held up better than promised. ARR fell 2.2% to $819.7 million, down from $824.0 million in the second quarter, but ahead of the roughly $812 million the company had guided in August.
- The tone stayed careful. Mohamed said the company is "operating with greater discipline," but added, "We are not declaring victory." He called this "a multi-quarter journey."
The numbers
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $212.4 million | $218.0 million | -2.5% |
| ARR | $819.7 million | about $838 million | -2.2% |
| Non-GAAP operating income | $46.2 million | $36.9 million | +25% |
| Non-GAAP EPS | $0.60 | $0.57 | +5% |
| Free cash flow | $26.5 million | $30.1 million | -12% |
Product subscription revenue fell 1.9% to $206.1 million. GAAP net income of $3.5 million, or $0.05 a share, included $10.0 million of restructuring charges and a $5.5 million write-down of a strategic investment. Operating cash flow was $30.1 million. Rapid7 serves about 11,800 customers. The fourth-quarter guide of $0.53 to $0.55 a share sits around the $0.54 that the old full-year consensus implied, and fourth-quarter revenue of $208 million to $210 million is close to the roughly $209 million implied, so the raise to the year comes from the third quarter. Our guide to how to read an earnings release covers how to separate a beat from a change in the outlook, and our page on guidance changes explains why the raise matters more than the quarter.
The bull case
This is the third report in a row where Rapid7's earnings have topped estimates. First-quarter earnings were $0.36 a share against about $0.30 expected. In August, second-quarter earnings of $0.44 a share beat estimates of $0.35, StockStory reported, and the stock closed up 15.2% the next day at $13.38. The new team has narrowed the business to detection and response and exposure management, cut costs, and kept ARR above its own guide. Earnings of $1.95 a share at the midpoint of the new guide put the stock at about 9 times this year's earnings even after the jump. Before the report the forward P/E was 8.3, and about 11.8% of the float was sold short, so part of the move can come from short sellers covering; our explainer on short interest and squeezes covers how that works.
Pay is tied to the stock. Mohamed's performance award covers 2,125,000 shares that vest at price hurdles from $15.00 to $30.00 or higher, according to the June 1 filing. JANA Partners, the activist investor, also has a board seat: in March, Rapid7 agreed to nominate JANA's Kevin Galligan, under an agreement that runs until January 8, 2027 at the latest.
The risks
The top line is still falling. ARR fell 2.0% from a year earlier in the second quarter and 2.2% in the third, and the fourth-quarter guide calls for another drop to about $812 million, down 3%. Profit gains from cost cuts can run out if sales do not turn. The stock also trades above every analyst target: the consensus target is $11.65 and the highest is $15, and JPMorgan cut the stock to underweight on Sept 15.
The balance sheet needs work. The $600 million of 0.25% convertible notes due March 15, 2027 convert at $103.38 a share, so holders will want cash. Paying them from the $731.6 million on hand would leave about $130 million before new cash flow, with $300 million more due in 2029. Our explainer on the debt maturity wall covers how a refinancing like this can move a stock. The sector also swings on AI news: Rapid7 fell 6.7% on April 9, the day it set its 52-week low, after Anthropic's Claude Mythos model raised fears for security software, and rose 5% on Oct 21 as those fears eased, StockStory reported. On Oct 26 it jumped 20.3% to $17.93 without a company announcement, then gave most of that back by Nov 3.
What comes next
The fourth-quarter report and the first 2027 outlook are due around February 10, 2027. Before then, watch for analyst target changes after the call, how Rapid7 plans to handle the March 2027 notes, and any news when the JANA agreement ends in early January. Our page on post-earnings announcement drift covers why stocks that gap up on a clear change in profit often keep moving the same way. A close back below the $15.04 pre-report level would undercut the Bullish case.