

Nov 2, 2026: an upgrade on the second day after earnings
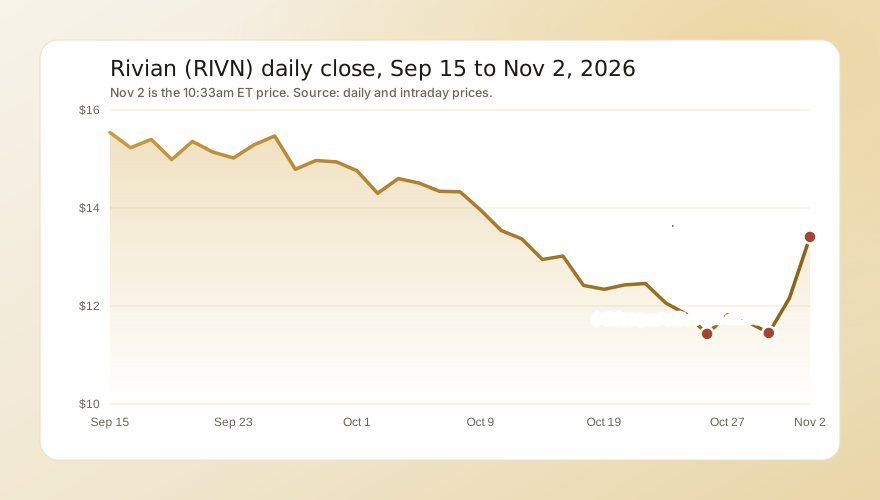
Rivian closed at $12.16 on Oct 30, up 6.2% on the day after results. Premarket trading on Nov 2 ran between $12.25 and $12.75 as the UBS note circulated. The stock opened at $12.93 and traded between $12.65 and $13.52 in the first hour. It was $13.41 at 10:33am on 21.3 million shares, already 0.8 times its 20-day daily average an hour into the session.
Other auto stocks rose too, but by much less:
| Stock or fund | Oct 30 close | Nov 2, 10:32am | Change |
|---|---|---|---|
| Rivian (RIVN) | $12.16 | $13.41 | +10.2% |
| Lucid (LCID) | $3.02 | $3.27 | +8.1% |
| Tesla (TSLA) | $399.81 | $410.04 | +2.6% |
| General Motors (GM) | $87.40 | $89.20 | +2.1% |
| Ford (F) | $12.25 | $12.46 | +1.7% |
| Invesco QQQ (QQQ) | $690.49 | $697.99 | +1.1% |
Lucid also jumped, so some of the move is a bid for beaten-down electric vehicle makers, but Rivian led the group and was the only one with a named catalyst. Our look at why Tesla stock fell shows how differently the market has treated the largest EV maker this quarter, and more of the session's swings are in today's biggest stock moves.
After the move, RSI(14) stood at 53, the shares sat 7% below their 50-day average and 13% below their 200-day average, and the stock was 41% below its 52-week high of $22.69 and 18% above its 52-week low of $11.38. This is context, not a signal.
What UBS is betting on
Spak's case, as 24/7 Wall St. and Schaeffer's Research reported it, has four parts: solid early R2 demand, a turn in automotive gross margin as R2 volume rises, software and services revenue that helps fund growth, and no need for new capital before 2029. UBS also sees Autonomy+, Rivian's driver-assistance subscription, as a possible U.S. rival to Tesla's Full Self-Driving. The margin claim matches management's own words: interim CFO Derek Mulvey said on the Oct 29 call, "We expect that R2 will help us achieve a positive automotive gross margin exit rate for the year," 24/7 Wall St. reported. Our explainer on why analyst upgrades move stocks covers why an upgrade after the numbers are out can still move a stock this much.
What the third quarter showed
| Line | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
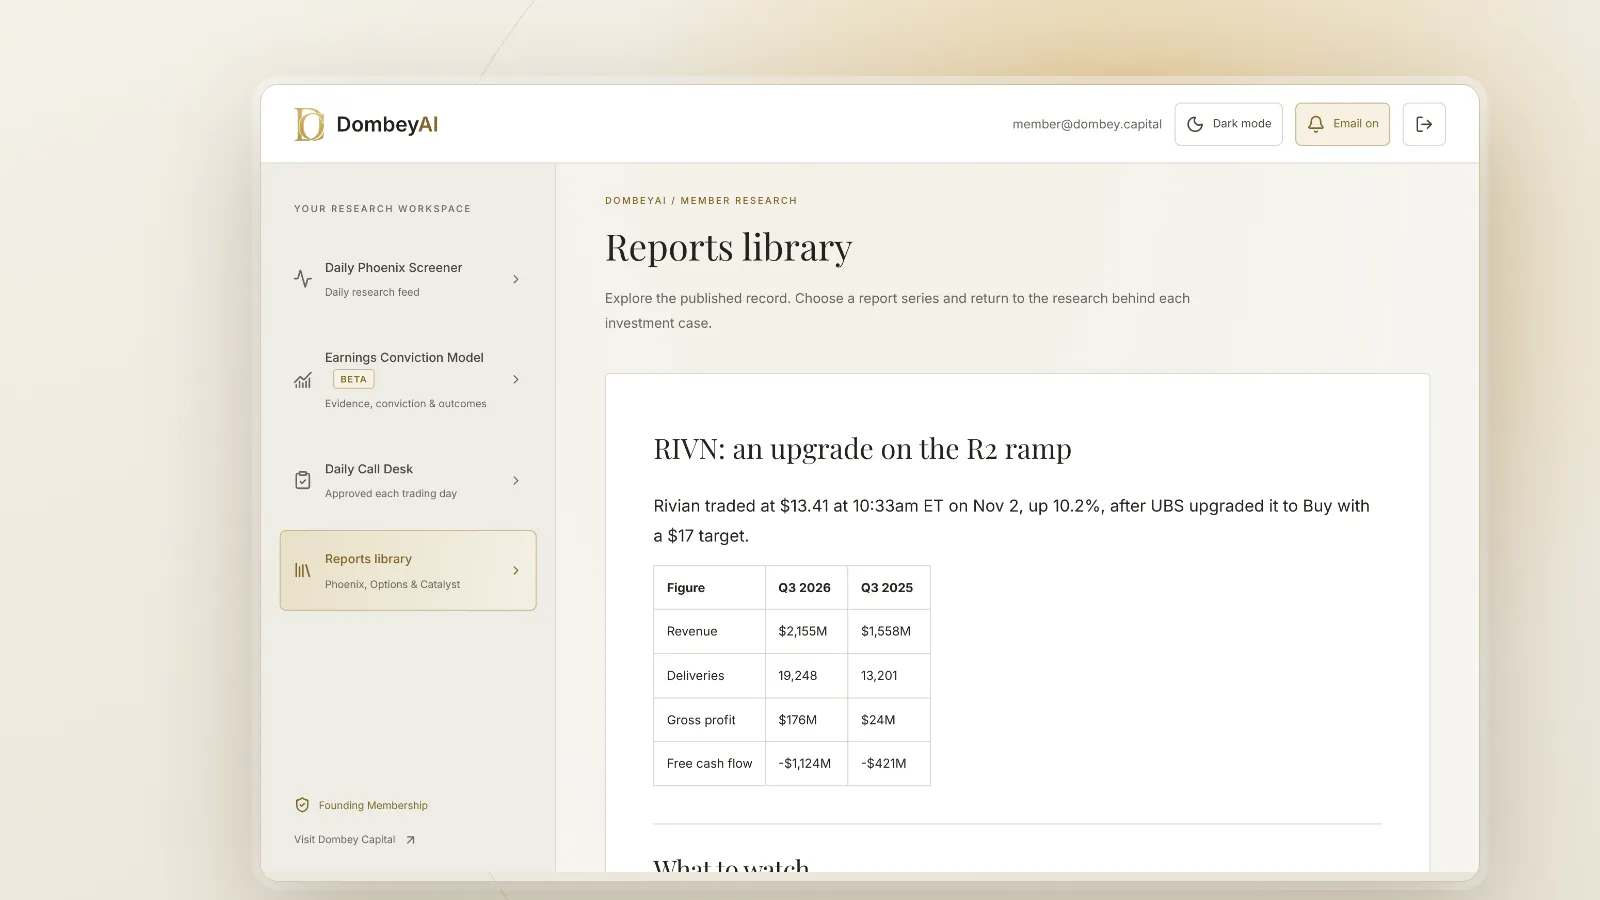
| Revenue | $1,558M | $2,155M | +38% |
| Deliveries | 13,201 | 19,248 | +46% |
| Production | 10,720 | 19,751 | +84% |
| Gross profit | $24M | $176M | +$152M |
| Free cash flow | -$421M | -$1,124M | worse by $703M |
Automotive revenue was $1.550 billion and software and services revenue was $605 million, up 45%, of which $354 million came from the Volkswagen Group joint venture. The adjusted loss was $0.48 a share against an expected $0.64. Rivian raised its delivery guide to 67,000 to 70,000 from 65,000 to 70,000, improved adjusted EBITDA guidance by $100 million at the midpoint to negative $1.85 billion to negative $1.75 billion, and cut capital spending guidance by $300 million at the midpoint to $1.40 billion to $1.50 billion on timing.
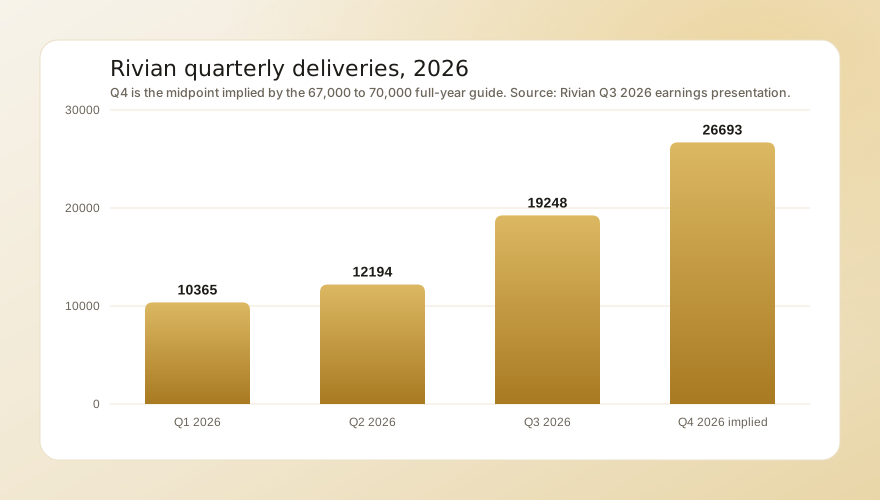
The delivery guide carries the most information. Rivian delivered 10,365 vehicles in the first quarter, 12,194 in the second and 19,248 in the third, or 41,807 in nine months. Reaching 67,000 to 70,000 means 25,193 to 28,193 in the fourth quarter.
The bull case
- Volume is ramping fast. Production rose 84% from a year earlier, and the R2 outsold both the R1 and the commercial van in the third quarter.
- The guide rose on every line. Deliveries, adjusted EBITDA and capital spending all moved the right way, and the fourth-quarter implied deliveries would be a record by a wide margin.
- The balance sheet buys time. Pro forma liquidity of $7.095 billion against third-quarter free cash flow of negative $1.124 billion supports UBS's view that no raise is needed before 2029.
- A second revenue stream. Software and services brought in $605 million in the quarter with $256 million of gross profit, according to the earnings presentation, which helps fund the vehicle ramp.
- Positioning. About 17.4% of the float is sold short, which can add fuel when news turns positive; see what short interest and days to cover tell you.
The risks
- The cash burn got worse. Free cash flow went from negative $421 million a year earlier to negative $1.124 billion, as Rivian bought inventory for the R2 launch and deferred revenue fell.
- The margin is not there yet. Automotive gross profit was a loss of $80 million, and that figure was helped by $81 million of regulatory credit revenue and a tariff refund receivable, neither of which is a steady source.
- Lower prices per vehicle. Rivian said a higher mix of R2 and commercial vans cut the average selling price.
- No new data today. The upgrade restates a view on numbers the market saw on Oct 29. A move this size on an opinion can fade; our note on base rates covers why.
What comes next
- Autonomy and AI Day, Dec 9, 2026. Rivian plans to say more on its autonomy roadmap, including the Point to Point feature, which it expects to reach all Autonomy+ subscribers in 2027.
- Fourth-quarter production and deliveries, likely in early January. The test is 25,193 deliveries, the low end implied by the guide.
- Fourth-quarter results, not yet dated, with the automotive gross margin exit rate management promised.
Dombey's published work on event-driven moves is in the research archive, and our guide on what an earnings catalyst is explains how to prepare for the delivery report.