

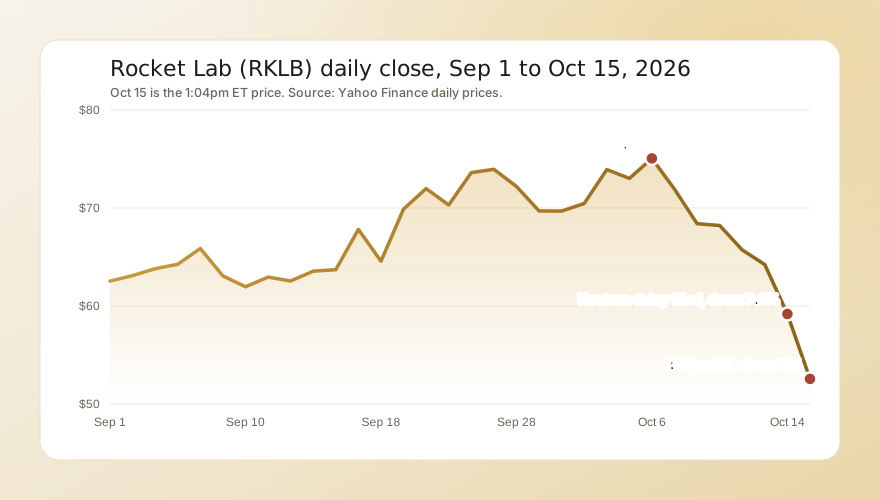
Oct 15, 2026: a gap down, a low near $50, then a partial recovery
Rocket Lab filed the Neutron update after the close on Oct 14, following a regular session in which the stock had already fallen 7.9% to $59.18. It fell as low as $53.44 after hours. In Thursday's premarket it traded between about $53 and $54, roughly 9% to 10% below Wednesday's close.
The regular session opened lower, at $51.48, down 13%. The stock then touched $49.69, a 16% drop from Wednesday's close. It recovered to as high as $55.21 during the session and was at $52.56 at 1:04pm ET, about 6% above the low. Volume had reached 33 million shares by then, already the most in a session since Aug 10.
What pushed it down:
- The delay itself. Rocket Lab said Neutron's inaugural launch is now expected in 2027. Beck said engineers found voids in the carbon-composite forward dome of the first-stage propellant tank, and the fix needs a new dome and process changes.
- A pattern of slips. Neutron was unveiled in 2021 with a 2024 first flight. That moved to mid-2025, then into 2026, and in August Beck said the window for a launch this year was "narrowing." Investors who had given the company the benefit of the doubt on the fourth-quarter date lost it.
- An existing slide. The stock had fallen in six of the seven sessions before the news. Chief financial officer Adam Spice sold about $9.9 million of shares in early October under a pre-arranged trading plan, and broad markets were under pressure from higher bond yields.
What helped the recovery:
- Management set a near-term marker. Beck said fixes have been identified, a new dome will be built and inspected, and the full first stage should be assembled within the first quarter of 2027, after which the company expects to give a launch date. He said the added time also lets Rocket Lab bring forward upgrades planned for later flights.
- Analysts held their ratings. Cantor Fitzgerald kept its Overweight rating and $122 target, calling the delay disappointing but not material over the long term. Raymond James (Outperform, $80) and Berenberg (Buy, $83) also stayed positive.
- Beck framed it as a margin decision. He said the dome flaws do not necessarily mean it would fail in flight, but "possible success isn't our standard."
The Neutron schedule, in dates
| When stated | First launch target | What changed |
|---|---|---|
| 2021 | 2024 | Neutron unveiled |
| Later updates | Mid-2025, then 2026 | Development took longer |
| Feb 2026 | Q4 2026 | Stage 1 tank failed a test in January |
| Aug 2026 | Q4 2026 | Tank production "aligned" with pad delivery in Q4 |
| Oct 14, 2026 | 2027 | Voids found in the tank's forward dome |
The August results release said production of the Stage 1 tank was aligned with delivering Neutron to the launch pad in the fourth quarter. Two months later the date moved. That is why the market punished the news more than the length of the delay alone would suggest. Our explainer on hard and soft catalysts covers why a target date set by the company carries less weight than a date set by a regulator or a contract.
The numbers behind the stock
The delay matters because Neutron is the rocket that would let Rocket Lab compete for larger missions, and it is still in development. Research and development spending has risen every quarter.
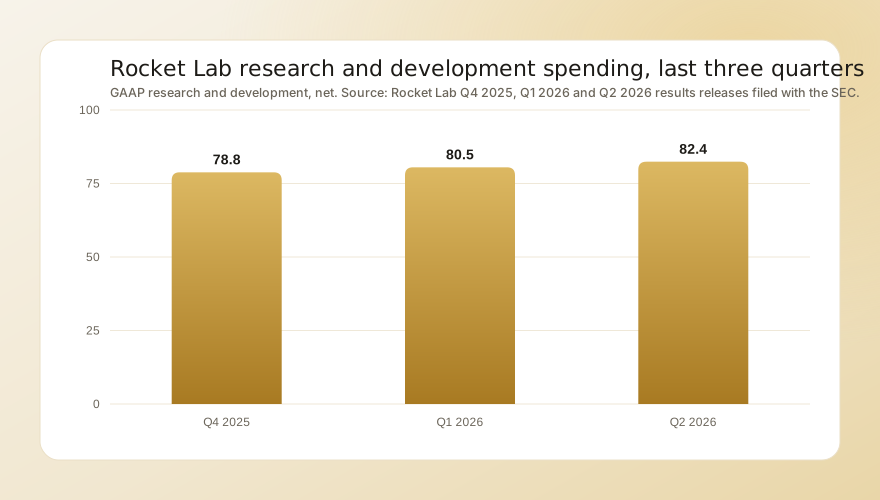
Total research and development runs at about $80 million a quarter, and a later first flight means more quarters of that spending before Neutron earns launch revenue. The second-quarter net loss was $49.3 million, and adjusted EBITDA was a loss of $8.8 million.
The rest of the business is doing well:
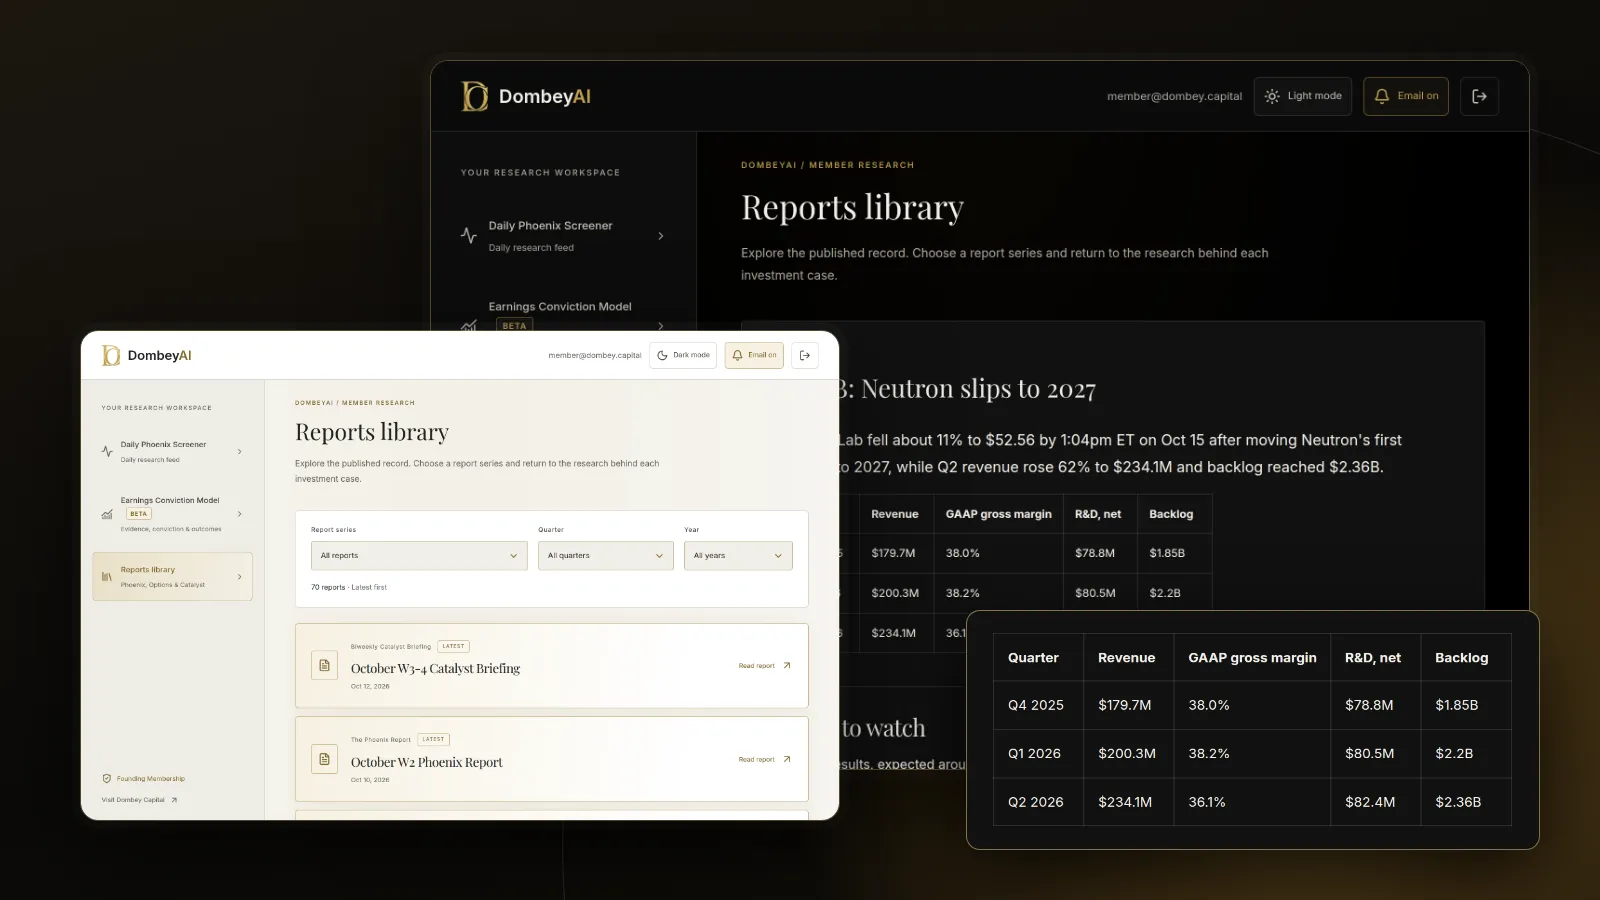
| Quarter | Revenue | GAAP gross margin | Backlog |
|---|---|---|---|
| Q4 2025 | $179.7M | 38.0% | $1.85B |
| Q1 2026 | $200.3M | 38.2% | $2.2B |
| Q2 2026 | $234.1M | 36.1% | $2.36B |
Revenue in the second quarter rose 62% from a year earlier, and the company guided to $250 million to $265 million for the third quarter. Gross margin guidance for the third quarter is lower, 29% to 31% on a GAAP basis. For how to read a target like that, see why guidance changes move stocks.
The case for the stock
- The money is there. Cash and marketable securities rose to $2.39 billion at June 30 from $1.10 billion at the end of 2025, against $14.8 million of convertible notes and borrowings. A delay of a few quarters is affordable.
- Demand did not change. The delay moves Neutron revenue later. It does not cancel contracts, and Beck pointed to strong demand and upcoming contract announcements. Electron signed a 20-mission deal with Synspective last month.
- The sell-off already prices a lot. At $52.56 the stock is about 65% below its 52-week high of $151 set in May, and about $15 above its 52-week low of $37.57.
The risks
- Another slip. A fifth delay would make the 2027 date hard to believe and would mean more quarters of heavy development spending before Neutron earns revenue.
- The Iridium deal. Rocket Lab agreed in June to buy Iridium for about $8.0 billion of enterprise value, paying $27.00 in cash plus Rocket Lab stock for each Iridium share, with a collar of $67.50 to $112.50 on the Rocket Lab share price. The stock is now well below the bottom of that collar. The cash part will come from the balance sheet plus other debt and equity, backed by a $3.6 billion bridge loan commitment. A share sale at these prices would mean more dilution for existing holders.
- Lower margins ahead. Third-quarter gross margin guidance of 29% to 31% is below the 36.1% the company reported in the second quarter.
- Losses continue. Consensus estimates cited by Investing.com show a loss per share through 2027. Some targets have come down: TD Cowen cut its target to $90 from $120 earlier this month.
What comes next
- Third-quarter results, expected around November 10. The company had not confirmed the date as of Oct 15. Watch revenue against the $250 million to $265 million guidance, the backlog, and whether management repeats the first-quarter 2027 target for first-stage assembly. Our guide to preparing for an earnings report explains what moves a stock on the day.
- A new forward dome. Rocket Lab says the replacement dome will be built and inspected before the first quarter of 2027. Any update on that part is the earliest sign of whether the new schedule holds.
- Iridium financing. How the company raises the cash portion, and at what price, will matter more now that the stock is below the collar.
- A launch date. The company expects to name one after the first stage is assembled.