Teladoc (TDOC) Stock: Why It Rose 25% After a Profit Beat
Why Teladoc stock jumped 25% on Oct 29: adjusted EBITDA above guidance, BetterHelp insurance growth, a plan for its $1 billion of 2027 notes and our view.
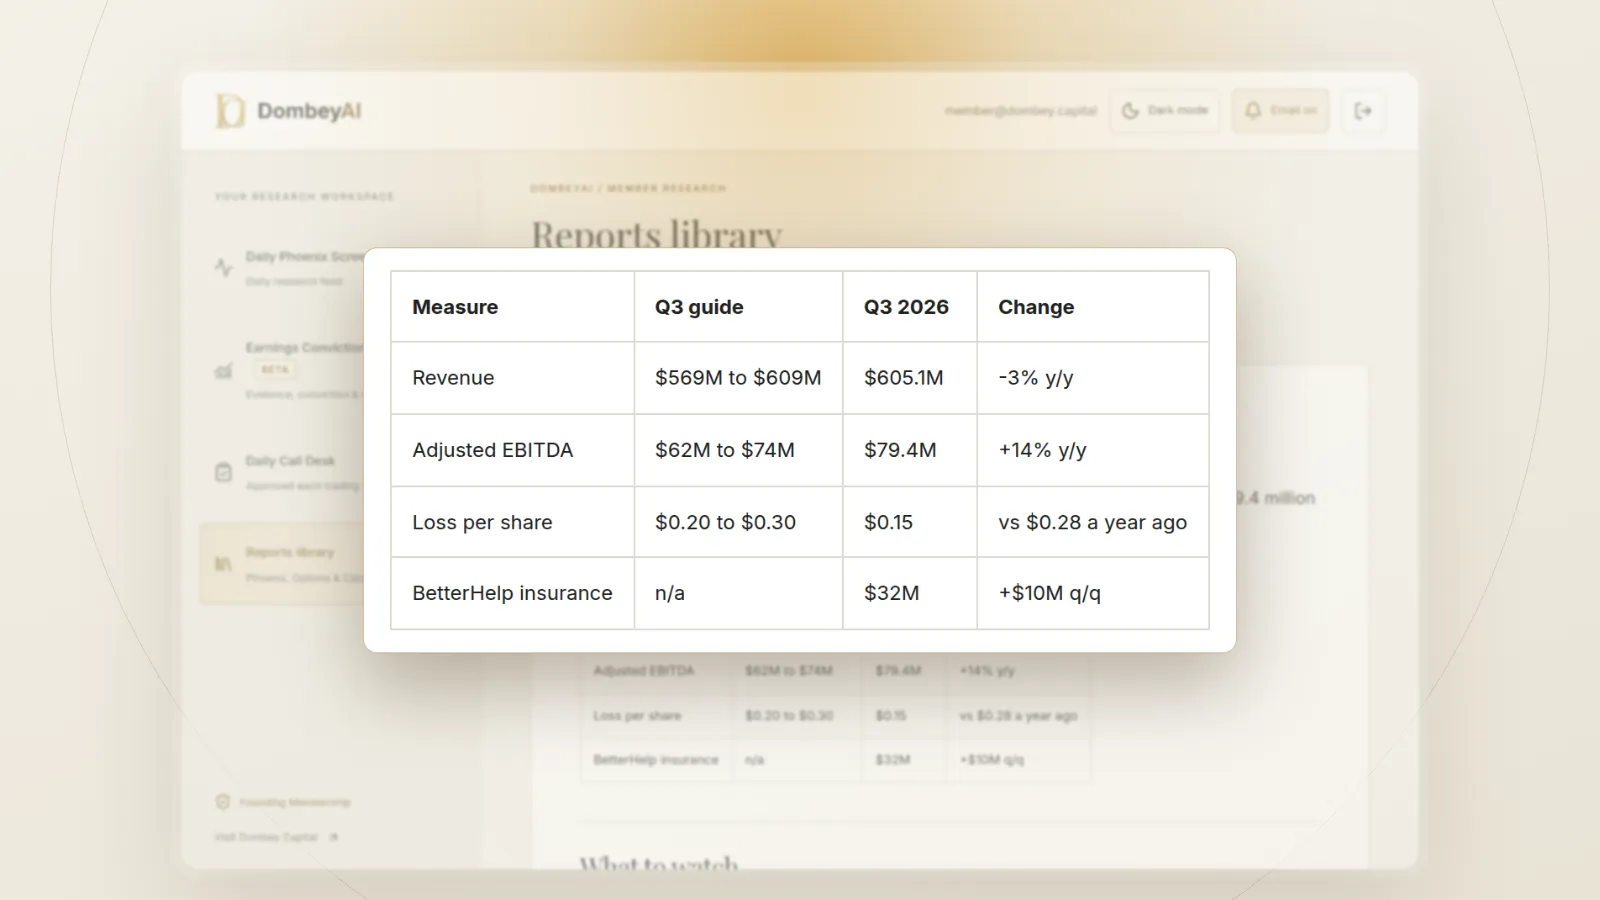
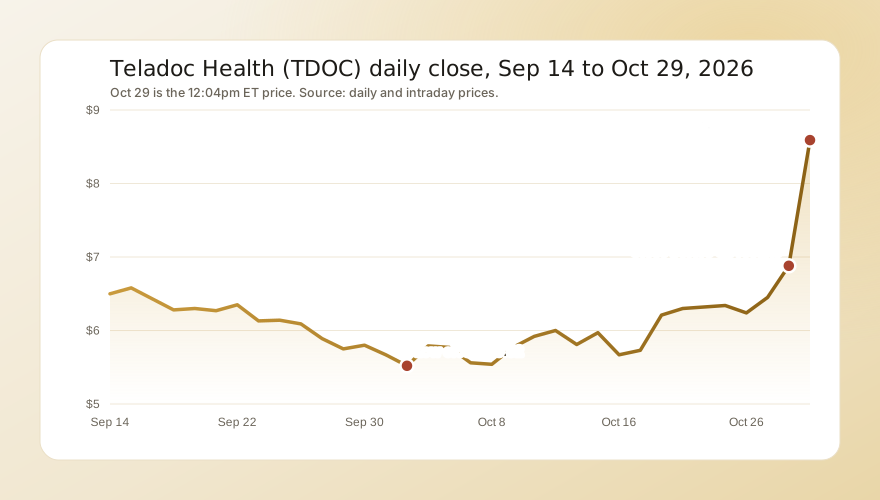
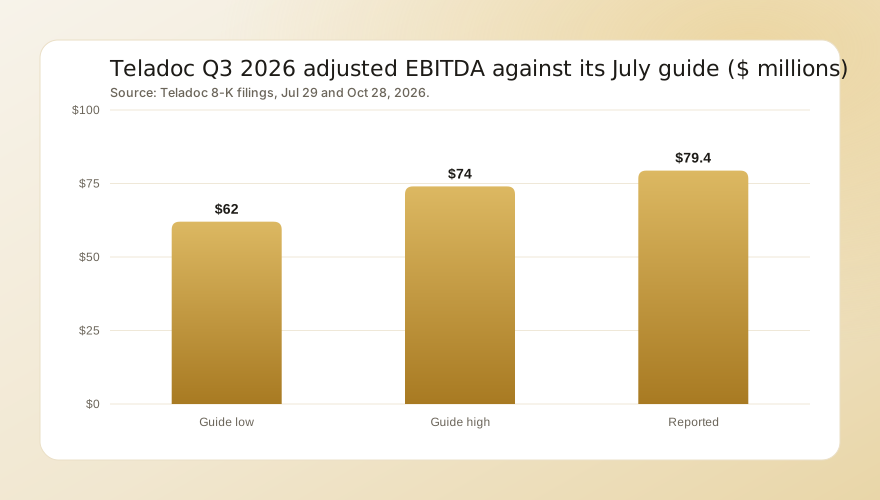
Teladoc Health rose 24.8% to $8.59 at 12:04pm ET on Oct 29, 2026, from a $6.88 close, after a third quarter in which profit came in well above its own guide and management set out how it will handle $1 billion of convertible notes due in June 2027. Adjusted EBITDA rose 14% to $79.4 million, above the $62 million to $74 million Teladoc had guided in July, and the net loss of $0.15 a share beat both its guide of $0.20 to $0.30 and the analyst average of about $0.22. Revenue still fell 3%, to $605.1 million, but BetterHelp's insurance business, the piece meant to replace shrinking cash-pay therapy, brought in $32 million, above management's range. CFO Mike Grasher said Teladoc intends to repurchase a substantial portion of the notes, potentially before year-end, with cash and new debt, and repay the rest in cash at maturity. Volume reached 10.5 million shares by 12:04pm, 2.7 times its 20-day average for a full day.
Our view: Bullish through February 24, 2027, when the fourth-quarter report and 2027 guidance are expected. The case against the stock: revenue is still shrinking, BetterHelp revenue fell 13% and its margin was 2.2%, management expects a "continued challenging environment in 2027" for cash-pay users, the traditional debt used to retire the notes will add interest cost, and after a 25% gain the shares trade near the $8.83 average analyst target with RSI(14) at 82. The case for it carries more weight into February. Teladoc makes cash: free cash flow was $75.9 million in the quarter and the full-year guide is $135 million to $165 million, against a market value of about $1.56 billion. With $850 million of cash, the plan for the 2027 notes turns a maturity that has hung over the stock into a refinancing it can mostly fund itself. Profit beat guidance in both segments, the loss guide narrowed, and 17.8% of the float is sold short, about 7.5 days of average volume. We would move off Bullish if the new debt carries a rate that wipes out most of the free cash flow, if fourth-quarter BetterHelp insurance revenue falls below the $32 million low end of its guide, or if Integrated Care revenue turns down. This is a view on direction over that window, not a recommendation to trade the stock.
Key takeaways
Teladoc rose 24.8% to $8.59 at 12:04pm ET on Oct 29, 2026, from a $6.88 close, after its third-quarter report. It opened at $7.91 and reached $8.99 at 9:45am, its highest price since its 52-week high of $9.89.
Adjusted EBITDA rose 14% to $79.4 million, above the $62 million to $74 million Teladoc had guided, and the net loss of $0.15 a share beat both its guide of $0.20 to $0.30 and the analyst average of about $0.22. Revenue fell 3% to $605.1 million.
BetterHelp insurance revenue was $32 million, above management's range and up $10 million from the second quarter, with an annualized run rate above $140 million on recent weekly sessions.
Teladoc plans to repurchase a substantial portion of its $1 billion of convertible notes due June 2027, potentially before year-end, with cash and new debt, and to repay the rest in cash. It ended September with $850 million in cash.
Our view is Bullish through February 24, 2027, the expected fourth-quarter report: the business makes cash, the debt plan removes the main overhang, and 17.8% of the float is still sold short.
Oct 29, 2026: a 25% gain, with the open as the low
Teladoc reported after the close on Oct 28. The first premarket trades at 4am were at $7.24, up 5.2%, and the stock rose to $7.95 by 7:35am. It opened the regular session at $7.91, which was also the day's low, then reached $8.99 at 9:45am, up 30.7%. At 12:04pm it was $8.59.
What happened:
Profit above the guide. Integrated Care adjusted EBITDA was $75 million, up 13.3%, and its 18.8% margin came in "well above the high end of our guidance range," Grasher said. Consolidated adjusted EBITDA of $79.4 million topped the range by $5.4 million.
Insurance is ramping. BetterHelp insurance revenue was $32 million, up $10 million from the second quarter. CEO Chuck Divita said weekly covered sessions recently reached 27,000, "an annualized insurance revenue run rate of over $140 million." Insurance accounted for 36% of new US BetterHelp users in the quarter, MarketBeat reported from the call.
A plan for the notes. Grasher said the first phase "would potentially involve repurchasing a substantial portion of the outstanding notes," and that Teladoc expects "to repay the remaining balance with cash at maturity in June 2027."
A narrower guide. The 2026 loss range moved to $0.75 to $0.95 a share from $0.75 to $1.00, and the adjusted EBITDA floor rose $6 million.
The Street. Stifel and Needham kept neutral ratings on Oct 29.
Other virtual care names moved about 1%, so this was a Teladoc move. From the Oct 28 close, at 12:04pm:
Stock or fund
Oct 28 close
Oct 29, 12:04pm
Change
Teladoc Health (TDOC)
$6.88
$8.59
+24.8%
Health Care Select SPDR (XLV)
$179.72
$183.52
+2.1%
Hims & Hers (HIMS)
$29.32
$29.74
+1.4%
LifeStance (LFST)
$13.39
$13.57
+1.3%
Doximity (DOCS)
$34.25
$34.00
-0.7%
After the jump, RSI(14) stood at 82, the shares sat 39% above their 50-day average and 33% above their 200-day average, and the stock was 13% below its 52-week high of $9.89.
The numbers: shrinking sales, growing profit
Revenue fell 3% from a year earlier: access fees fell 10% to $466.7 million while other revenue rose 31% to $138.4 million. BetterHelp's paying users fell 12% to 336,000, MarketBeat reported. But profit rose. The net loss narrowed to $26.9 million from $49.5 million, operating cash flow was $106.5 million and capital spending $30.5 million. For the fourth quarter, Teladoc guides revenue of $569 million to $615 million and adjusted EBITDA of $74 million to $100 million. Our explainer on free cash flow yield shows how to set that cash against the share price.
The bull case: cash, and a fix for the debt
Cheap on cash flow. Enterprise value is about $1.74 billion, about six times the midpoint of the 2026 adjusted EBITDA guide, and the shares trade at 0.6 times sales and 1.2 times book.
The maturity is manageable. Net debt was 0.5 times trailing adjusted EBITDA, down from 1.0 a year earlier, MarketBeat reported. Our guide to debt maturity walls and refinancing risk explains why a plan announced early matters.
Short interest. At 17.8% of the float, short sellers would need to cover positions if results keep improving. Our explainer on short interest and days to cover covers how that can extend a move.
The risks
Revenue. Full-year revenue growth for BetterHelp is guided at minus 12.9% to minus 16.1%, and Integrated Care at only 1.1% to 2.1%.
The cost of new debt. The repurchase depends on market conditions, and the terms of the new debt are not yet known.
The price. After the jump, the stock sits near the average analyst target, so further gains need estimates to rise.
What comes next
Watch for the note repurchase, which Grasher said could come before year-end, and for its terms. The fourth-quarter report, expected around February 24, 2027, brings 2027 guidance, including the BetterHelp insurance path toward a $200 million run rate by the end of 2027. Our explainer on why guidance changes move stocks covers what to look for in it. More of the day's swings are in today's biggest stock moves.
Frequently asked questions
Why did Teladoc stock go up today?
Teladoc rose 24.8% to $8.59 at 12:04pm ET on Oct 29 after third-quarter adjusted EBITDA of $79.4 million beat its own $62 million to $74 million guide, the loss per share was smaller than expected, BetterHelp insurance revenue grew faster than planned and management laid out a plan to deal with $1 billion of convertible notes due in June 2027.
What did Teladoc report for the third quarter of 2026?
Revenue fell 3% to $605.1 million, near the top of its $569 million to $609 million guide. The net loss was $26.9 million, or $0.15 a share, against $0.28 a year earlier. Adjusted EBITDA rose 14% to $79.4 million, and free cash flow was $75.9 million. Integrated Care revenue rose 2% to $398.5 million and BetterHelp revenue fell 13% to $206.6 million.
What is BetterHelp insurance revenue?
BetterHelp, Teladoc's online therapy business, is moving from customers who pay out of pocket to sessions covered by insurance. Insurance revenue was $32 million in the third quarter, up $10 million from the second. CEO Chuck Divita said weekly covered sessions recently reached 27,000, an annualized run rate above $140 million, and CFO Mike Grasher set a goal of at least $200 million a year by the end of 2027.
How will Teladoc pay its 2027 convertible notes?
Grasher said Teladoc intends to repurchase a substantial portion of the $1 billion of convertible notes due June 2027, potentially before year-end, using available cash and proceeds from more traditional debt financing, then repay the remaining balance with cash at maturity. Teladoc had $850 million of cash at September 30.
What is Teladoc's 2026 guidance?
Teladoc now expects 2026 revenue of $2.395 billion to $2.441 billion, adjusted EBITDA of $277 million to $303 million, a net loss of $0.75 to $0.95 a share and free cash flow of $135 million to $165 million. In July the ranges were $2.362 billion to $2.447 billion, $271 million to $303 million, a $0.75 to $1.00 loss and $130 million to $170 million.
When does Teladoc report next?
The fourth-quarter report is expected around February 24, 2027, with 2027 guidance. Teladoc has not confirmed the date.
Dombey Capital publishes investment research and educational content. Nothing herein is personalised investment advice, an offer to buy or sell any security, or a recommendation that any security or strategy is suitable for any recipient. We are not a registered investment adviser.
Turnaround and distressed equities carry substantial risk of permanent capital loss. Historical research outcomes are not a representation of any investor's actual results. Past performance does not indicate future results.