

Oct 22, 2026: a record quarter, and a call that sank the stock
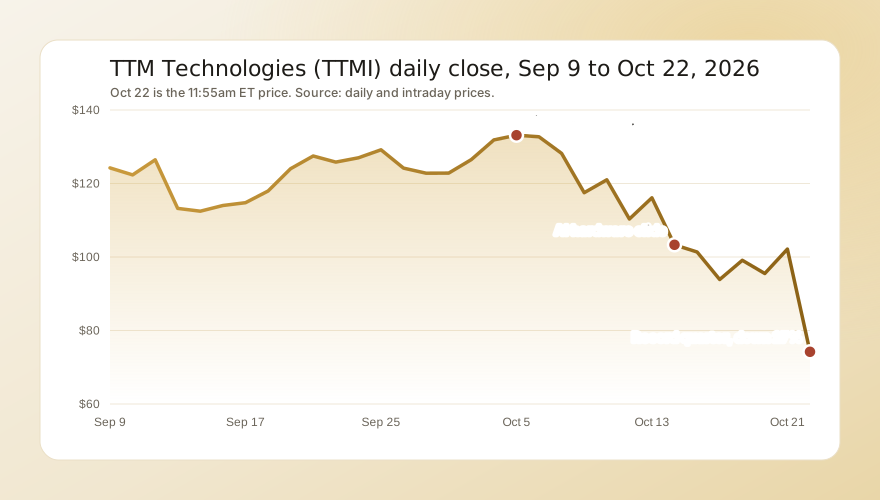
TTM released results at 6:00am ET. The stock traded at $101.00 at about 4:35am, close to the Oct 21 close, and drifted lower as the release circulated. It fell faster once the 8:30am call started: by 9:10am it was $79.00, down 22.7%, and it was $83.68 just before the bell. It opened at $83.75, touched $84.09 in the first minutes and then slid through the morning to a low of $73.42 at about 11:35am, down 28.1%. At 11:55am it was $74.21 on about 9.9 million shares.
What pushed it down:
- Data center sales below plan. Truist analyst Will Stein said data center and networking sales came in about 10% below prior guidance and asked whether supply, materials or yields were the cause. CEO Edwin Roks said none of them were, and that "yield numbers are where they should be." The segment was still 41% of sales and up 115%.
- A late N+M program. N+M, TTM's asymmetrical boards for AI systems, was about 30% of data center activity. Of three major programs, Roks said, "one of them is, let's say, a bit moving to the right," adding that it has "nothing to do with any technical issue." Stein had expected about $200 million of N+M sales in the third quarter and $400 million in the fourth; Roks said the third quarter was "slightly more than 200" and the fourth "slightly below the 400."
- A fourth-quarter range that only meets consensus. Guidance of $1.42 billion to $1.44 billion now includes the Swiss Technology Group and Epiq Solutions deals. StockStory put consensus at $1.44 billion, above the midpoint.
- More spending and more debt. Management added "another $400 million" of N+M capacity running into early 2028, on top of more than $1.3 billion already invested or committed. CFO Dan Boehle said new debt adds about $20 million a quarter of interest expense, and the $650 million Ophir Optics purchase announced Oct 19 will be paid with cash and revolver borrowings.
From the Oct 21 close, at 11:55am:
| Stock or fund | Oct 21 close | Oct 22, 11:55am | Change |
|---|---|---|---|
| TTM Technologies (TTMI) | $102.15 | $74.21 | -27.4% |
| Celestica (CLS) | $304.61 | $273.03 | -10.4% |
| Flex (FLEX) | $86.25 | $77.36 | -10.3% |
| Sanmina (SANM) | $172.07 | $155.43 | -9.7% |
| Amphenol (APH) | $79.20 | $72.50 | -8.5% |
| Jabil (JBL) | $280.99 | $261.03 | -7.1% |
| VanEck semiconductor ETF (SMH) | $556.70 | $528.07 | -5.1% |
| Invesco QQQ (QQQ) | $725.20 | $708.72 | -2.3% |
| SPDR S&P 500 ETF (SPY) | $773.09 | $764.35 | -1.1% |
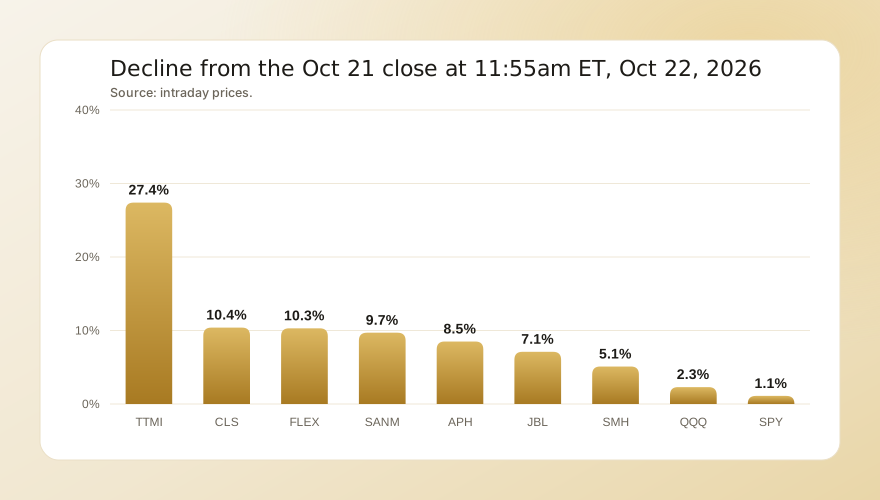
The whole AI hardware supply chain sold off on Thursday, and the Nasdaq 100 fell more than 2%. The five peers averaged a 9.2% drop. That leaves about 18 points that the sector does not explain, which is the part tied to TTM's call. For other AI hardware names under pressure this week, see our pages on Super Micro, CoreWeave and today's biggest stock moves.
After the drop, RSI(14) stood at 28, the shares sat 37% below their 50-day average and 42% below their 200-day average, volume ran 3.3 times its 20-day average of 3.0 million shares, and the stock was 67% below its 52-week high of $223.83.
The numbers
For the quarter ended Sept 28, 2026:
| Measure | Q3 2026 | Q3 2025 |
|---|---|---|
| Net sales | $1.2 billion | $752.7 million |
| GAAP operating income | $162.3 million | $71.9 million |
| GAAP EPS | $0.79 | $0.50 |
| Non-GAAP EPS | $1.46 | $0.67 |
| Adjusted EBITDA | $242.3 million (20.1%) | $120.9 million (16.1%) |
Cash flow from operations was $154.7 million, 12.9% of sales. By end market, data center and networking was 41% of sales and up 115%, aerospace and defense 34% and up 21%, and medical, industrial and instrumentation up 97%. The aerospace and defense backlog reached a record $2.0 billion.
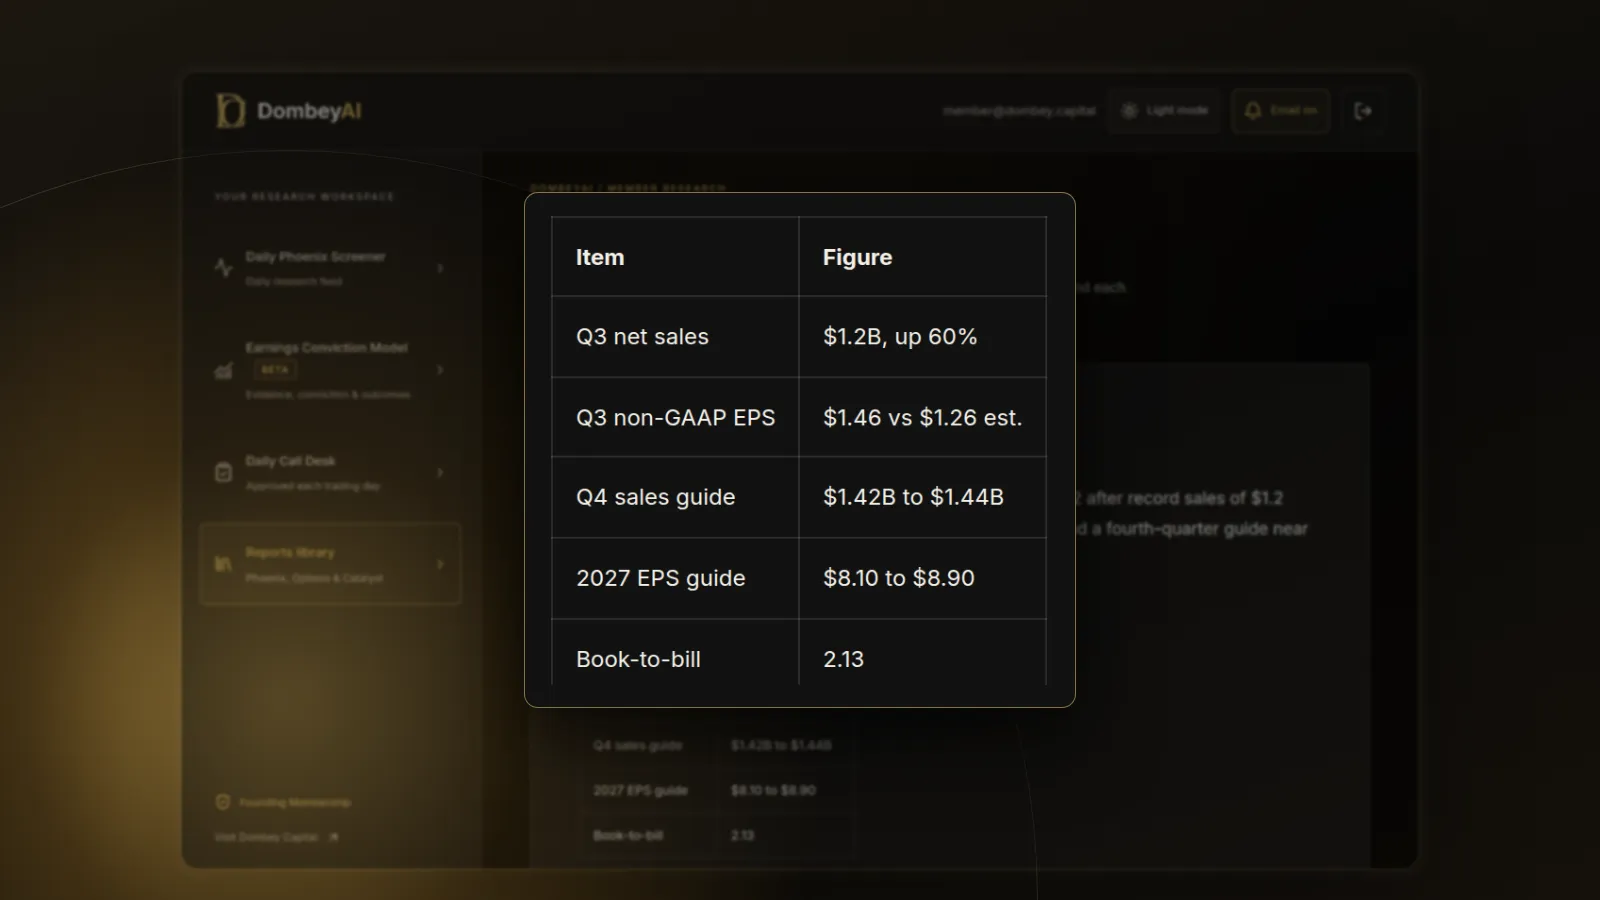
Guidance: fourth-quarter net sales of $1.42 billion to $1.44 billion and non-GAAP EPS of $1.77 to $1.83; full-year 2026 sales of $4.47 billion to $4.49 billion and EPS of $4.97 to $5.03; and a preliminary 2027 range of $6.5 billion to $6.75 billion of sales and $8.10 to $8.90 of EPS. Boehle expects gross and EBITDA margins to rise by more than 200 basis points in 2027 as N+M grows. Our explainer on how guidance changes move stocks covers why the near quarter often outweighs the next year in the first hours after a report.
The bull case
- The beat was broad. Sales beat by about $70 million, EPS by $0.20, and every major end market grew.
- Orders keep coming. The book-to-bill was 2.13, and the 90-day backlog, which customers can cancel, rose 111% to $1.3 billion.
- The price now assumes little. At $74.21 the stock trades at under 9 times the $8.50 midpoint of 2027 EPS guidance. The average analyst target is about $204, set before Thursday. Our guide to forward versus trailing P/E explains why a forward multiple matters most for a company growing this fast.
- The delay is a timing issue. Management said the late program is ramping now and the cause is the customer's schedule, not yields.
The risks
- Credibility on data center timing. A miss against the company's own data center plan in the quarter that was supposed to show the N+M ramp makes the fourth-quarter $400 million N+M figure the number to watch.
- Leverage and spending. Net leverage was 2.8 times on Sept 30, with $400 million more capacity spending, the Ophir purchase and two smaller deals still to close. Our explainer on the debt-to-equity ratio covers how to judge that kind of balance sheet.
- Materials. Roks said lead times for some board materials run 12 to 24 weeks, and the company is counting on customers to absorb price increases.
- A falling sector. The stock was already down 23% from its Oct 5 close of $133.14 before the report, as AI hardware stocks sold off together.
What comes next
- Fourth-quarter results, expected in early February. Watch N+M sales against the "slightly below 400" million figure and whether sales land inside $1.42 billion to $1.44 billion. Our guide on how to analyze an earnings call transcript shows how to track a figure like that from one call to the next.
- The third N+M program. Any update on when it reaches volume.
- The Ophir close, expected in the second quarter of 2027, and whether leverage is back inside the 1.5 to 2.0 times target by then.
- Analyst targets. Truist and Needham both kept Buy ratings in the past six weeks; cuts after Thursday's call would show how much of the 2027 range the Street believes.