

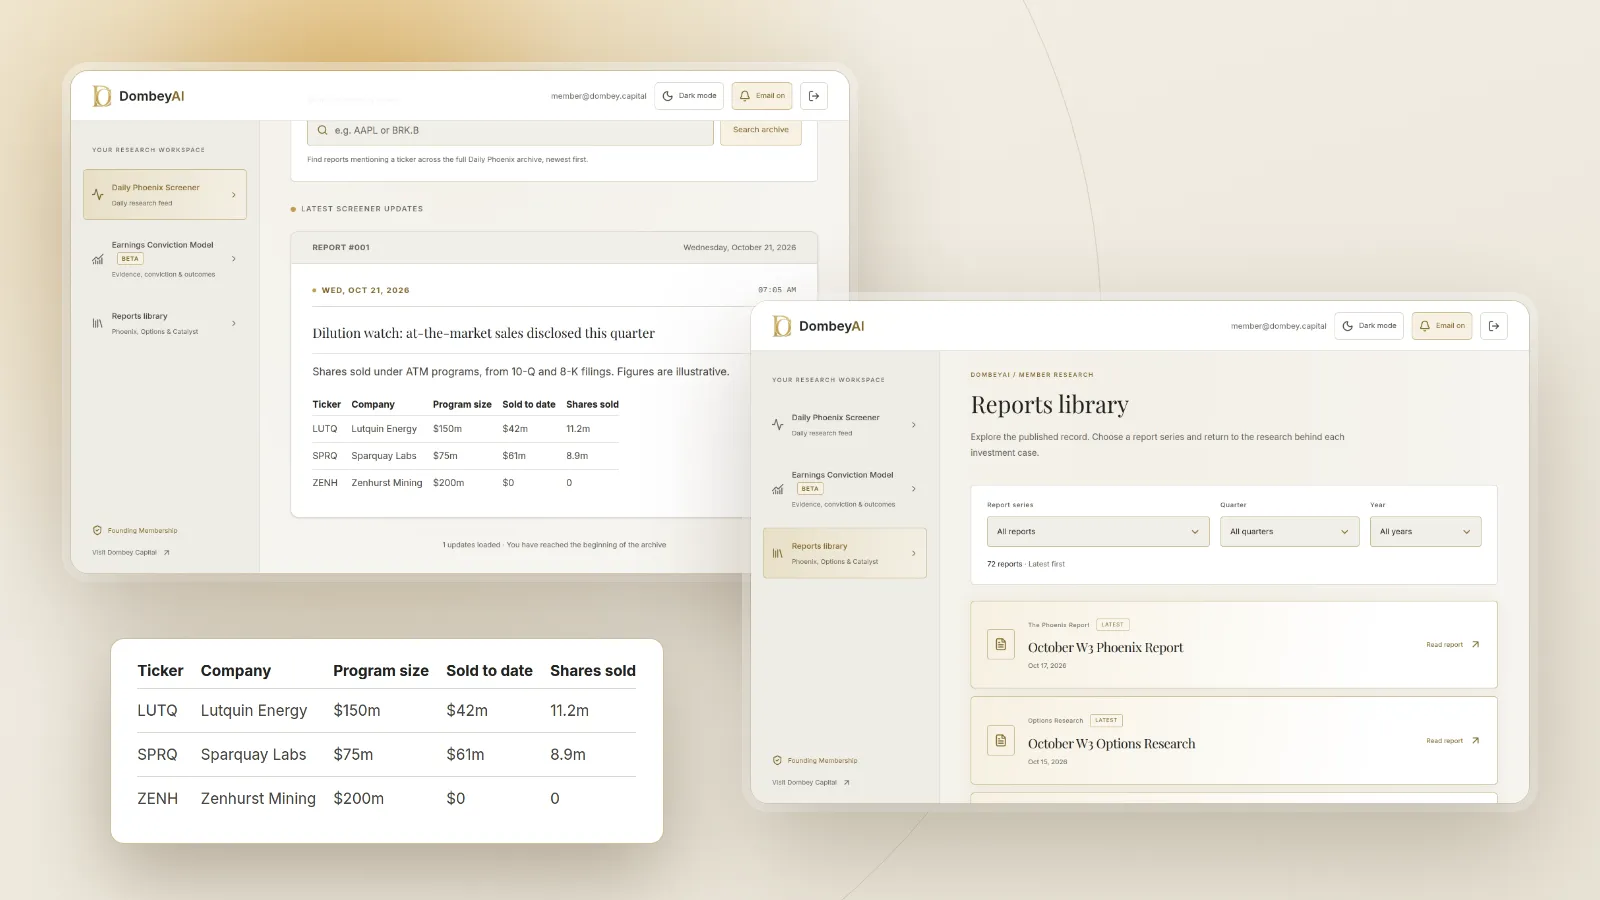
How an ATM offering works
An ATM program has three pieces.
- A shelf registration. The company first files a registration statement, usually on Form S-3, that registers a dollar amount of securities it may sell later. Once the SEC declares it effective, the shares are on the shelf.
- A sales agreement. The company signs an agreement with one or more broker-dealers, often called an equity distribution or sales agreement. It sets the maximum dollar amount, the commission and the terms for ending the program. The agent is treated as an underwriter for securities law purposes.
- A prospectus supplement. The company files a prospectus supplement under Rule 424(b) describing the ATM offering, the agent and the maximum amount. The sales agreement is usually filed as an exhibit to a Form 8-K or a periodic report.
After that, the company tells the agent how many shares it wants sold, over what period and at what minimum price. The agent sells into the market through ordinary trading, usually pacing orders so they are a modest part of each day's volume. Buyers on the other side of the trade see a normal fill. They generally cannot tell that the shares came from the company.
The company pays the agent a commission on each sale, set in the agreement and commonly a low single-digit percentage of gross proceeds. That is usually cheaper than the combined fee and price discount on a marketed deal.
The rules behind it: Rule 415 and Form S-3
The legal definition sits in SEC Rule 415, the rule that allows delayed and continuous offerings. Paragraph (a)(4) defines an at-the-market offering as "an offering of equity securities into an existing trading market for outstanding shares of the same class at other than a fixed price." The same paragraph requires a primary ATM offering by the company to come within paragraph (a)(1)(x), which covers securities registered, or qualified to be registered, on Form S-3 or Form F-3.
Two other parts of Rule 415 matter for investors:
- The three-year limit. Under paragraph (a)(5), securities registered under (a)(1)(x) may generally be sold only within three years of the registration statement's initial effective date. A company that wants to keep an ATM running files a new shelf before then.
- Rollover of unsold amounts. Under paragraph (a)(6), unsold securities and the fees paid on them can carry over to the new registration statement.
The baby shelf limit
Form S-3 is open to primary offerings of any size when the company's public float, the market value of common equity held by non-affiliates, is $75 million or more. Smaller listed companies can still use the form under General Instruction I.B.6, known as the baby shelf rule, but with a cap.
Under I.B.6, the company may sell no more than one-third of its public float in any period of 12 calendar months. The float is measured at a price from a date within 60 days before the sale, and every sale under the instruction in the trailing 12 months counts against the cap. The company must also be listed on a national securities exchange and must not be, or have recently been, a shell company. If the public float later reaches $75 million, the one-third limit stops applying to further sales under that registration statement.
The cap moves with the share price. When the stock falls, the float falls and so does the amount the company can sell. That is one reason small companies sometimes raise money through other routes as well.
ATM offerings compared with other ways to raise equity
| Method | Price | Timing | Typical discount | Who can buy | Signal to the market |
|---|---|---|---|---|---|
| At-the-market offering | Market price on each sale | Weeks to months, at the company's choice | Little or none beyond commission | Anyone trading the stock | Quiet; seen in filings after the fact |
| Underwritten follow-on | One fixed price | One or two days | Usually priced below the last close | Institutions allocated by the banks | Public announcement and pricing release |
| Rights offering | Fixed subscription price | Several weeks | Often set well below market | Existing holders first | Public, with a record date |
| Registered direct or PIPE | Negotiated fixed price | Days | Often a discount, sometimes with warrants | A small group of investors | Announced by press release and 8-K |
The ATM's advantages for the company are cost and control: no single-day discount, no roadshow, and the option to sell only when the price suits it. The drawback is speed. A company that needs a large amount quickly, or whose stock trades thinly, cannot raise much through daily volume.
A worked example
The figures below are illustrative. Company A (invented ticker QZRB) is hypothetical.
Company A has 50 million shares outstanding at $8.00, a market value of $400 million. Its public float is $300 million, so it is above the $75 million line and can use a regular Form S-3. It has $40 million of cash and burns about $12 million a quarter. It files a $150 million shelf and signs a $75 million ATM sales agreement with a 3% commission.
Two things stand out. First, ownership fell 7.4% even though no deal was ever announced. Second, the new runway changes the near-term risk: the company is no longer close to needing a distressed raise, which is often why the stock reacts less than the dilution alone suggests.
Now take Company B, also hypothetical, with a public float of $60 million. Under the baby shelf rule it can sell at most $20 million in 12 months. If its stock falls by a quarter and the float drops to $45 million, the cap falls to $15 million, less anything already sold in the trailing period. A small company in that position often has less financing room than its headline shelf amount suggests.
Where to find ATM activity in filings
An ATM leaves a paper trail, but it is spread across several documents. The guide to searching SEC EDGAR filings covers how to pull them up.
- Form S-3 and the prospectus supplement. These show the total shelf amount and the maximum ATM amount, the agent and the commission. For baby shelf users, the cover of the prospectus shows the public float calculation and the amount sold in the prior 12 months.
- The 8-K or exhibit with the sales agreement. This sets the terms, including how the program can be ended. Our guide to reading an 8-K for catalysts explains where exhibits sit.
- The 10-Q and 10-K. The equity note and the liquidity section usually report shares sold under the ATM during the period, the proceeds and the remaining capacity. Comparing the share count on the cover page of each 10-Q shows the effect even when the narrative is thin.
- Subsequent events. Many companies disclose ATM sales made after the quarter ended but before the filing date, which brings the share count closer to today.
What an ATM means for the stock
An ATM is a slow event rather than a dated one, but it changes the outlook for several things event-driven investors track.
- Share count. New shares reduce each holder's claim. Our explainer on dilution and share count changes shows how to measure it over time and when it destroys value per share rather than just ownership.
- Cash runway. For a business that loses money, ATM proceeds extend the time before the next financing. When you estimate cash runway, count sold proceeds as cash and treat unused capacity as a likely source with a likely dilution cost.
- Supply pressure. Steady company selling adds supply to the market. In a thinly traded stock, it can cap rallies, because the company has a reason to sell more when the price rises.
- Timing around catalysts. Companies often use an ATM after good news, when the price and volume are high. A sharp move up on a clinical result or a contract win can be followed by heavy ATM use, which shows up a quarter later.
- Going concern and listing risk. A company with a going concern warning and an active ATM is often funding operations quarter to quarter. A falling share price shrinks what it can raise, and a stock that drops far enough may face a reverse stock split to keep its listing.
For recent examples of how financing news and other events move single stocks, see today's biggest stock moves.
Where this goes wrong
Treating an unused program as harmless. A company with little cash and an ATM in place will usually use it. Leaving the capacity out of a share count estimate understates future dilution.
Assuming the full amount is available. Baby shelf users are limited to one-third of public float in 12 months, measured at a recent price. After a decline, the real capacity can be far smaller than the agreement suggests.
Reading the share count only once a year. ATM sales can add several percent a quarter. Annual snapshots hide the pace, and the 10-K may be months out of date by the time you read it.
Ignoring what the cash is for. Selling shares to fund a project that earns a good return is different from selling shares to cover losses. The same ATM can be value-adding at one company and value-destroying at another.
Confusing price weakness with ATM selling. Daily sales are not disclosed in real time, so a weak stock is not proof the company is selling. Wait for the quarterly figures before drawing that conclusion.
Dombey's published research tracks shelf capacity and share count changes before each catalyst; see the research archive.
The bottom line
An at-the-market offering is a company selling new shares into normal trading at market prices, through a sales agent, over a period it controls. SEC Rule 415 defines it and requires an eligible shelf on Form S-3 or F-3, and smaller companies face the baby shelf cap of one-third of public float in any 12 months. It is cheaper and quieter than a priced deal, which is exactly why investors miss it. Read the prospectus supplement for the capacity, the quarterly filings for the pace, and fold both into your share count and runway estimates.