

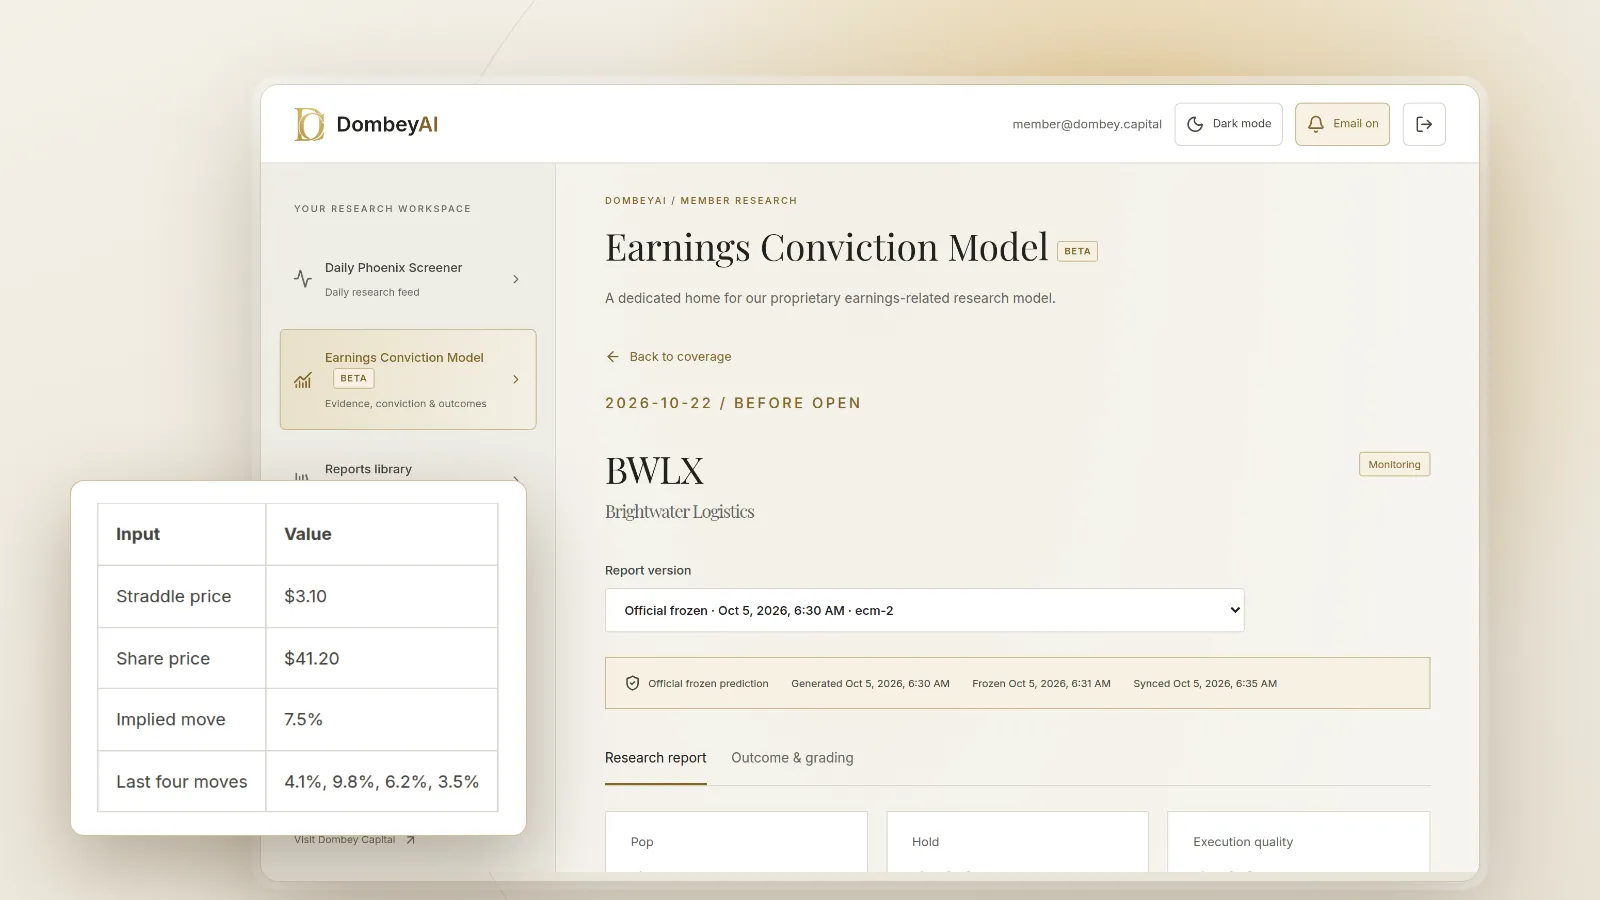
What you need
- The confirmed earnings date and whether the report comes before the open or after the close.
- An option chain with bid and ask prices for the relevant expiry.
- The current stock price.
- A record of the stock's past earnings reactions, measured as the percentage change from the close before the report to the close after it.
- Ten to fifteen minutes per stock.
Step 1: Confirm the earnings date
Check the company's investor relations page or its press release announcing the date. Many data services show estimated dates that are projected from past patterns, and those can be wrong. An estimated date that turns out to be a week late can put the report after the expiry you priced.
Note the timing. A report after the close on a Tuesday will move the stock on Wednesday. A report before the open on Wednesday will also move the stock on Wednesday. The expiry you choose must come after that first trading session.
Step 2: Pick the first expiry after the report
Choose the nearest expiry that falls after the first trading session following the report. If the company reports after the close on Thursday and weekly options expire on Friday, the Friday expiry captures the event with only one day of ordinary trading around it.
A later expiry will also include the event, but it spreads that event across more trading days. More of its price then reflects normal day-to-day volatility. The first expiry gives the cleanest read on the event itself.
If the stock has only monthly options, you may have to use an expiry several weeks out. The estimate will then overstate the earnings component, because the straddle also prices those extra weeks.
Step 3: Price the at-the-money straddle
A straddle is a call and a put with the same strike and expiry. Use the strike closest to the current stock price. Take the mid price of each option, halfway between the bid and the ask, and add them.
Then divide the straddle price by the stock price:
Approximate implied move = (at-the-money call mid + at-the-money put mid) / stock price
A worked example
The numbers below are illustrative. Company A trades at $50.00 and reports after the close on Thursday. The Friday expiry has a $50 strike.
- $50 call: bid $2.30, ask $2.50, mid $2.40.
- $50 put: bid $2.10, ask $2.30, mid $2.20.
- Straddle: $2.40 + $2.20 = $4.60.
- Approximate implied move: $4.60 / $50.00 = 9.2%, or about $4.60 in either direction.
If the stock sits between two strikes, average the straddles at the strikes just above and just below, or weight them by distance from the stock price.
Step 4: Apply the 0.85 adjustment
The straddle price is a reasonable first estimate, but many traders scale it down. A common rule of thumb multiplies the straddle by about 0.85 to estimate the expected move. This is an approximation, not a formula from a pricing model.
The reasoning is loose. The straddle includes some value from ordinary trading days inside the expiry, and option sellers usually demand a premium for taking event risk. Scaling down by about 15% is one way to strip some of that out. Different traders use slightly different factors.
For Company A: $4.60 × 0.85 = $3.91, or about 7.8% of the stock price.
Treat both figures as a range rather than a point. In this example, the options market is pricing a move of roughly 8% to 9% in either direction.
Step 5: Compare with past reactions
Pull the stock's percentage moves on its last eight to twelve earnings reports. Use the absolute size of each move, ignoring direction. Then look at where the current implied move sits in that range.
The numbers below are illustrative. Suppose Company A's past reactions ranged from 3% to 14%, and most fell between 5% and 8%. An implied move of 8% to 9% sits toward the upper part of that history. That suggests the options market expects a somewhat larger reaction than usual, perhaps because of a recent guidance change or a pending catalyst.
Look at the context of each past reaction, not just its size. A 14% move driven by an acquisition announced alongside earnings tells you little about the next report.
| Item | What to use | Watch for |
|---|---|---|
| Earnings date | Company press release or investor relations page | Estimated dates that are not confirmed |
| Expiry | First expiry after the first post-report session | Monthly-only chains that include extra weeks |
| Strike | Closest to the stock price | Stock between strikes |
| Prices | Mid of bid and ask | Wide spreads that make the mid unreliable |
| Implied move | Straddle / stock price | Treat as approximate |
| Expected move | Straddle × about 0.85 | Rule of thumb, not a formula |
| History | Last eight to twelve reactions, absolute size | One-off events that distort the range |
Step 6: Check liquidity and plan for IV crush
Look at the bid-ask spread on each leg. If the call in Company A's example were bid $1.80 and offered $3.00, the mid of $2.40 would mean little. A wide spread tells you the market maker is unsure of fair value or that few contracts trade. Check volume and open interest as well. Thin markets produce noisy estimates.
Then consider what happens after the report. Implied volatility typically rises into earnings and falls sharply once the result is known. This is called IV crush. A straddle bought at $4.60 can lose value even if the stock moves, because the option's remaining time value collapses. A position only gains if the realized move exceeds what was priced, after costs.
That is why the implied move is useful even if you never trade options. It tells you what the market already expects, so you can judge whether a result is likely to surprise.
Where this goes wrong
The implied move is a price, not a forecast. Stocks often move much more or much less than implied, and a single report can land far outside the historical range.
The 0.85 factor is a convention. It has no fixed basis for any single stock, and it can mislead when skew is steep or when the expiry includes several ordinary trading days.
Liquidity matters more than precision. A straddle built from wide quotes can produce an implied move that is off by several percentage points.
Small caps and special situations often have the thinnest option markets. For many of the companies in a special situation screen, listed options may not exist, or may trade too rarely to use. In those cases the balance sheet and the filings carry more information; see how to read a 10-Q for special situations.
Other events can sit inside the same expiry: an investor day, a court ruling, a central bank decision. Each adds to the straddle price and inflates the estimate of the earnings move.
Common mistakes
- Using an unconfirmed earnings date. The whole calculation depends on the event falling before the expiry.
- Picking a later expiry. More time means more ordinary volatility in the price.
- Using last trade prices instead of mids. Last trades can be stale, especially in thin chains.
- Treating 0.85 as exact. It is a rough adjustment.
- Ignoring direction risk. The implied move is symmetrical. It says nothing about which way the stock will go.
- Forgetting IV crush. Being right on direction does not guarantee a profitable option position.
Dombey's published research notes the options-implied move alongside each earnings catalyst where liquid options exist; see the research archive.
The bottom line
The at-the-money straddle in the first expiry after earnings, divided by the stock price, gives a quick approximation of the move the options market expects. Scaling it by about 0.85 is a common rule of thumb, not a precise adjustment. Compare the result with the stock's own history, check that the options are liquid enough to trust, and remember that implied volatility usually falls once the report is out. Use the figure to understand expectations, not as a signal to trade.