

What you need
- The REIT's latest 10-K and 10-Q, including the property schedule and debt maturity table.
- The quarterly supplemental package, which most REITs post on their investor relations site with FFO, AFFO, same-property results, leasing data and capital spending.
- The company's FFO reconciliation, usually in the earnings release.
- Recent market capitalization rates for the REIT's property types, from broker research, deal announcements or peer disclosures.
- A list of three to five peers that own the same kind of property.
- A spreadsheet.
If you are new to the filings, our guides to reading a 10-Q for special situations and reading a cash flow statement cover where each item lives.
Step 1: Identify what the REIT owns and how it earns
Start with the property schedule and the business description. Note:
- Property type. Industrial, office, retail, residential, healthcare, data center, self-storage and others behave differently and trade on different multiples.
- Lease structure. Long net leases, where tenants pay taxes, insurance and maintenance, produce steadier cash flow than short gross leases.
- Occupancy and lease expiries. The schedule of leases expiring by year shows how much rent resets soon.
- Tenant concentration. A large share of rent from one tenant is a single point of failure.
- Development pipeline. Projects under construction tie up capital before they earn.
Mortgage REITs, which own loans and securities rather than buildings, need a different approach based on book value and spreads; this guide covers equity REITs.
Step 2: Calculate FFO from the reconciliation
FFO is the industry's standard earnings measure, defined by Nareit. Starting from net income attributable to common shareholders:
| Line | Treatment |
|---|---|
| Net income | Starting point |
| Depreciation and amortization of real estate | Add back |
| Gains on sales of depreciable real estate | Subtract |
| Losses on sales of depreciable real estate | Add back |
| Impairment write-downs of depreciable real estate | Add back |
| Adjustments for unconsolidated joint ventures and partnerships | Apply the same rules to the REIT's share |
| FFO | Divide by diluted shares and units for FFO per share |
REITs report FFO with a reconciliation to net income. Use the company's figure, but check it against the rules above. Some REITs also report "core" or "normalized" FFO that removes further items such as debt extinguishment costs or transaction expenses. Note which version you use and keep it consistent across peers.
Step 3: Adjust to AFFO
FFO ignores the money a landlord must spend to keep buildings leased. AFFO, sometimes called funds available for distribution, corrects for that. A typical build:
- Start with FFO.
- Subtract recurring capital expenditures: roof, mechanical and other maintenance spending.
- Subtract tenant improvements and leasing commissions on renewals and re-leasing.
- Subtract straight-line rent adjustments, the non-cash difference between accounting rent and cash rent.
- Add back non-cash stock compensation and amortization of debt costs, if you treat them as non-cash.
AFFO has no standard definition, so two REITs can report very different AFFO for similar results. Rebuild it yourself from the supplemental package where you can. For office and retail REITs, tenant improvements and leasing commissions can be a large share of FFO, so this step often changes the picture.
Step 4: Estimate net asset value
NAV values the properties as if they were sold today, then subtracts what the REIT owes.
- Take next year's expected net operating income (NOI): property revenue minus property operating expenses, before depreciation, interest and corporate overhead. Use the same-property figures in the supplemental package.
- Divide by a capitalization rate, the yield buyers accept on that property type in that market. A lower cap rate means a higher value.
- Add cash, land, development at cost and other assets.
- Subtract total debt, preferred stock and other liabilities.
- Divide by diluted shares and operating partnership units.
The cap rate drives the answer. A 0.5 percentage point change in cap rate on a large portfolio can move NAV per share by double digits. Show a range, not a point. Our explainer on real estate hidden in balance sheets uses the same income approach for non-REIT companies.
Step 5: Work through an example
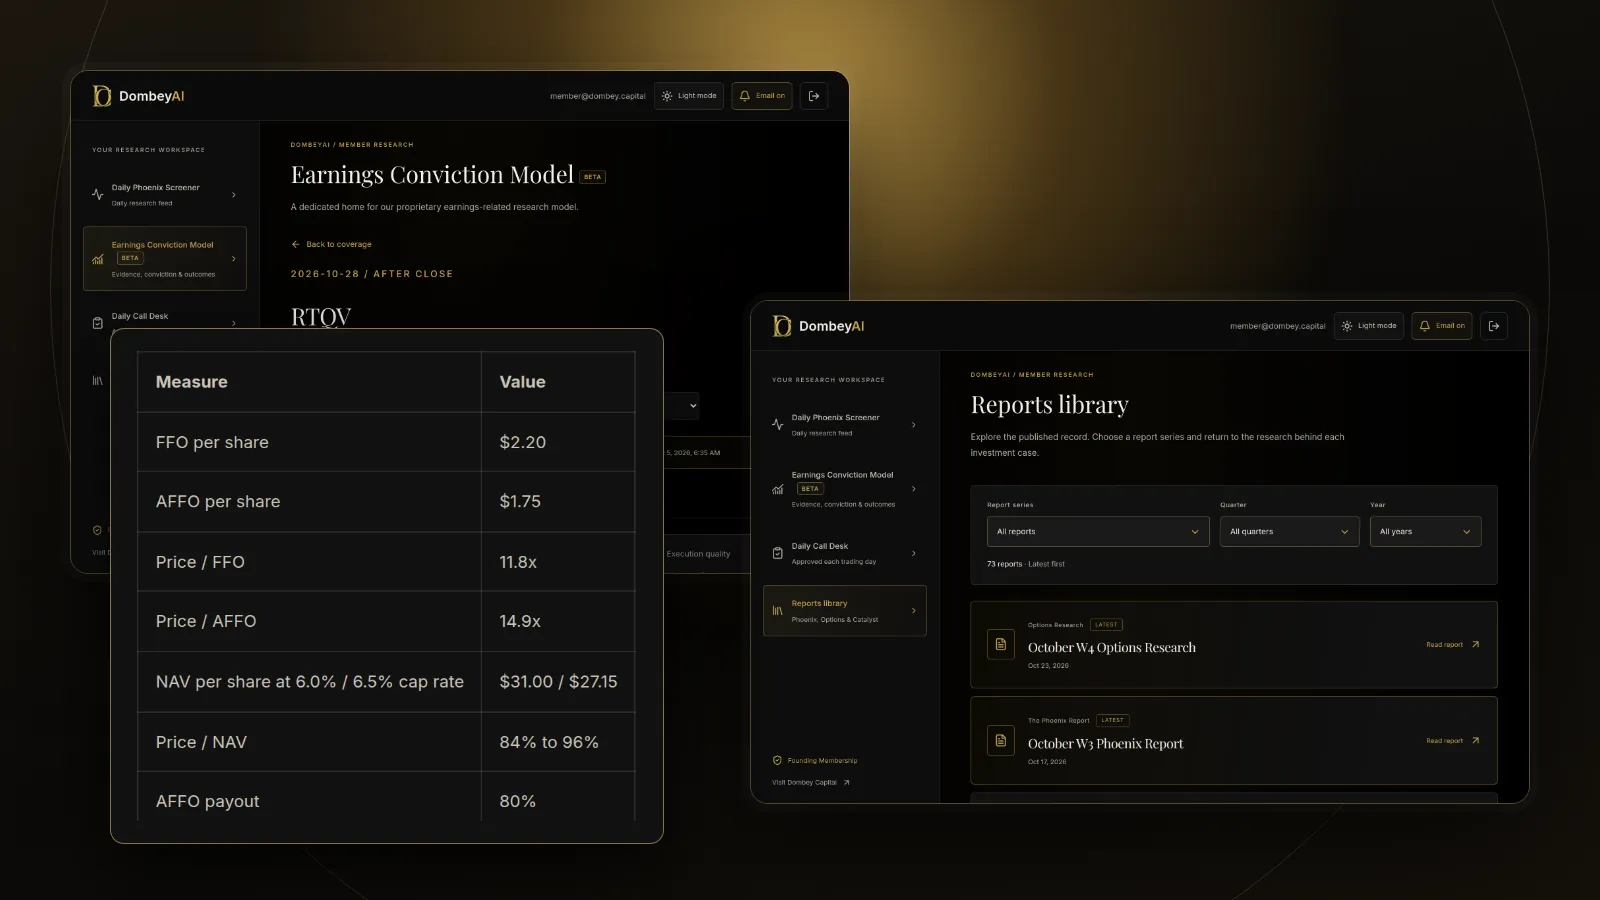
Put the results side by side:
| Measure | REIT A | What to compare it with |
|---|---|---|
| Price / FFO | 11.8x | Peers in the same property type |
| Price / AFFO | 14.9x | Peers, using a consistent AFFO build |
| Price / NAV | 84% to 96% | Peers and recent private market sales |
| AFFO payout | 80% | Peers and the REIT's own history |
| Net debt / NOI | 6.3x | Peers and the REIT's own target |
Step 6: Test the dividend
REITs must distribute at least 90% of taxable income to keep their tax status, so the dividend is central to how they are owned. Check:
- AFFO payout ratio. Dividends per share divided by AFFO per share. A ratio near or above 100% leaves no room for error.
- Trend. Is AFFO per share growing, flat or falling? A covered dividend on falling AFFO may not stay covered.
- Taxable income. Because the 90% test is on taxable income, a REIT can sometimes pay less than AFFO, or pay part of the dividend in stock in some circumstances. Read the dividend policy.
A dividend yield well above peers is often the market's warning, not a gift.
Step 7: Check leverage and refinancing
REITs retain little cash, so they depend on debt and equity markets. Read the debt table for:
- Net debt to EBITDA or to NOI. Compare with peers and the REIT's own targets.
- Maturities. How much debt comes due in each of the next three years, and at what rate it was borrowed. Debt refinanced at higher rates lowers future FFO. Our guide to debt maturity walls explains the risk.
- Fixed versus floating rate. Floating rate debt passes rate changes straight into FFO.
- Secured versus unsecured. Unsecured debt with covenants limits flexibility in different ways from property mortgages.
- Covenants. Unsecured bond and credit facility covenants often cap leverage and require minimum coverage ratios.
Step 8: Compare with peers and decide what the gap means
With FFO and AFFO multiples, NAV and the dividend checks done, compare REIT A with peers that own the same property type. A REIT that trades well below NAV and peers is either mispriced or carrying a problem the market sees: rising vacancies, heavy capital needs, a maturity wall or a weak tenant. The work in steps 1, 3 and 7 should tell you which.
Large discounts to NAV are one reason REITs become special situations: boards sometimes respond with asset sales, buybacks, a strategic review or a sale of the company. Our explainers on asset sales and strategic reviews cover what happens next. Our guide to sum-of-the-parts valuation helps when a REIT owns several property types that deserve different cap rates.
For tools that bring REIT filings and peer data together, see the best stock research tools for individual investors.
Common mistakes
- Using net income or EPS. Real estate depreciation makes GAAP earnings a poor guide to REIT cash flow.
- Trusting reported AFFO as comparable. Each REIT defines it differently. Rebuild it or at least read the definitions.
- Using one cap rate. NAV is a range. A point estimate hides how sensitive the answer is.
- Comparing across property types. Office and industrial REITs trade on different terms for good reasons.
- Ignoring capital spending in office and retail. Tenant improvements and leasing commissions can absorb much of FFO.
- Treating a high yield as cheap. A high yield often signals a dividend the market expects to be cut.
- Skipping the maturity table. Refinancing at higher rates can lower FFO for years.
Dombey's published research applies asset-based valuation like this when a discount and a catalyst coincide; see the research archive.
The bottom line
Value a REIT on FFO and AFFO for earnings power and on NAV for the worth of its properties, then test the dividend and the balance sheet. Rebuild AFFO where you can, show NAV as a range across cap rates and compare only with peers that own similar properties. A discount to peers or NAV is a question, not an answer: the leasing data, capital spending and debt maturities usually show whether it is a mispricing or a fair price for a problem.