

What you need
- The latest 10-K and any 10-Q filed since. The segment note in the financial statements is the core input. The guide on searching SEC EDGAR filings shows how to pull them.
- An enterprise value build for the whole company, so you know the debt, cash and other claims. See how to calculate enterprise value.
- A short list of comparable listed companies for each segment, with their EV/EBITDA or other multiples.
- Market prices for any listed stakes the company holds.
- A spreadsheet with one row per part and a column for the source of each figure.
Step 1: Map the parts from the filings
Start with Item 1 of the 10-K, which describes the business under Item 101 of Regulation S-K, and then go to the segment note in the financial statements under Item 8. The segment note lists each reportable segment with its revenue and a profit measure, and reconciles the segment totals to consolidated results. That reconciliation shows the unallocated corporate costs you will need in Step 5.
Then list everything that is not in an operating segment: equity-method investments, listed stakes, real estate not used in operations, tax assets, and businesses held for sale. These often sit in the investments note, the property note or the discontinued operations note. A 10-K is due 60 days after fiscal year end for large accelerated filers, 75 days for accelerated filers and 90 days for all other registrants, so check the 10-Qs and 8-Ks filed since for asset sales or acquisitions that change the map. The 10-Q guide for special situations shows where these notes sit in a quarterly filing.
Step 2: Pick a profit measure for each segment
Use the profit measure the company reports for its segments, and convert it to a common basis if you can. Many companies report segment operating income. If the note also gives segment depreciation and amortization, add it back to get segment EBITDA, which lets you use EV/EBITDA multiples from comparable companies.
Check three things before moving on:
- Allocation. Some companies push corporate costs into the segments; others keep them in a separate line. Read the accounting policy for segments so you do not count overhead twice or not at all.
- Inter-segment sales. Revenue between segments is eliminated in the consolidated figures. Use external revenue when you compare a segment with peers.
- Period. Use trailing twelve months or the latest fiscal year for every segment. Mixing periods distorts the total.
Step 3: Choose a valuation method for each part
Each part gets the method that fits how a buyer or the market would price it on its own.
| Part | Typical method | Where the input comes from |
|---|---|---|
| Mature operating segment | EV/EBITDA or EV/EBIT from listed peers | Segment note, peer filings |
| Fast-growing or loss-making segment | EV/sales from listed peers | Segment note, peer filings |
| Listed stake in another company | Market price x shares held, less tax on gain | Investments note, market quote |
| Unlisted stake or joint venture | Share of earnings x peer multiple, or book value | Equity-method note |
| Surplus real estate | Appraisal, recent comparable sales, or book value | Property note, local sale records |
| Cash-generating runoff business | Discounted cash flow of the remaining flows | Segment note, MD&A |
Use a range of multiples for each segment, not one figure. A low, base and high case built from the spread of peer multiples gives you a sense of how much the answer depends on judgment. The price-to-sales explainer covers when a sales multiple is appropriate.
Step 4: Value each operating segment
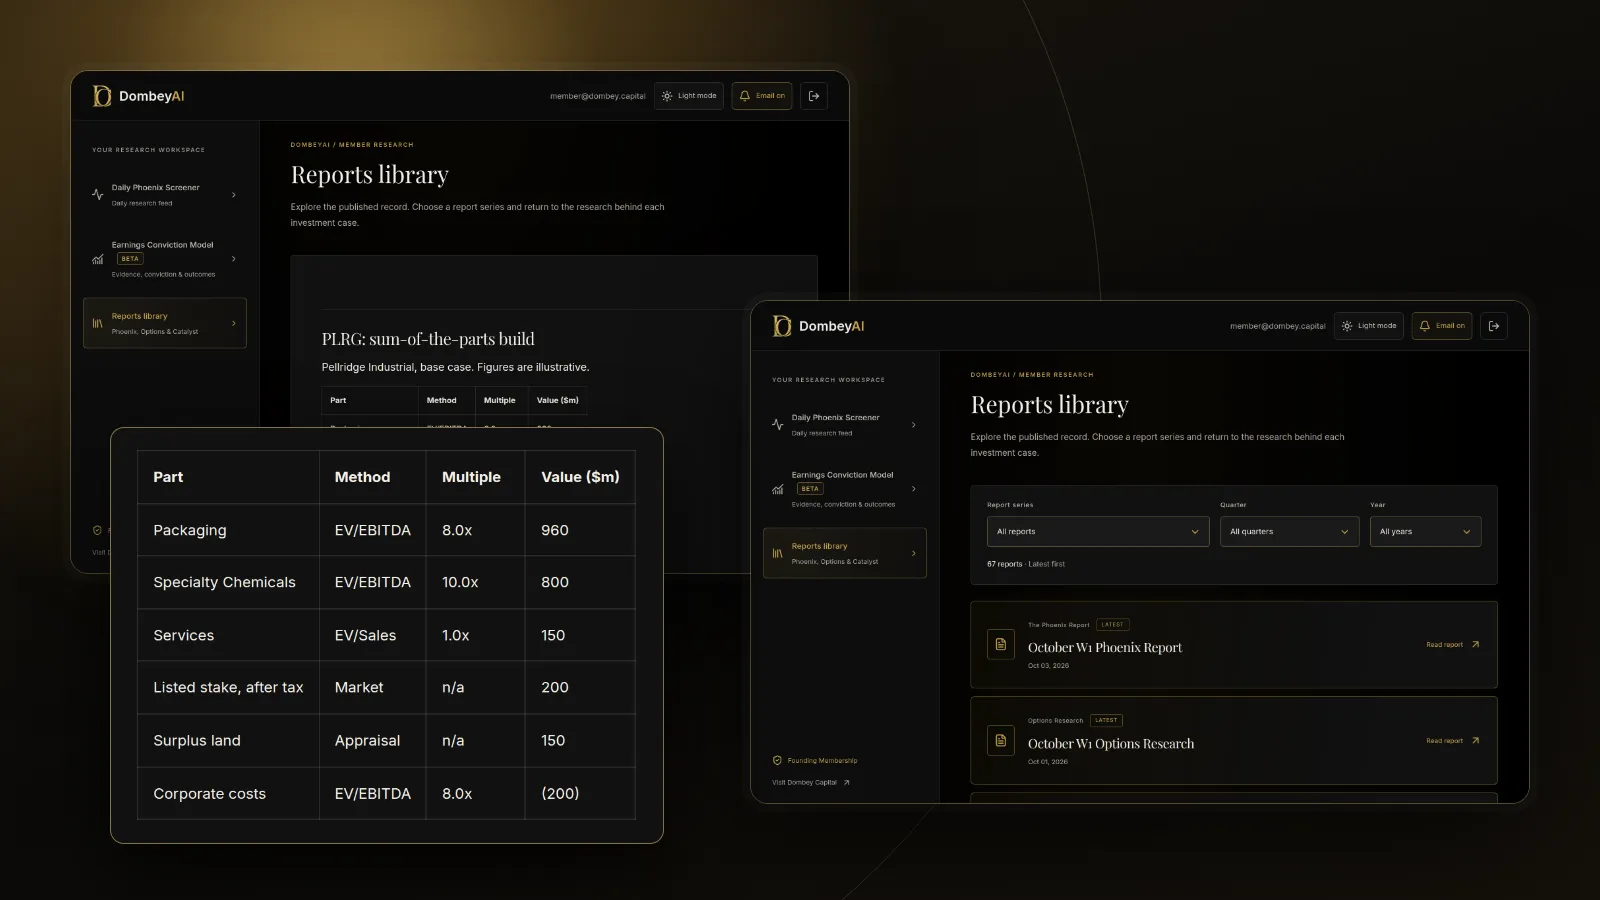
Multiply each segment's profit measure by its chosen multiple. The result is the enterprise value of that segment, before corporate costs and before debt.
Be honest about fit. A segment that is smaller, slower or more cyclical than its listed peers deserves a lower multiple than their median.
Step 5: Subtract capitalized corporate costs
The segment reconciliation usually shows a line called corporate, unallocated or eliminations. It covers head office, the board, public company costs and some shared services. Those costs are real, and they would not all disappear if the businesses were separated, because each standalone company would need some of its own.
Capitalize the annual cost at the blended multiple of the segments and subtract it. If you expect a separation to remove part of the cost, show that as a separate scenario, not as your base case.
Step 6: Add the non-operating assets
Now add the parts that do not earn segment profit.
- Listed stakes: shares held times the current market price. If the company would have to sell the stake to realize the value, subtract tax on the gain over its tax basis, which is often disclosed in the income tax or investments note.
- Unlisted stakes: use the share of the investee's earnings times a peer multiple, or the carrying value if the earnings are small or erratic.
- Surplus real estate: use an appraisal or recent comparable sales if available, and book value as a floor-level fallback.
Do not add an asset whose income is already in a segment's EBITDA. That counts the same value twice.
Step 7: Bridge from enterprise value to equity per share
Add the segment values and non-operating assets, subtract capitalized corporate costs, then subtract the same claims you would in any enterprise value build: debt, preferred stock, noncontrolling interest and debt-like items such as an unfunded pension. Add back cash and liquid investments. Divide by fully diluted shares.
| Line | Company A ($ millions) |
|---|---|
| Operating segments | 1,910 |
| Less capitalized corporate costs | (200) |
| Plus listed stake, after tax | 200 |
| Plus surplus land | 150 |
| Less net debt | (500) |
| Less pension deficit and noncontrolling interest | (70) |
| Equity value | 1,490 |
| Per share (100 million diluted shares) | $14.90 |
At a price of $10.00, Company A trades about 33% below this base-case sum of the parts (illustrative). The net cash per share explainer covers the cash and debt side of this bridge in more detail.
Step 8: Run a range and test the largest inputs
A single number hides how fragile the result is. Build a low, base and high case, changing the multiples, the real estate value and the tax assumption together.
Then ask which single input moves the answer most. Usually it is the multiple on the largest segment. If one turn of that multiple moves the per-share value by more than the discount you think you see, the discount is less certain than it looks.
Step 9: Identify what would close the gap
A sum of the parts above the share price is a description, not a reason the price will change. Many multi-business companies trade below their parts for years. Look for a mechanism and a date:
- If the company has announced a spin-off, the Form 10 will show standalone financials for the business being separated. See what a Form 10 is and spin-off investing.
- If an activist has filed a 13D asking for a break-up, the filing states its plans. See what a 13D filing is.
- If the company is selling a division, the price paid tests your multiple directly.
- If the company is buying back stock below your estimate, each repurchase raises value per remaining share.
- If none of these apply, the gap may persist, and the honest conclusion is that the parts are cheap without a catalyst.
Dombey's published research pairs this kind of break-up analysis with the dated event that could close the gap; see the research archive. Record the result, its range and the expected catalyst date in a dated investment thesis.
Common mistakes
- Using the consolidated multiple for every segment. That defeats the purpose of the exercise and returns roughly the current market value.
- Ignoring corporate costs. Leaving out head office expense inflates the total, often by several percent of equity value.
- Counting an asset twice. An equity-method stake whose income sits inside segment EBITDA should not also be added as a separate asset.
- Valuing stakes before tax. A sale at a large gain triggers tax. Only a tax-free separation avoids it, and that is not certain.
- Choosing peers that flatter. Picking the highest-multiple peer for each segment produces a large discount that no buyer would pay.
- Forgetting separation costs. Separated businesses lose shared purchasing, shared IT and shared sales teams. Standalone costs can be higher than the segment note suggests.
Where this goes wrong
Segment data is limited. Companies choose their own segment boundaries and profit measures, and allocation of shared costs can make a weak segment look stronger than it would be alone. Peer multiples move with the market, so a sum of the parts built at a high point for one industry can shrink quickly. Separation itself costs money: advisory fees, new systems, new boards and possibly tax, and the parts may not trade where you assumed once they stand alone. The method also says nothing about timing. A discount can widen before it closes, and the capital you commit has an opportunity cost while you wait. Use the result as a range and a set of questions for the next filing, not as a fixed value.
The bottom line
A sum-of-the-parts valuation values each business and asset on its own terms, then subtracts corporate costs and the claims ahead of common shareholders. The segment note in the 10-K is the starting point, and each part needs a method and a peer group that fits it. Run a low, base and high case, because the multiple on the largest segment usually drives the answer. A gap between the parts and the price matters only when a spin-off, sale, activist or buyback gives it a way to close.