

Oct 28, 2026: a premarket gain that kept building after the open
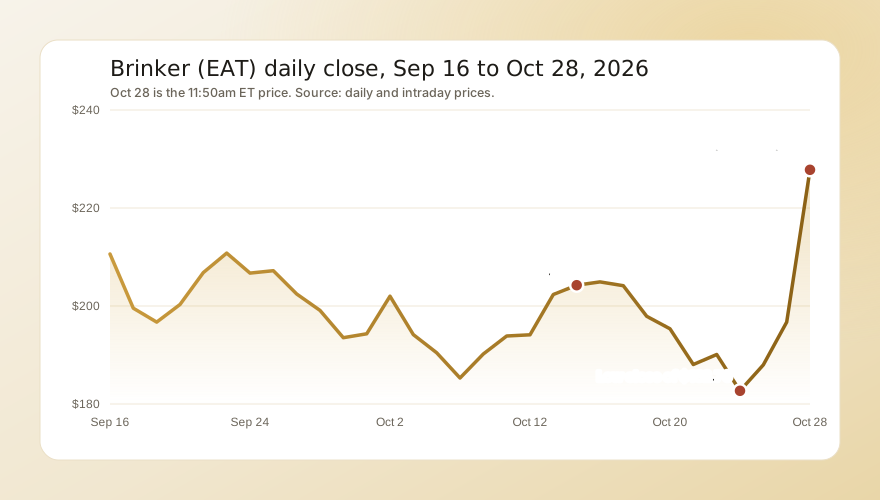
Brinker released results at 7:45am. The stock opened premarket trading at $195.50 just after 4am, dipped to $191.99 at 5:30am, and climbed to $210.01 by 9:10am once the numbers were out. It opened the regular session at $207.00, touched $201.83 in the first minutes, and then rose through the morning to $231.74 at 11:25am, up 17.8%. At 11:50am it was $227.79 on 1.74 million shares.
What lifted it:
- Traffic, not just price. Chili's traffic rose 6.4% and price added 3.7%, with mix flat. CEO Kevin Hochman said Chili's "delivered its 22nd consecutive quarter of same-store sales growth, up +10%, lapping a +21% from last year." Analysts had expected comparable sales of 8.5% to 9.5%, Investing.com reported before the release.
- Margins widened. Restaurant operating margin rose to 17.7% of company sales from 16.2%, and operating income rose to $151.0 million, 10.2% of revenue, from $117.9 million.
- A raised outlook. Fiscal 2027 adjusted EPS guidance rose by $0.60 at the middle and revenue guidance to $6.23 billion to $6.33 billion. The year includes a 53rd week, which Brinker estimates adds about 2.0% to revenue and $0.70 to EPS.
From the Oct 27 close, at about 11:51am:
| Stock or fund | Oct 27 close | Oct 28, 11:51am | Change |
|---|---|---|---|
| Brinker (EAT) | $196.72 | $227.79 | +15.8% |
| Texas Roadhouse (TXRH) | $166.71 | $174.46 | +4.7% |
| Darden (DRI) | $213.96 | $219.65 | +2.7% |
| SPDR S&P 500 (SPY) | $769.66 | $771.23 | +0.2% |
| Consumer Discretionary SPDR (XLY) | $115.45 | $114.93 | -0.5% |
| Cheesecake Factory (CAKE) | $108.47 | $106.24 | -2.1% |
After the jump, RSI(14) stood at 66, the shares sat 8% above their 50-day average and 31% above their 200-day average, volume ran 1.4 times its 20-day average, and the stock was 11% below its 52-week high of $254.99.
The numbers
| Measure | Q1 fiscal 2027 | Q1 fiscal 2026 |
|---|---|---|
| Total revenues | $1,475.6M | $1,349.2M |
| Chili's comparable sales | +10.1% | +21% |
| Restaurant operating margin | 17.7% | 16.2% |
| Operating income | $151.0M | $117.9M |
| Adjusted EPS | $2.77 | $1.93 |
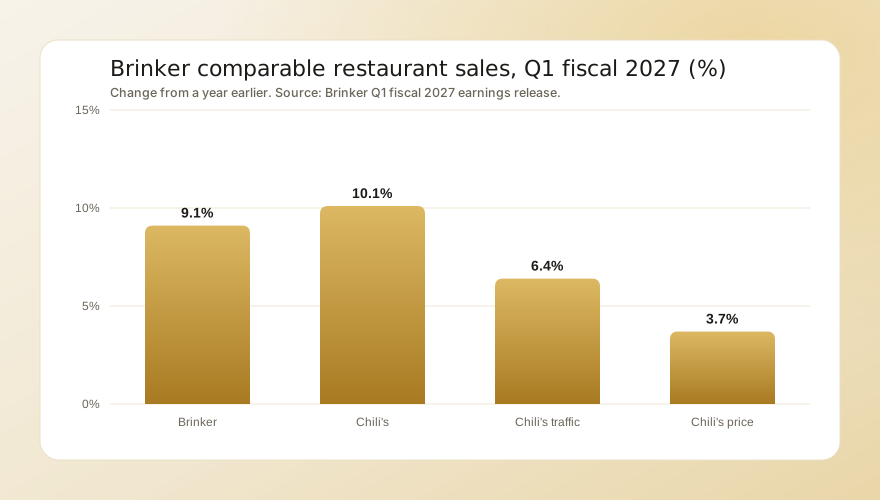
Revenue rose 9.4%. Brinker also redeemed $350 million of 8.25% notes with its revolving credit line, which cost a $17.6 million loss on the early payoff and replaces fixed 8.25% debt with bank borrowing. GAAP EPS was $2.64, against $2.17 a year earlier. Our guide on how to read an earnings release shows how adjusted and GAAP figures fit together in a report like this.
Why the stock had been weak
The shares closed at $182.70 on Oct 23, down 28% from the high. The worry was arithmetic: Chili's had grown comparable sales 21% in the same quarter a year earlier, and it is hard to keep adding traffic on that base. Several firms that kept buy ratings still trimmed targets before the report, citing shifting sentiment, Investing.com reported, and CNBC wrote before the reports that restaurant earnings would test whether owning more brands pays off. A 10.1% gain with 6.4% more guests is the answer the market was waiting for. Our page on why guidance changes move stocks explains why a raised outlook usually matters more than the quarter itself.
The bull case
- Share gains are still running. Twenty-two straight quarters of comparable sales growth at Chili's, with traffic leading.
- Estimates should rise. The new EPS range sits above the $13.28 analyst average, and our page on earnings estimate revisions covers why upward revisions tend to support a stock after the first day.
- The valuation is moderate. About 16.7 times the middle of the guide; see our explainer on forward and trailing P/E.
- Cash returns. Brinker bought back $125 million of stock in the quarter with operating cash flow, and free cash flow nearly doubled to $105.7 million, Investing.com reported.
The risks
- The comparison gets harder before it gets easier. Analysts had expected comparable sales to slow to 3% to 4% in the current quarter.
- Maggiano's is shrinking. Comparable sales fell 3.4%, with traffic down 5.1%.
- The 53rd week flatters the year. It adds about $0.70 of EPS that will not repeat in fiscal 2028.
- A fast move. A 16% gain in a morning leaves room for some of it to fade if the broader market turns.
What comes next
- Estimate and target changes this week. Watch whether the analyst average moves above the new guidance midpoint.
- Traffic data through the holidays. Chili's value menu and marketing carried the quarter; any slowdown in guest counts would show up first.
- The fiscal second-quarter report, likely in late January 2027. Watch Chili's traffic, restaurant operating margin against 17.7%, and whether the EPS range holds.
For more of the day's large moves, see today's biggest stock moves.