

Nov 3, 2026: a profit beat on a shrinking share count
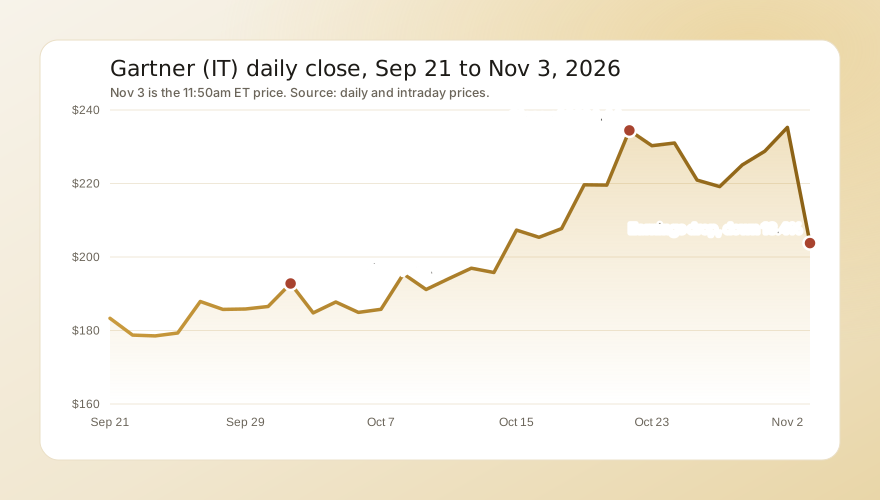
Gartner closed Nov 2 at $235.26, near the top of a run that took it from $192.80 on Oct 1. It reported before the open and held its call at 8:00am ET. Premarket trading ranged from $215.00 to $233.99. The stock opened at $208.00, which was the high of the regular session, and dropped to $184.95 at 9:35am, down 21.4%, before buyers stepped in. At 11:50am it was $203.78, down 13.4%, on about 1.3 million shares.
What moved the stock:
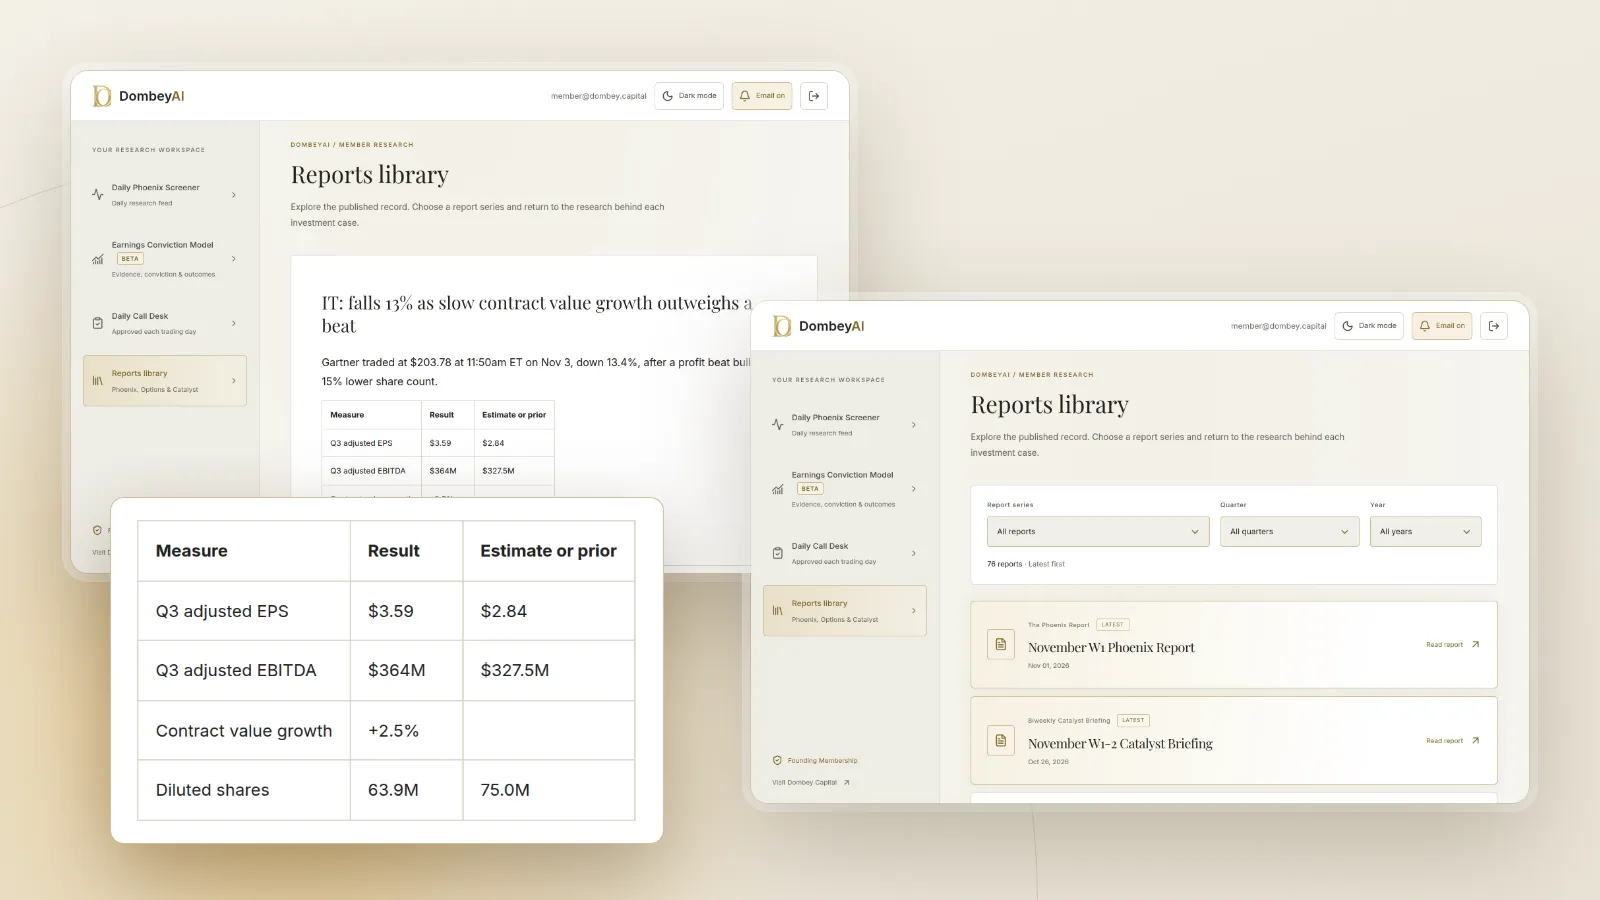
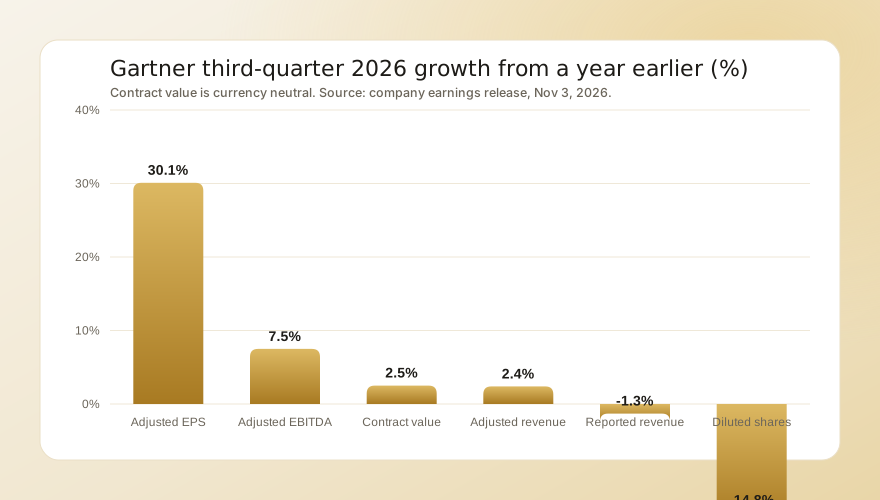
- Contract value growth is still slow. Currency-neutral contract value rose 2.5% from a year earlier and 1.1% from the prior quarter. Technology buyers, the larger group at $4.0 billion, grew 2.1%, and business functions, at $1.3 billion, grew 3.7%. Chief executive Gene Hall said contract value growth "accelerated again," but from a low base.
- Buybacks did much of the earnings work. Adjusted earnings rose 30.1% to $3.59 a share, and IBTimes noted that the per-share figure used 63.9 million diluted shares against 75.0 million a year earlier. Adjusted EBITDA excluding the sold business rose 7.5%.
- The run-up left little room. The shares had gained about 25% in the month before the report, IBTimes reported, so an in-line growth picture was not enough.
- Research peers fell less. Forrester was down 1.7%, Verisk down 1.5%, S&P Global down 1.6% and FactSet down 3.0% late in the morning, a sign some of the selling was about AI risk to the whole group.
At 11:50am RSI(14) was 47, and the stock sat 3.8% below its 20-day average but still 3.6% above its 50-day and 20.8% above its 200-day average.
The numbers
| Measure | Q3 2026 | Year earlier | Change |
|---|---|---|---|
| Reported revenue | $1,505 million | $1,524 million | -1.3% |
| Adjusted revenue | $1,505 million | $1,469 million | +2.4% |
| Insights revenue | $1,292 million | $1,271 million | +1.7% |
| Adjusted EBITDA, excluding divested business | $364 million | $339 million | +7.5% |
| Adjusted EPS | $3.59 | $2.76 | +30.1% |
| Free cash flow | $275 million | $269 million | +2.2% |
| Diluted shares for adjusted EPS | 63.9 million | 75.0 million | -14.8% |
Insights, the research subscription business, is 86% of revenue and grew 1.7%, with a 77.6% contribution margin. Conferences grew 15.4% and consulting 2.3%. GAAP earnings of $3.35 a share were up more than sixfold from $0.47 a year earlier, on net income of $214 million against $35 million. Our explainer on buybacks as catalysts covers when a falling share count deserves credit and when it is masking slow growth, and the rest of the session's movers are in today's biggest stock moves.
The bull case
Gartner is a high-margin subscription business that throws off cash. Free cash flow was $275 million in the quarter and the company now guides to at least $1.235 billion for the year, which funds buybacks of more than 10% of the share count a year at recent rates. Contract value growth has improved for three quarters in a row, margins in Insights rose, and the morning low of $184.95 was close to the average analyst target, a level where some buyers clearly saw value.
If the fourth quarter shows contract value growth heading toward the mid single digits, the per-share math works again: modest growth plus a shrinking share count can still produce double-digit earnings growth. Our page on free cash flow yield shows how to weigh that cash against the price.
The risks
The core risk is that 2.5% is the new normal. Gartner sells research and advice to technology and business leaders, and AI tools now answer many of the questions those leaders used to pay analysts for. A business growing low single digits does not usually hold a premium multiple, and buybacks cannot shrink the share count forever without more borrowing.
The second risk is the setup. A 22% run in a month priced in a clear acceleration, and the report delivered a slight one. The average analyst target is below the price, so there is little support from the Street, and our guide to earnings estimate revisions explains why targets tend to follow the price lower after a report like this. Our page on post-earnings announcement drift covers why gaps on slow growth often keep going.
What comes next
The fourth-quarter contract value number is the next real test. The company has not set a date for its fourth-quarter report, which usually comes in early February. Before then, watch for analyst target changes after the call, any comments at investor conferences about renewal rates, and whether the stock holds the $184.95 morning low. A close back above $215 would undercut the Bearish case.