

Nov 2, 2026: a beat on volume and a raised outlook
IDEXX released results before the open. The stock had traded as low as $538.30 at 5:30am in thin premarket trading, then climbed to $593.81 by 8:25am as the numbers were digested. It opened at $621.22, reached a high of $662.98 at 9:50am, and held near $656 through midday on about 1.0 million shares, 1.9 times the 20-day average.
What changed:
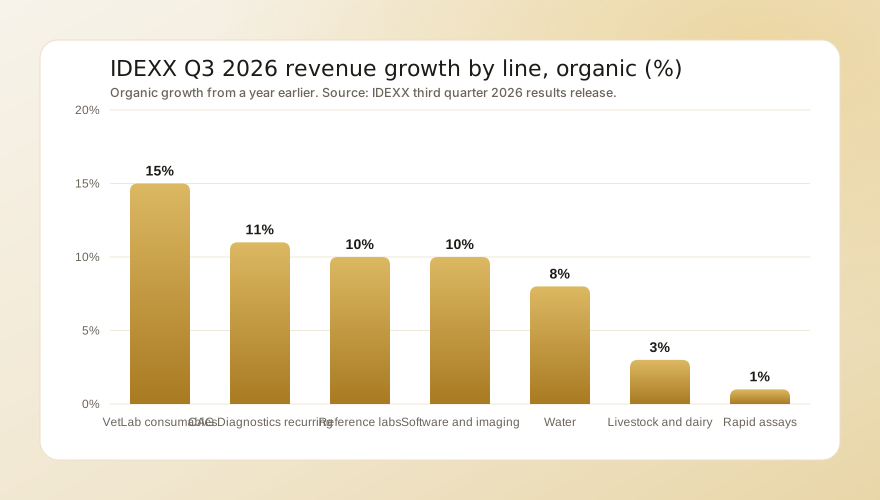
- Revenue beat on volume. Reported and organic revenue both grew 10%. The company said growth was led by volume expansion, not only price.
- Recurring diagnostics accelerated. CAG Diagnostics recurring revenue grew 11% organically, with international up 14% organically and the U.S. up 10%.
- Instrument placements. IDEXX placed over 1,900 inVue Dx analyzers in the quarter, taking the installed base to nearly 11,000.
- Margins widened. Gross margin was 62.9%, up 110 basis points, and operating margin was 33.1%, up 100 basis points.
- Guidance went up. The 2026 EPS outlook rose $0.25 at the midpoint, to $14.96 to $15.16.
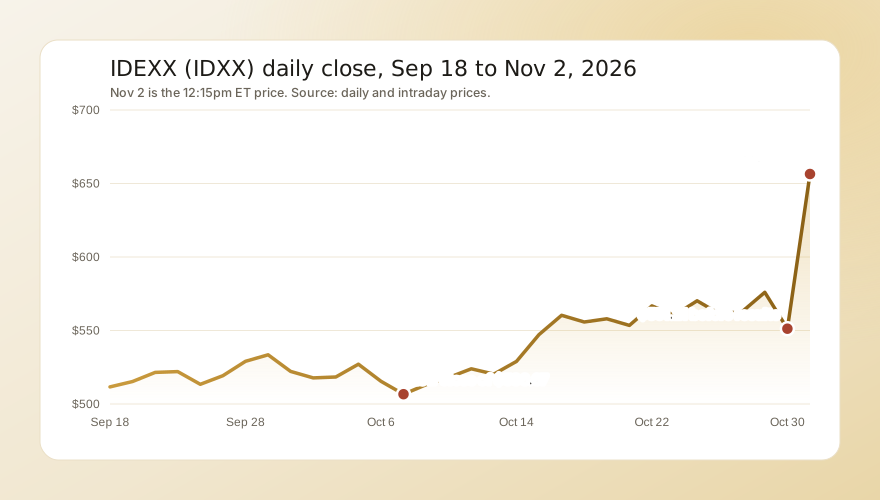
The jump took RSI(14) to 75, an overbought reading, and lifted the shares 22% above their 50-day average and 15% above their 200-day average. The 52-week high of $769.98 is the next reference above.
The numbers behind the move
IDEXX's business is built on recurring testing revenue: the consumables clinics buy to run tests on IDEXX analyzers, reference lab work, and software subscriptions. All of the large recurring lines grew at or near double digits.
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $1,214 million | $1,105 million | +10% |
| EPS | $4.01 | $3.40 | +18% |
| Gross margin | 62.9% | 61.8% | +110 bp |
| Operating margin | 33.1% | 32.1% | +100 bp |
The weak spots were small. Rapid assay revenue grew only 1%, as price offset lower testing volumes, and capital instrument revenue was flat even with the inVue placements. Livestock, poultry and dairy grew 3%.
Guidance: higher revenue, lower margin
IDEXX raised its 2026 revenue outlook to $4,741 million to $4,767 million, up $32 million at the midpoint, of which $5 million comes from the CoVet acquisition. Organic growth guidance rose to 9.3% to 10.0%, up 0.6 points at the midpoint, and CAG Diagnostics recurring organic growth is now expected at 10.3% to 11.0%.
The one cut was to the reported operating margin outlook, now 32.1% to 32.3%. CoVet, an AI clinical assistant for veterinary teams, adds costs before it adds much revenue. Even so, the EPS range moved up, which tells you the revenue raise more than covers the deal costs. Our guide to guidance changes explains why a raised outlook usually matters more to a stock than the quarter itself, and why earnings estimate revisions tend to follow for weeks.
The case for the stock
- Growth is coming from volume. Volume-led growth is more durable than price-led growth, and it is the clearest sign that clinics are running more tests per visit.
- The installed base keeps growing. Nearly 11,000 inVue Dx analyzers, plus an 11% expansion of the global premium instrument base, means more machines pulling through consumables for years.
- Room to the old high. The stock closed between $507 and $576 throughout October and is still 15% below its $769.98 high. Analysts' average price target before the report was about $692, and those targets are likely to move up with the guidance.
The risks
- Valuation. At about 46 times trailing earnings and about 43 times the 2026 EPS midpoint, IDEXX is priced for steady double-digit recurring growth. Our explainer on forward P/E vs trailing P/E shows why the forward multiple is the one to watch here.
- Clinic visits. Rapid assay testing volumes fell in the quarter, and IDEXX lists U.S. clinical visit trends as a risk to its outlook. If visits weaken, test volumes follow.
- The margin cut. A lower margin outlook means CoVet must start paying off. If the integration costs run longer, the margin story weakens.
- Overbought. An RSI of 75 after a 19% day often leads to a pause or a partial giveback.
What comes next
IDEXX's next dated event is its fourth-quarter report, usually in early February, when it gives its first 2027 outlook. Before then, analyst target changes in the next few days will show how far estimates move. Our primer on earnings catalysts covers how to read the setup into the next report, and the rest of the day's swings are in today's biggest stock moves.
This is a view on direction over that window, not a recommendation to trade the stock.