

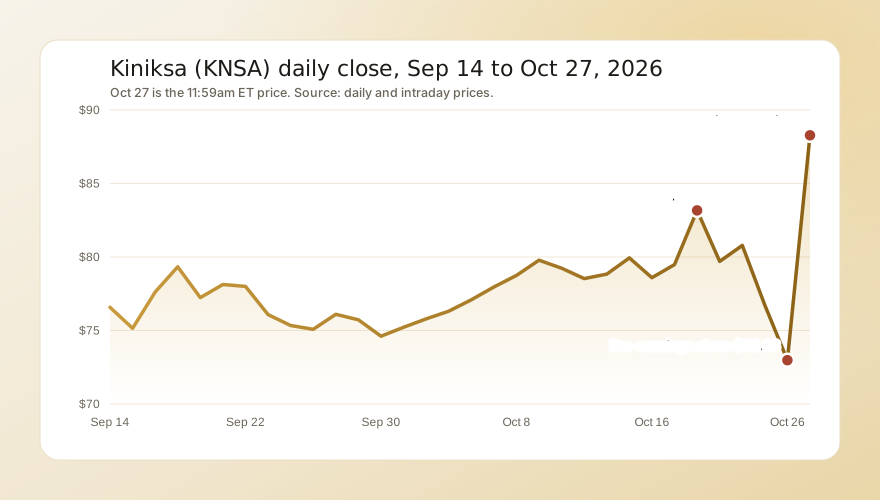
Oct 27, 2026: a gap higher at the open and a new 52-week high
Kiniksa released results before the open, at 7:30am ET, and held its call at 8:30am. The stock opened at $84.52, 15.8% above Monday's close. Its low for the session was $82.26, which still left it 12.7% higher on the day, and it reached $88.44, a new 52-week high. At 11:59am it was $88.28 on about 1.0 million shares, already more than its 20-day average for a full day.
The jump also reversed a slide into the report. The shares closed at a record $83.17 on Oct 20, then fell in three of the next four sessions to $72.98 on Oct 26, a drop of 12.3%, including a 4.0% fall on Oct 26 on 1.4 million shares. Kiniksa's only filing in that window named its chief operating officer as president. Part of today's move was that pre-earnings caution unwinding: measured from the Oct 20 record, the stock was up about 6%. After the move, RSI(14) stood at about 64, the shares sat about 13% above their 50-day average and about 49% above their 200-day average, and they traded within 0.2% of the 52-week high. More of the day's big moves are in today's biggest stock moves.
The numbers
What Kiniksa reported for the quarter ended Sept 30:
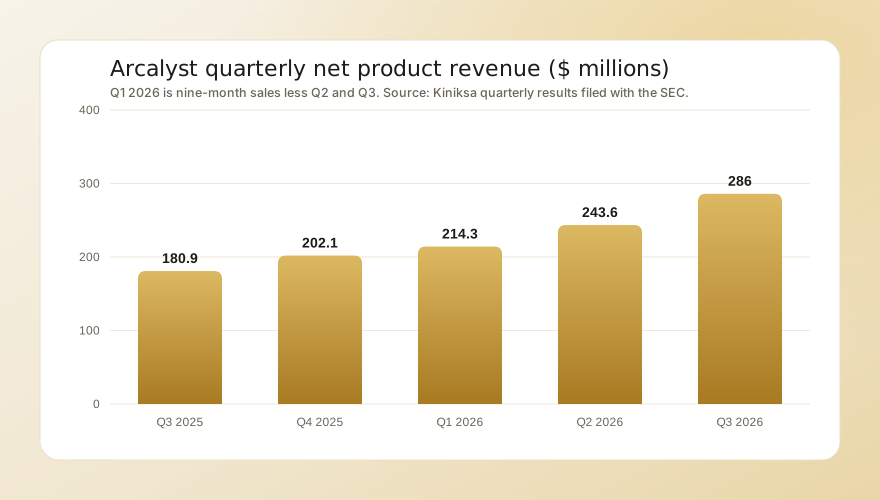
- Sales. Arcalyst net product revenue of $286.0 million, up 17% from $243.6 million in the second quarter and about 58% from a year earlier. Nine-month sales were $743.8 million, against $475.4 million a year earlier.
- Profit. Operating income of $54.2 million, against $24.0 million a year earlier. Net income was $47.3 million, or $0.56 a diluted share, against $18.4 million, or $0.23.
- Costs. Collaboration expenses, which the company says are driven mainly by Arcalyst's collaboration profitability, rose to $105.8 million from $63.3 million. Research spending rose to $32.8 million from $24.2 million on more KPL-387 trial work, and selling, general and administrative costs rose to $65.4 million from $49.1 million.
- Cash. $568.8 million of cash, cash equivalents and short-term investments at Sept 30, up from $525.9 million at June 30 and $414.1 million at the end of 2025, with no debt.
- Adoption. About 23% of the 14,000 patients a year with multiple recurrences were on Arcalyst, against about 21% at the end of June. More than 5,450 prescribers have written it, against more than 5,000 in July. Average total time on therapy was about three years.
The guidance tells the same story. Kiniksa has raised its 2026 Arcalyst range at every report this year:
| Date | 2026 Arcalyst sales guidance | Midpoint |
|---|---|---|
| Feb 24, 2026 | $900M to $920M | $910M |
| Apr 28, 2026 | $930M to $945M | $937.5M |
| Jul 28, 2026 | $980M to $995M | $987.5M |
| Oct 27, 2026 | $1,045M to $1,050M | $1,047.5M |
The midpoint is now 15% above where it started the year. Our guide to why guidance changes move stocks explains why a raised outlook often matters more than the quarter itself. Kiniksa also set 2026 research spending at $160 million to $170 million and selling, general and administrative costs at $270 million to $280 million.
The bull case
- Growth is not fading. Sales rose 17% from the second quarter alone. Years into its launch in this disease, the drug is still gaining share.
- Room to grow. With about 23% of eligible patients on treatment, most of the market is still untreated with Arcalyst, and patients stay on it for about three years.
- Estimates have to move. A quarter about $25 million above the average estimate and a higher full-year range push forecasts up; our page on earnings estimate revisions covers why that tends to support a stock after the first day.
- A next product in the same disease. KPL-387 targets once-monthly dosing in a liquid formulation, against weekly Arcalyst, and is in a pivotal trial of up to about 85 patients.
The risks
- Valuation. At $88.28 the market value is about $6.9 billion, more than 60 times trailing earnings and about 7 times trailing sales. That leaves less room for a soft quarter.
- One product. Arcalyst is all of Kiniksa's product revenue, and a large share of its profit is shared through collaboration expenses, which rose 67% from a year earlier, faster than sales.
- A long wait for new data. KPL-387 pivotal results are not due until the second half of 2027, and the trial is event-driven, so timing can move.
- The run-up. The stock was $35.20 at its 52-week low. A 150% rise from there means holders have large gains to protect.
What comes next
- KPL-1161 Phase 1 start, by the end of 2026. Kiniksa has kept this target since February.
- Fourth-quarter results, likely in late February 2027 (last year's came on Feb 24). The bar is about $301 million to $306 million of Arcalyst sales, implied by the new range; reading the release line by line is covered in our guide on how to read an earnings release.
- KPL-387 pivotal data, second half of 2027. Our explainer on regulatory approvals as catalysts covers how the steps after that data tend to move a stock.