

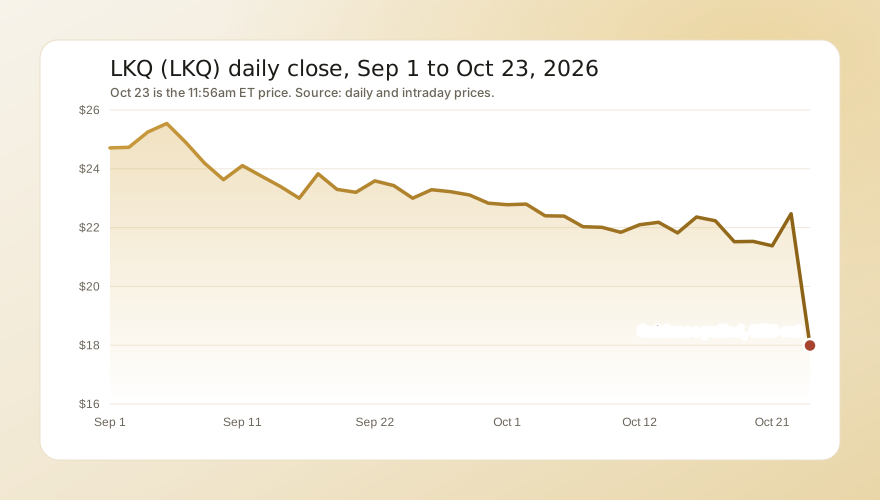
Oct 23, 2026: guidance pulled, CEO out, and a 20% drop at the open
LKQ released the news before the market opened. The stock traded at $21.78 at 8am, slid to $20.10 by 8:05am, and was $17.99 at 9:25am, down 19.9%. It opened at $18.08, fell to $17.21 in the first five minutes, a new 52-week low, and then held between $17.36 and $18.29 through the morning. At 11:56am it was $17.99 on 8.0 million shares, 2.4 times its 20-day average for a full day.
What pushed it down:
- The guidance is gone. LKQ withdrew its full-year 2026 outlook, last updated on July 30, citing the European results and the CEO change. It did not replace it with a new range.
- A loss where there was a profit. The company expects a third-quarter net loss from continuing operations of $16 million to $32 million, including $111 million of non-cash impairment charges, against net income of $178 million a year earlier.
- Two leaders out on the same day. CEO Justin Jude and Andy Hamilton, president of LKQ Europe, both left on Oct 23. Chairman John Mendel said results had "fallen significantly short of the Board's expectations."
- An adviser for Europe. The board hired Alvarez & Marsal to focus on customer service levels, operational stability and cost discipline in the region.
Other parts sellers fell far less:
| Stock or fund | Oct 22 close | Oct 23, 11:56am | Change |
|---|---|---|---|
| LKQ (LKQ) | $22.47 | $17.99 | -19.9% |
| Genuine Parts (GPC) | $127.97 | $122.40 | -4.4% |
| O'Reilly Automotive (ORLY) | $92.00 | $90.29 | -1.9% |
| AutoZone (AZO) | $3,270.70 | $3,210.64 | -1.8% |
| Advance Auto Parts (AAP) | $46.69 | $46.32 | -0.8% |
| S&P 500 fund (SPY) | $763.96 | $762.66 | -0.2% |
The US parts retailers barely moved, which fits LKQ's own account that North America was in line and the problem sits in Europe. Genuine Parts, which also sells in Europe, fell more than the others; we covered its own drop earlier in why Genuine Parts stock fell. More of the day's swings are in today's biggest stock moves.
After the drop, RSI(14) stood at 24, the shares sat 24% below their 50-day average and 35% below their 200-day average, and they were 52% below their 52-week high of $37.13.
What the preliminary numbers show
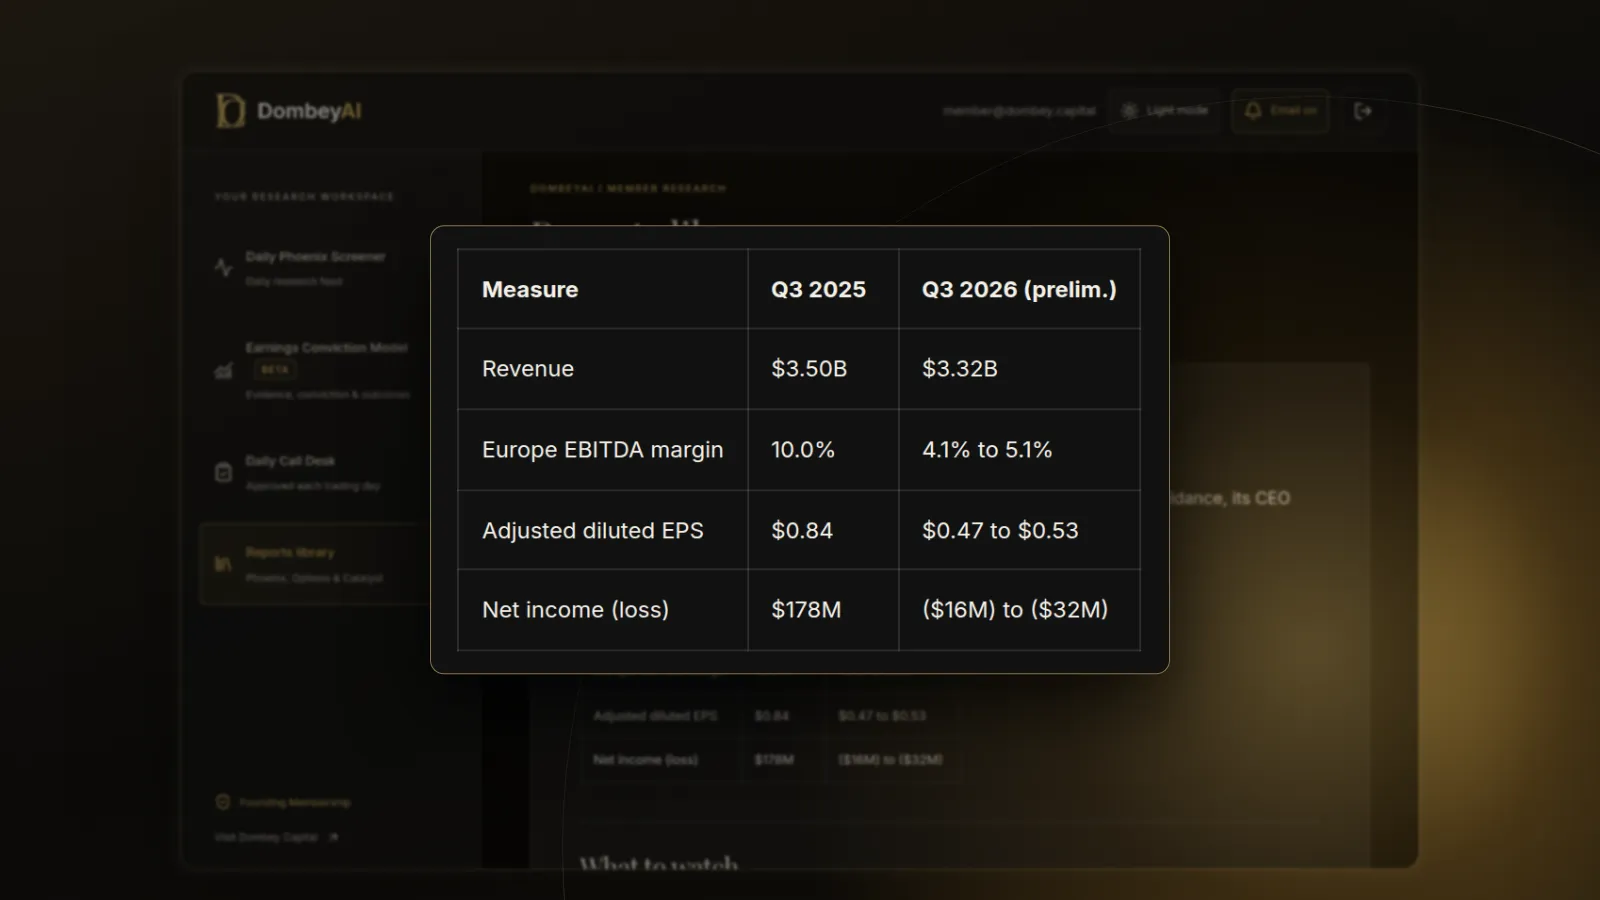
| Measure | Q3 2026 (preliminary) | Q3 2025 |
|---|---|---|
| Revenue | $3.32B | $3.50B |
| Organic parts and services revenue | -5.4% | n/a |
| Europe organic parts and services revenue | -9.8% | n/a |
| Europe segment EBITDA margin | 4.1% to 5.1% | 10.0% |
| Adjusted diluted EPS | $0.47 to $0.53 | $0.84 |
| Diluted EPS | loss of $0.06 to $0.12 | $0.69 |
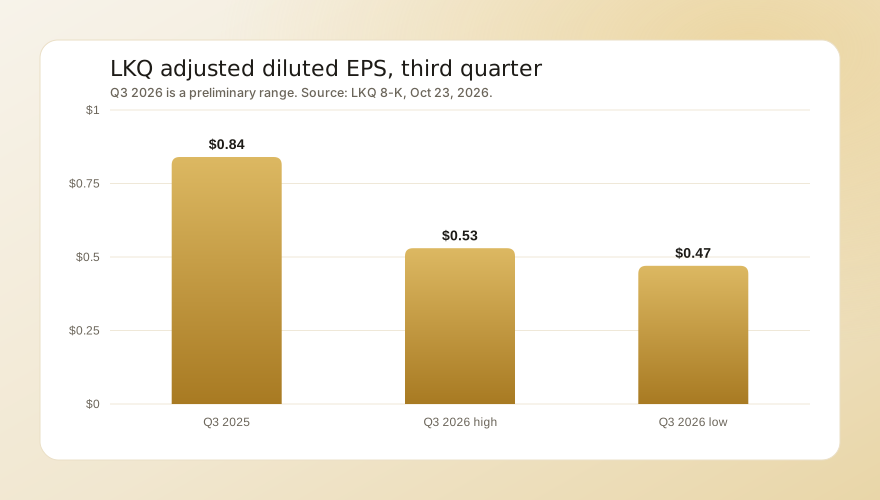
The impairment charges include $88 million of goodwill and $23 million on net assets held for sale. Our explainer on goodwill and impairments covers why a goodwill charge is a signal about past deals, even though it uses no cash. Specialty, the smallest segment, was "modestly below expectations." The release gave no cash flow, debt or buyback figures; those come on Oct 29.
The bull case
- North America held. The largest segment performed in line with the company's expectations despite softer market conditions, so the problem is concentrated in one region with a known cause.
- An ERP failure can be fixed. Disruption from a systems rollout is operational, not a loss of customers to a competitor, and Alvarez & Marsal's brief is service levels and stability.
- A sale is still possible. The board said its strategic review is ongoing. A sale of Europe or Specialty could cut debt and simplify the company; see what happens after a strategic review.
- The price is low against the old numbers. The consensus target before the news was about $31.30, and the stock trades at about seven times trailing EBITDA on an enterprise basis.
The risks
- No floor for estimates. With guidance withdrawn, analysts will cut 2026 and 2027 numbers without company help.
- Leverage rises as EBITDA falls. Net debt was about 3.9 times trailing EBITDA before this quarter. A halved European margin pushes that ratio higher; see what counts as high debt.
- The dividend is unaddressed. A 6.7% yield on a stock that just pulled guidance is a sign the market doubts the payout.
- A leadership gap. The new CEO starts on December 15, so the Oct 29 report will come from an interim office, and a new chief executive may reset expectations again once in the job.
- Europe may get worse before it improves. The release names volume declines in the UK and Benelux as well as Germany's ERP problem, and the first is a demand issue, not a systems one.
What comes next
- Full third-quarter results and the call on October 29. Watch for any fourth-quarter or 2027 framework, cash flow and net debt at Sept 30, and anything on the dividend. Our guide to preparing for an earnings report covers what tends to move a stock on the day.
- Analyst estimate and target cuts. These will come over the next week and show how far the Street thinks earnings fall.
- The strategic review. Any announced sale, and its price, would change the debt picture.
- December 15. Salvatore Abbate takes over as CEO.