

Nov 4, 2026: CTV beats and the outlook goes up again
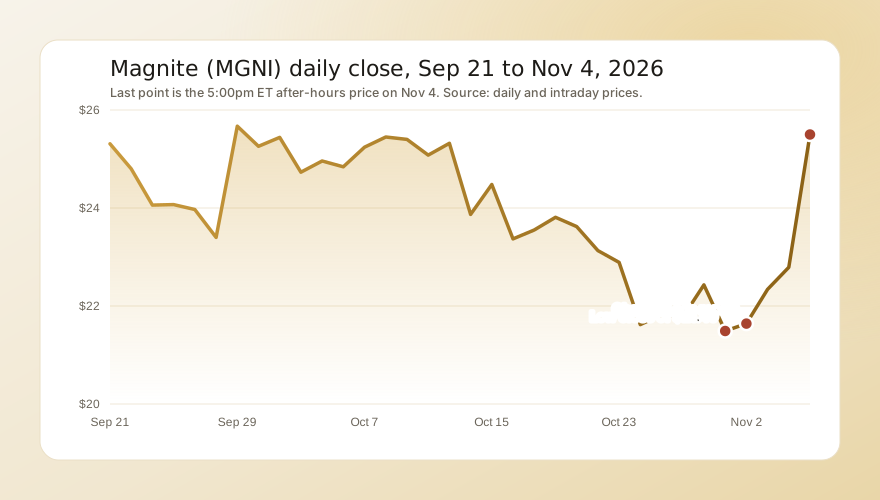
Magnite traded between $22.37 and $22.75 before the open, opened at $22.86, made its low of $22.60 at 9:30am and its high of $23.40 at 9:45am, then closed at $22.79, up 2.0%, on about 3.0 million shares. Ad tech peers were also higher in the regular session: PubMatic rose 1.3%, The Trade Desk 2.9% and DoubleVerify 1.4%, while AppLovin jumped ahead of its own report (see why AppLovin stock rose). The stock had been sliding for a month, from $25.45 on Oct 8 to a low close of $21.49 on Oct 30.
Two days before the report, on Nov 2, The Information reported that OpenAI had reached unannounced agreements with Magnite and PubMatic to fill unused ad space in ChatGPT, Investing.com reported. Magnite traded up 5% that morning but closed up only 0.7%, and the volumes were described as modest. The release itself did not mention OpenAI.
The results came out at 4:05pm, with a call at 4:30pm. The first trades after the release were near $24.84, and by 4:09pm the stock touched $27.27. What moved it:
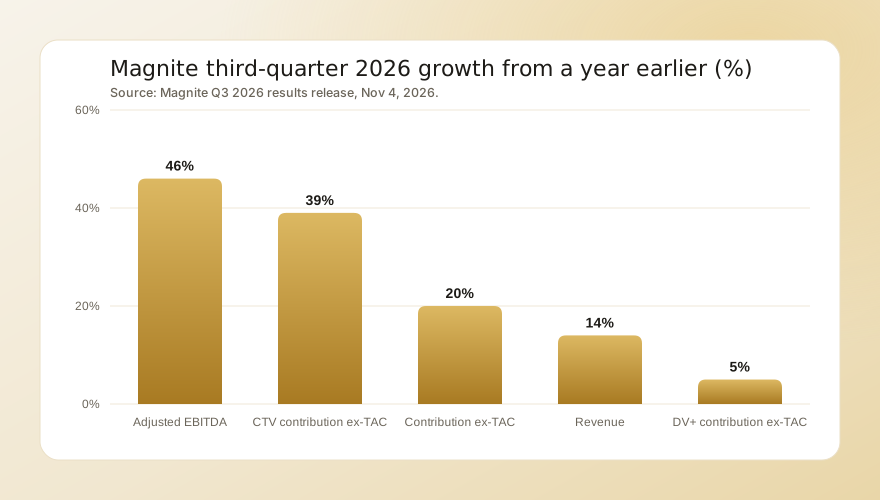
- The beat was large. Contribution ex-TAC of $200.6 million was $8.6 million above the top of the guide. B. Riley, which rates the stock a buy with a $30 target, had modeled $190.0 million.
- CTV sped up. CTV contribution ex-TAC grew 39%, faster than the 36% of the second quarter, and is now 53% of the total. Chief executive Michael Barrett said political spending outperformed, "mostly in CTV."
- Margins jumped. Adjusted EBITDA of $83.4 million compared with $57.2 million a year earlier and about $70.0 million in B. Riley's model.
- The year and next year both went up. The full-year guide rose to about 17% contribution ex-TAC growth and about 30% adjusted EBITDA growth, and free cash flow growth is now expected above 60%, from the high 40% range.
At the regular close, RSI(14) stood at 47, the shares sat 4.6% below their 50-day average and 28.7% above their 200-day average, volume was 1.6 times its 20-day average, and the stock was 15.1% below its 52-week high. The rest of the session's movers are in today's biggest stock moves.
The numbers
| Measure | Q3 2026 | Q3 guide | Change from a year earlier |
|---|---|---|---|
| Contribution ex-TAC | $200.6 million | $188-192 million | +20% |
| CTV contribution ex-TAC | $105.4 million | $98-100 million | +39% |
| DV+ contribution ex-TAC | $95.3 million | $90-92 million | +5% |
| Revenue | $204.2 million | none | +14% |
| Adjusted EBITDA | $83.4 million | none | +46% |
| Non-GAAP EPS | $0.33 | none | from $0.20 |
Net income rose 70% to $34.0 million, or $0.23 a diluted share, and operating cash flow was $68.0 million. Magnite ended September with $392.9 million of cash and $349.9 million of debt, after repaying $205.1 million of convertible notes this year, and it bought back $55.6 million of stock in the first nine months. Our explainer on adjusted EBITDA covers what the adjusted figure leaves out, and our page on buybacks as catalysts covers when repurchases matter to a stock.
For the fourth quarter Magnite expects contribution ex-TAC of $227 million to $233 million, including $124 million to $127 million from CTV and $103 million to $106 million from DV+, with adjusted EBITDA operating expenses of $125 million to $127 million. Our guide to guidance changes explains why a second raise in a row can move a stock more than the quarter itself.
The bull case
Magnite is the largest independent sell-side ad platform, and CTV is where the growth is. A business growing near 40% now makes up more than half of contribution ex-TAC, which pulls the whole company's growth rate up each quarter even if DV+ stays slow. The 2027 outlook matters most here: management expects growth excluding political to be faster than in 2026, before any lift from the court-ordered remedies in Google's ad tech case, which analysts have cited as an opening for independent platforms. The ChatGPT ad deal is small today but adds a new buyer channel.
The valuation was modest going in. Before the report the forward P/E was about 18.4, 13 of 15 analysts rated the stock a buy, and the average target stood at $28, above even the after-hours high. Our page on post-earnings announcement drift covers why stocks that gap up on a clear change in guidance often keep moving the same way, and our guide to earnings estimate revisions covers why raised targets tend to follow a beat like this.
The risks
Political advertising inflated 2026. Management now expects political spending to be nearly three times its initial forecast, and that money does not come back in an off year, which is why the reported 2027 growth outlook is about 10% against over 15% on an underlying basis. DV+ grew 5%, so the non-CTV half of the business remains slow.
The buy side is a risk too. The Trade Desk, the largest independent demand-side platform, closed Nov 4 at $13.23, and a weaker partner on the other side of the trade can mean tougher pricing. The Google remedies are a court process with no fixed timing, and the after-hours move faded from $27.27 at 4:09pm to $25.50 by 5:00pm, a sign that some holders used the jump to sell near the old high.
What comes next
The fourth-quarter report is expected around February 25, 2027, with the full 2027 guide. Before then, watch whether the stock holds above the $22.79 close it gapped from, whether analysts raise targets above the current $25 to $32 range, and any figures on ChatGPT ad volumes. A close back below $22.79 would undercut the Bullish case.