

Nov 3, 2026: an in-line quarter and a weaker 2027
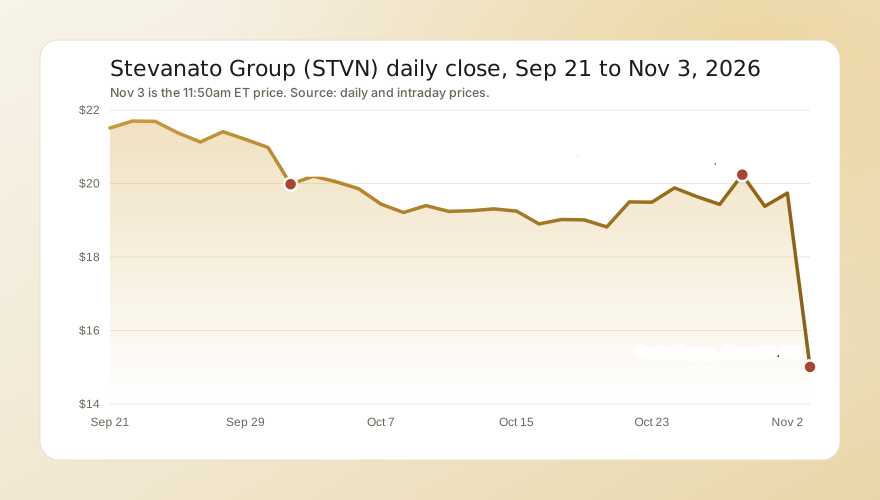
Stevanato closed Nov 2 at $19.74. Premarket trading ranged from $17.00 to $19.67 after the release, and the selling came at the open. The stock opened at $15.94, which was also the high of the regular session, and touched $13.03 at 9:30am. By 11:50am it was $15.01, down 24.0%, on about 6.1 million shares, about 15 times its three-month daily average of roughly 394,000 shares.
What moved the stock:
- GLP-1 volumes will be lower next year. GLP-1 therapies were about 17% to 18% of third-quarter revenue. The company said it now expects lower GLP-1 volumes and revenue in 2027 than it had planned, which "will temporarily moderate growth," and that it remains confident it can grow low single digits based on what it knows today.
- Orders came in short. Management said order intake improved during the quarter but ended below its targets for signed orders, IBTimes reported, which leaves less visibility into 2027.
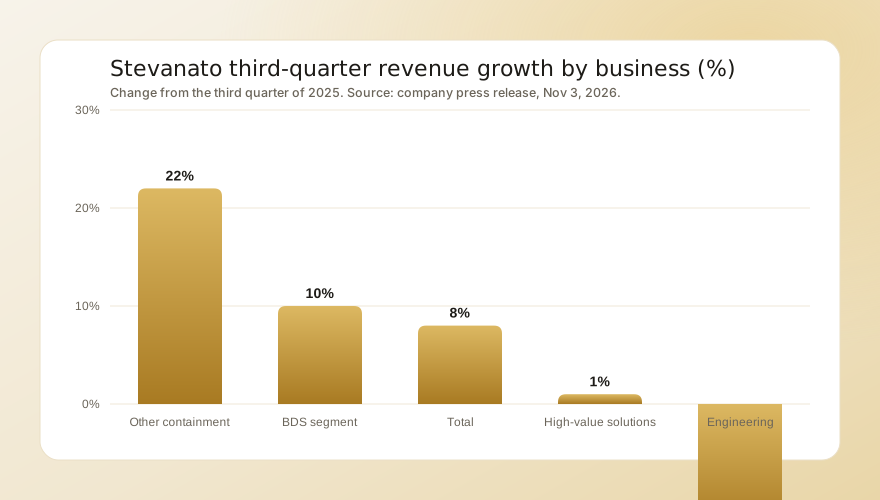
- The profit engine slowed. High-value solutions, mainly EZ-fill syringes and cartridges, grew 1% to 149.4 million euros, or 46% of revenue. The faster growth came from bulk syringes and cartridges, up 22%, and part of that was variable compensation tied to lower GLP-1 volumes, payments that will not repeat at the same level.
- Peers barely moved. West Pharmaceutical was up 1.0% and Becton Dickinson down 0.1% late in the morning, and the health care sector fund was up 0.4%, so the drop was about Stevanato's own outlook.
At 11:50am RSI(14) was 23, deep in oversold territory, and the stock sat 21.9% below its 20-day average, 26.6% below its 50-day average of $20.37 and 17.2% below its 200-day average of $18.07.
The numbers
| Measure | Q3 2026 | Change from a year earlier |
|---|---|---|
| Revenue | 326.1 million euros | +8% |
| High-value solutions revenue | 149.4 million euros | +1% |
| Other containment and delivery revenue | 144.6 million euros | +22% |
| Engineering segment revenue | 32.0 million euros | -12% |
| Adjusted EBITDA | 88.8 million euros | +14% |
| Adjusted EBITDA margin | 27.2% | +1.5 points |
| Adjusted diluted EPS | 0.16 euros | from 0.14 euros |
The quarter was not the problem. Gross margin slipped 0.1 point to 29.1% on higher utility costs and depreciation, but operating margin rose 1.1 points to 18.5%, and net profit rose 16% to 41.8 million euros. Operating cash flow was 57.6 million euros and capital spending was 44.8 million euros, mostly for the new plants in Latina, Italy, and Fishers, Indiana, and for device programs in Germany. Free cash flow was 21.7 million euros. Cash was 114.9 million euros and net debt 353.7 million euros at Sep 30.
The 2026 guidance stands at 1.260 billion to 1.280 billion euros of revenue, adjusted EBITDA of 335.0 million to 345.2 million euros and adjusted diluted earnings per share of 0.60 to 0.62 euros. At $15.01 and a dollar near 1.16 to the euro, the stock trades at about 21 times the midpoint of that earnings guide. Our guide to why guidance changes move stocks explains why a soft outlook for next year can outweigh a clean quarter, and the rest of the session's movers are in today's biggest stock moves.
The bull case
The underlying demand for injectable biologics is not in question. Non-GLP-1 biologics grew more than 30% in the quarter, biosimilars and self-injected drugs keep adding volume, and Stevanato is one of a small number of suppliers that can make ready-to-fill syringes and cartridges at scale. Margins kept improving even as the GLP-1 business slowed, because the Latina and Fishers plants are filling and running more efficiently.
The reset is also large. The stock fell from $19.74 to as low as $13.03 in one morning and is now 44% below its $27 52-week high. The average analyst price target before the report was $25.58, with a low of $17.50, so the Street will have to cut targets, but even the lowest target sat well above today's price. If 2027 turns out better than low single digits, today's price leaves room for it.
The risks
The bigger risk is that "low single digits" is a starting point, not a floor. The company gave that figure based on "what we know today," orders are behind plan, and GLP-1 makers have already cut volume expectations once. Stevanato is still spending heavily on new capacity, and capacity that is built for GLP-1 demand needs other customers to fill it.
The second risk is the multiple. Before today the stock traded at about 35 times trailing earnings. Even after the drop it trades at about 21 times this year's guidance, which is a growth multiple for a business that has just guided to slow growth. Our page on forward versus trailing P/E shows why a cut to next year's estimates can push a forward multiple up even after a large price drop. Engineering is a third, smaller risk: the segment's margin is 10.2% and management called its results below expectations.
What comes next
The next dated event is the fourth-quarter report early next year, when the company is expected to give formal 2027 guidance; it has not set a date. Before then, watch three things: analyst estimate cuts in the next two weeks, which our guide to earnings estimate revisions explains, any announcement of large new biologics or device orders, and whether the stock holds the $12.89 52-week low. Stevanato files as a foreign private issuer, so its quarterly numbers arrive on a 6-K and its annual report on a Form 20-F rather than a 10-K.
Moves like this one often keep drifting for weeks as estimates catch up, a pattern our page on post-earnings announcement drift describes, and that is the main reason our view stays Bearish after a 24% fall.