

Oct 30, 2026: a gap down on the fourth-quarter guide
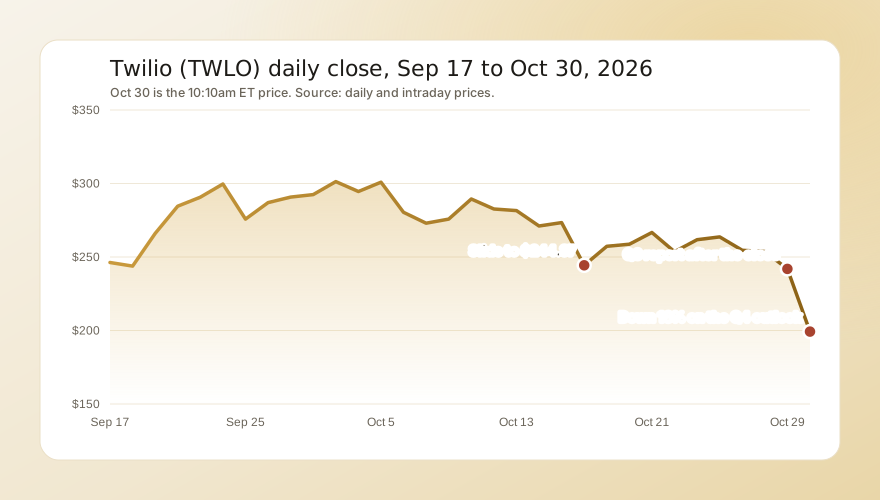
Twilio closed at $241.90 on Oct 29, down 4.7% on the day, and reported after the close. Premarket trading ran from $203.50 at 4am to a low of $189.99 at 9:10am. It opened at $186.59, fell to $180.00 by 9:35am, down 25.6% from the close, then rose as the group steadied. It was $199.24 at 10:10am on 2.5 million shares, 0.6 times its 20-day average with the session still young.
What happened:
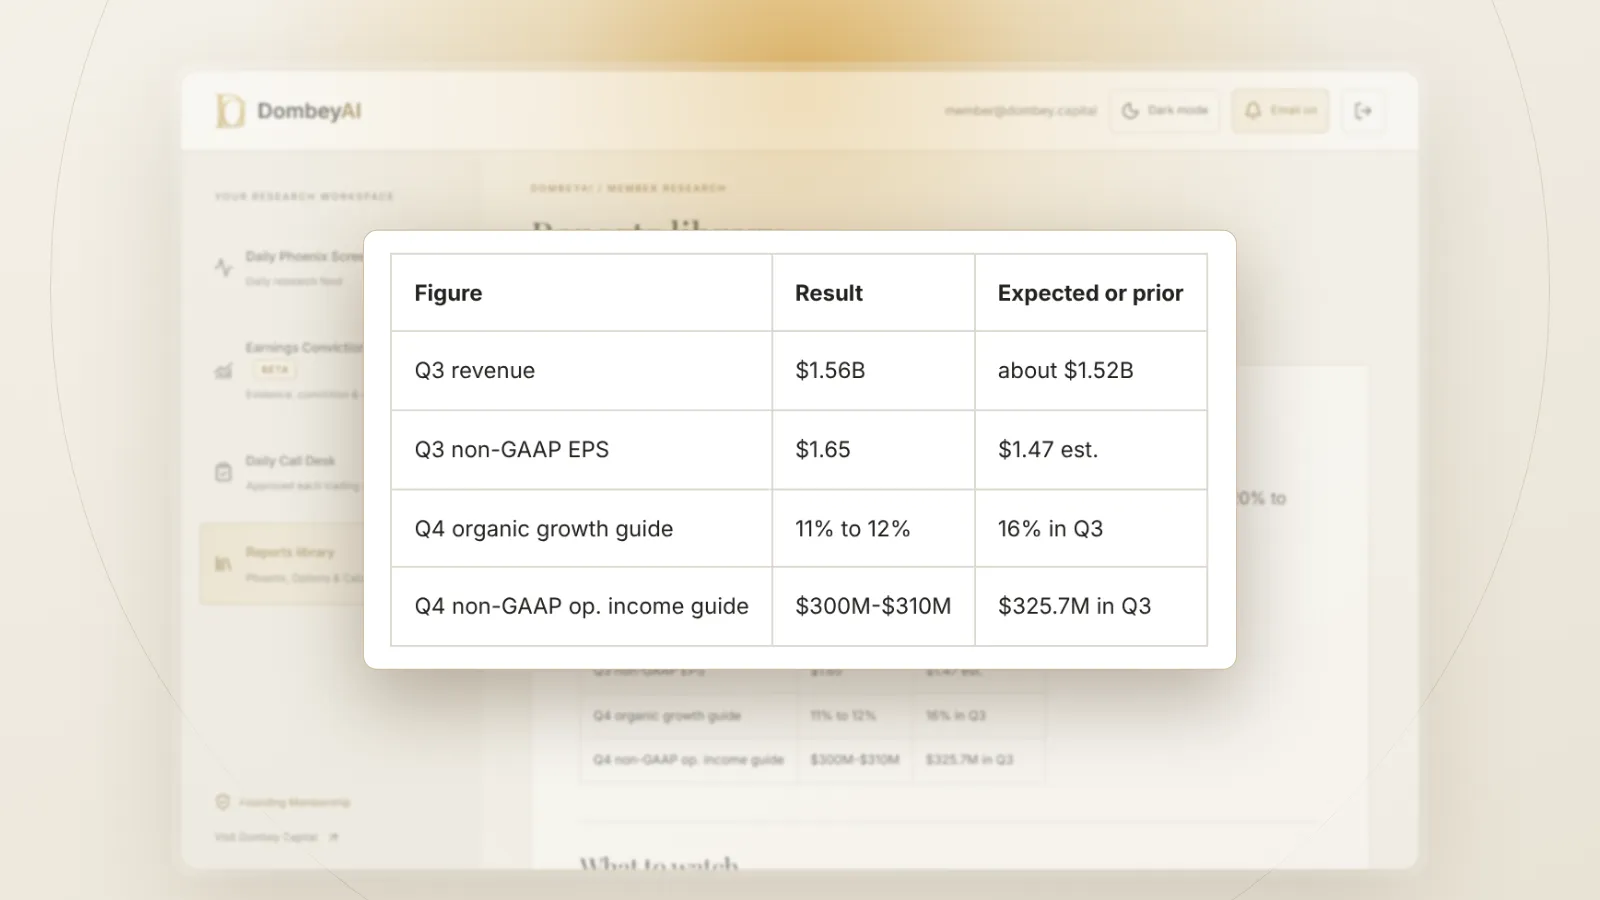
- The quarter beat. Revenue was $1,559.5 million, up 20% reported and 16% organic. Non-GAAP income from operations rose 39% to $325.7 million, a 21% margin against 18% a year earlier. Free cash flow was $369.6 million, a 24% margin, and the dollar-based net expansion rate was 114% against 109% a year ago, according to the company's results release.
- The guide slows. For the fourth quarter Twilio guided revenue to $1.595 billion to $1.605 billion, which implies 17% to 17.5% reported growth but only 11% to 12% organic growth. It guided non-GAAP income from operations to $300 million to $310 million and non-GAAP earnings to $1.48 to $1.53 a share, against $1.65 in the third quarter.
- The year was raised. It lifted 2026 organic growth to 15% from 13% to 13.5%, reported growth to 20% from 18% to 18.5%, and non-GAAP income from operations to $1.19 billion to $1.20 billion from $1.135 billion to $1.155 billion.
- The slowdown carries into next year. Investing.com reported that Twilio expects 2027 organic growth of at least 10%, below the 15% now expected for 2026.
- The core line slowed. Messaging, about 59% of revenue, grew 17% organic in the third quarter, down a point from the second, per the call coverage. Analysts pressed management on why the fourth-quarter organic guide looks so similar to the third-quarter guide and whether first-half tailwinds had faded.
From the Oct 29 close, at 10:10am:
| Stock or fund | Oct 29 close | Oct 30, 10:10am | Change |
|---|---|---|---|
| Twilio (TWLO) | $241.90 | $199.24 | -17.6% |
| Fastly (FSLY) | $25.64 | $23.59 | -8.0% |
| Datadog (DDOG) | $265.84 | $244.95 | -7.9% |
| Bandwidth (BAND) | $53.11 | $49.04 | -7.7% |
| Cloudflare (NET) | $310.30 | $288.07 | -7.2% |
| Zoom (ZM) | $97.66 | $97.02 | -0.7% |
| Software fund (IGV) | $107.97 | $106.02 | -1.8% |
| Invesco QQQ (QQQ) | $715.34 | $696.81 | -2.6% |
Twilio fell about 10 times as far as the software fund and more than twice as far as any close peer in the table. Software and cloud names were weak across the board, with Fastly, Datadog, Bandwidth and Cloudflare all down 7% to 8%, so part of the move is the group. Our look at Fastly's earlier fall and Datadog's rise shows how differently the market has treated these names on their own results. More of the day's swings are in today's biggest stock moves.
After the drop, RSI(14) stood at 29, the shares sat 23% below their 50-day average and 5% above their 200-day average, and the stock was 36% below its 52-week high of $308.40. This is context, not a signal.
What the numbers say
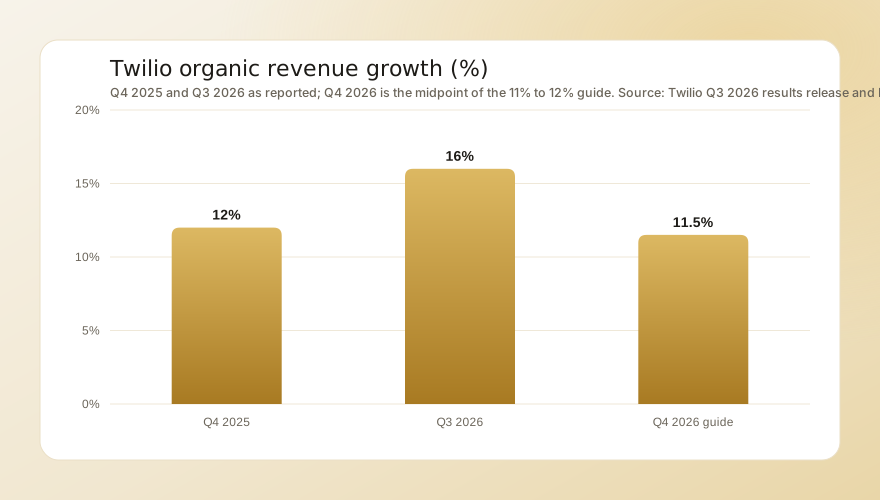
Reported growth of 20% flatters the picture, because $53.1 million of third-quarter revenue came from U.S. carrier fees that Twilio passes through at cost. Strip those out, plus $1.8 million from an acquisition, and organic revenue was $1,504.6 million, up 16%. That 16% was up from 12% in the fourth quarter of 2025, so the third quarter was a high-water mark, and the fourth-quarter guide of 11% to 12% takes growth back to last year's pace. Our guide to why outlooks move stocks explains why the direction of a guide can outweigh the size of a beat.
Profit is the second worry. Non-GAAP gross margin was 49% against 50% a year earlier, and the Q4 operating income guide of $300 million to $310 million is $16 million to $26 million below the third quarter even though revenue keeps rising. The CFO pointed to higher hosting costs in the holiday season and the end of some cost tailwinds, Investing.com reported.
At $199.24 the market value is about $30.6 billion. Annualizing the midpoint of the fourth-quarter earnings guide of $1.505 gives about $6.02 a share, which puts the stock near 33 times. Our explainer on forward and trailing P/E shows how much that depends on which year you trust.
The bull case
- The beat was broad. Revenue, earnings, operating margin, free cash flow and net expansion all improved from a year ago, and the 114% net expansion rate means existing customers are still spending more.
- The year was raised, not cut. Organic growth for 2026 went to 15% from 13% to 13.5%, and operating income guidance rose by about $50 million at the midpoint.
- Cash is plentiful. Free cash flow was $369.6 million in a quarter. Twilio bought back $127.2 million of stock in the third quarter and has about $700 million left on its authorization through 2027.
- The drop came on top of a slide. The stock fell 10.6% on Oct 16 with no company news, and it has now lost 35% from its high. The consensus target in the data we checked was $262.88, with a low of $192, though those figures may not reflect today's cuts.
- The bar is now lower. The CFO said Twilio has delivered nine consecutive quarters of double-digit organic growth, and the guide only asks for 11% to 12% in the fourth.
The risks
- A step down in growth. Organic growth falls four to five points in a quarter, and 2027 is guided to at least 10%, so the market may be repricing Twilio from a re-accelerating story to a mature one. Our piece on earnings estimate revisions covers how cuts can keep pressure on a stock after day one.
- Messaging is slowing. The business that makes up more than half of revenue grew a point slower, and analysts asked directly whether it is moderating.
- Margins are pointed the wrong way. Gross margin slipped, and fourth-quarter operating income is guided below the third.
- The valuation is not low. About 33 times annualized earnings leaves little room if the 11% to 12% is missed.
- A gap this size can extend. Our note on base rates covers why a sharp first-day drop says little about the next month.
What comes next
The next dated checkpoint is the end of the fourth quarter on December 31, 2026, with results to follow. Twilio has not announced a date in the sources we checked. Before then, watch the analyst target cuts that follow a guide like this, whether the rest of the software group steadies, and any sign that messaging growth is holding at 17%. The test of the Bullish view is whether fourth-quarter organic growth lands at or above 11% with operating income at or above $300 million.