

Oct 16, 2026: a slow open, then a steady climb on the beat
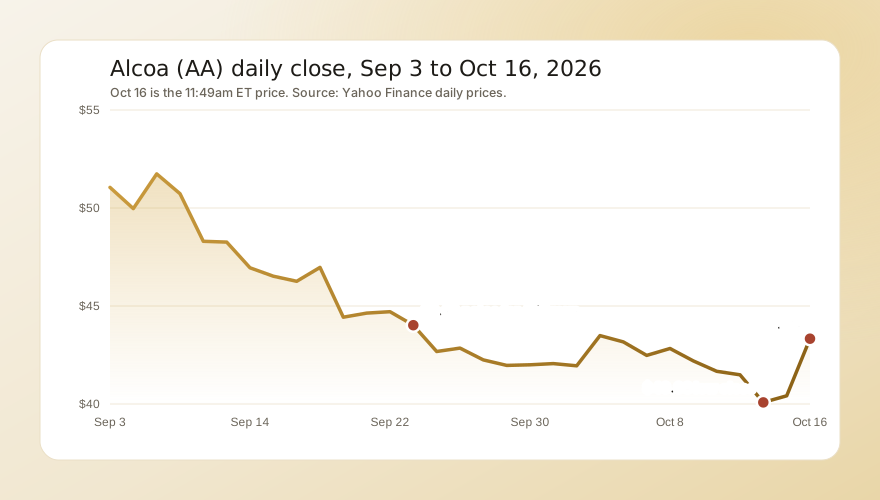
Alcoa reported after the close on Oct 15, and shares rose about 2.5% in after-hours trading, according to Investing.com. Premarket trade was thin, between $41.03 and $41.85. The stock opened at $41.17, which was also the day's low, and was up just 1.9% at $41.27 at 9:51am ET, Schaeffer's reported. Buying picked up through the morning. The shares reached $44.34 around 11:00am ET, about 9.7% above the prior close, and traded at $43.33 at 11:49am ET.
What pushed it up:
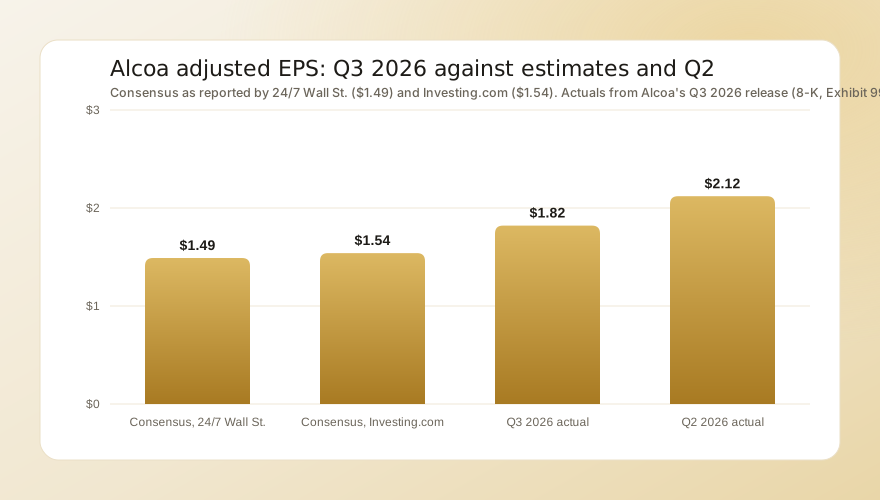
- An earnings beat. Adjusted EPS of $1.82 beat the $1.49 consensus cited by 24/7 Wall St. and the $1.54 cited by Investing.com. GAAP net income was $483 million, or $1.81 a share, up from $232 million a year earlier.
- A data center sale. Alcoa signed definitive agreements to sell portions of the Massena East site. It expects $50 million to $65 million at closing, which it expects within six months, and $60 million to $250 million more as the buyer builds approved data center capacity over seven years. CEO William Oplinger called it "the first transaction supporting our target to generate $500 million to $1 billion from asset monetization by 2030."
- A shareholder vote. South32 shareholders approved the AliGroup sale on Oct 15. Alcoa has already raised $2.6 billion of senior notes to pay most of the $3.1 billion cash price and still expects to close in the first half of 2027.
- A low starting point. The stock closed at $40.08 on Oct 14, its lowest close in the period shown, and Schaeffer's noted it had tested $40 this week. Barclays started coverage at Overweight with a $55 target on Oct 14, according to Goldesel, arguing that weaker aluminum expectations were largely priced in.
The group helped a little. Century Aluminum (CENX) rose 5.7% and Constellium (CSTM) 2.3%, while Kaiser Aluminum (KALU) gained 1.7% and the SPDR S&P Metals and Mining ETF (XME) 1.5% by late morning. Century's gain suggests part of the move was a sympathy bid for U.S. smelters, but Alcoa's rise was larger than every peer's, and only Alcoa had results and a deal to report.
By late morning, RSI stood at 49, the shares sat 7.5% below their 50-day average and 24.5% below their 200-day average, volume ran 1.5 times its 20-day average, and the stock was 48.5% below its 52-week high of $84.38, based on Yahoo Finance daily prices.
The numbers
Adjusted EPS beat estimates by a wide margin, but it was lower than the second quarter.
| Measure | Q3 2025 | Q2 2026 | Q3 2026 |
|---|---|---|---|
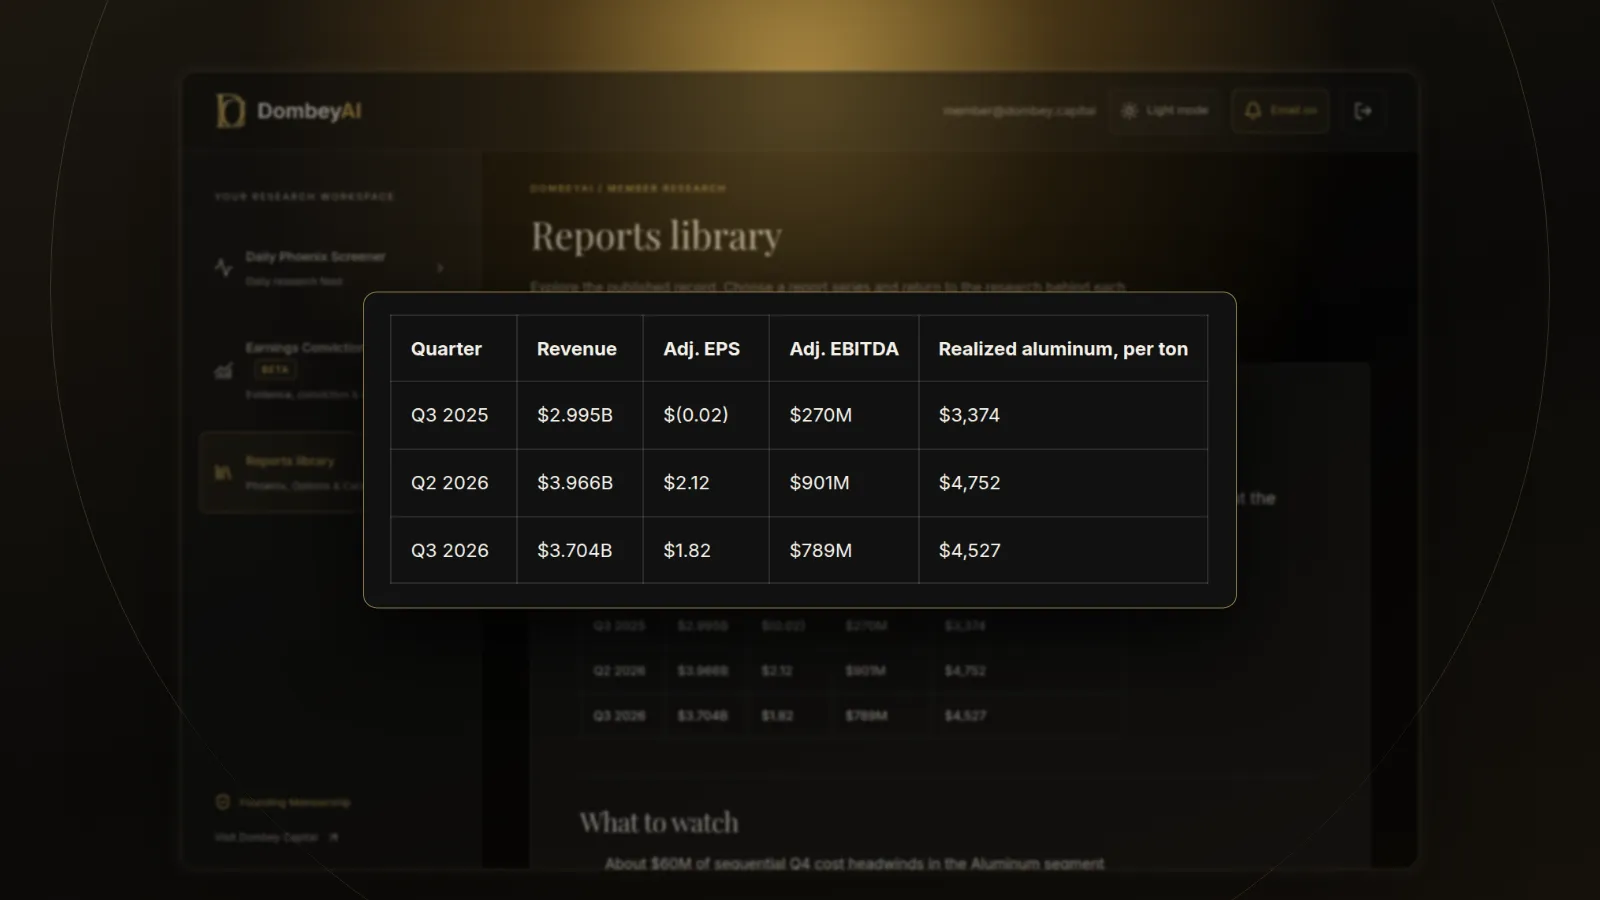
| Revenue | $2.995B | $3.966B | $3.704B |
| Adjusted EPS | $(0.02) | $2.12 | $1.82 |
| Adjusted EBITDA | $270M | $901M | $789M |
| Realized aluminum price, per ton | $3,374 | $4,752 | $4,527 |
| Realized alumina price, per ton | $377 | $334 | $353 |
The two segments moved in opposite directions. Alumina segment adjusted EBITDA improved by $95 million to a $1 million loss, on higher prices and an 11% rise in alumina output to 2.5 million metric tons as the Pinjarra refinery in Australia stabilized. Aluminum segment EBITDA fell to $862 million from $1.07 billion on lower metal prices, lower shipments and higher carbon costs. Aluminum shipments fell 5% to 693,000 tons, which CFO Molly Beerman said reflected the second quarter's one-time sale of about 30,000 tons of repositioned inventory.
Cash flow was solid. Cash from operations was $643 million and free cash flow was $472 million. Cash reached $4.4 billion, including the $2.6 billion of new notes, against $4.82 billion of long-term debt. Alcoa kept its 2026 guidance of 9.5 to 9.6 million tons of alumina and 2.4 to 2.6 million tons of aluminum.
The case for the stock
- It is cheap on earnings. FinViz shows a forward P/E of 7.39, a price-to-sales ratio of 0.78 and a price-to-book ratio of 1.56. Our explainer on forward and trailing P/E covers why a forward multiple this low can signal either value or expected earnings declines.
- Alumina is tightening outside China. Oplinger said the Alumina Price Index rose to about $370 a ton in the quarter and that the company expects "further tightening in the fourth quarter and into 2027." He said the price was $387 at the time of the call and that higher prices are not in the flat guidance: "if prices get better during the course of the quarter... it will flow through."
- The metal market is still short. Management said global aluminum inventories sit at about 42 days of consumption, and that "most products are sold out or tightly committed."
- Cash is coming. Beerman expects working capital to release at least 10 days in the fourth quarter, and Oplinger said two more asset sales "could happen quickly" after Massena East. For how these deals can change a valuation, see asset sales and divestitures.
- Analysts see upside. Financial Modeling Prep shows a consensus price target of $60.17, with a range of $53 to $70.
The risks
- Higher fourth-quarter costs. The release expects higher raw material costs and planned maintenance to cut Aluminum segment EBITDA by about $30 million sequentially, and alumina costs in that segment to add another $30 million. Beerman said about $10 million of the first figure is carbon. Our guide to guidance changes explains why a cautious outlook can outweigh a beat.
- Mine approvals are late. "The mining approvals are taking longer than expected," Oplinger said, and the process now runs into 2027. Alcoa has added six months of mining in current areas, but he said that beyond that, "we'll have to make some harder decisions."
- Aluminum prices are off their highs. The realized price fell 5% from the second quarter. Oplinger expects about 1.5 million tons of new smelting capacity in Indonesia in 2027, which he called material on a 75 million ton market. Analysts also asked about a possible U.S. tariff carve-out for Canadian metal. Oplinger said the Midwest premium should stay strong even then, but called it speculation.
- Leverage rises with AliGroup. Alcoa expects pro forma leverage of about 1.5 times after closing and says debt reduction, not buybacks, will come first. Interest expense guidance rose to about $185 million for 2026.
- The trend is down. Even after Oct 16, the shares are 48% below their June high and down about 18% this year, per FinViz.
What comes next
- Fourth-quarter results in January 2027. Watch Aluminum segment EBITDA against the third quarter's $862 million and whether the cost headwinds land at the guided $60 million. Our guide to preparing for an earnings report explains what moves a stock on the day.
- Alumina prices. Higher prices flow straight into the Alumina segment, which guided flat on performance alone.
- Massena East closing. Alcoa expects it within six months. The size of approved capacity, from 180 megawatts up to 635 megawatts, sets how much of the $315 million arrives.
- AliGroup approvals. Oplinger said about a dozen regulatory approvals are needed and that he sees no red flags. Closing is targeted for the first half of 2027.
- Western Australia mining approvals, which management now expects by mid-2027.