

The price-to-sales formula
There are two equivalent ways to calculate it.
Price-to-sales = market capitalization / trailing twelve months revenue
Price-to-sales = share price / revenue per share
Revenue per share is trailing revenue divided by diluted shares outstanding. Use the same share count on both sides and the two methods agree.
A few practical points:
- Use trailing twelve months (TTM). Add the last four reported quarters. A single fiscal year can be more than nine months stale.
- Use net revenue. The SEC's guide to financial statements describes net revenue as sales after returns and allowances. That is the figure on the top line of most income statements.
- Use diluted shares. Options, convertible bonds and restricted stock all add to the share count. Ignoring them understates the market value you are paying.
- Check for portfolio changes. If the company bought or sold a business during the year, TTM revenue may not reflect what it owns today. The segment note and acquisitions note tell you.
P/S vs EV/sales
Revenue supports every claim on a business. Lenders get paid out of it before shareholders do. So comparing the equity value alone with total revenue mixes two different things.
EV/sales = enterprise value / trailing twelve months revenue
Enterprise value is market cap plus debt, preferred stock and minority interest, minus cash. The difference matters most at the extremes.
A company with a $100 million market cap, $300 million of debt and $400 million of revenue has a P/S of 0.25. That looks very cheap. Its EV/sales is 1.0, which may not be cheap at all. The debt holders have first claim on whatever profit those sales produce.
The reverse also happens. A company with a lot of cash can have an EV/sales well below its P/S. If cash covers most of the market cap, the market is valuing the operating business, and its sales, close to nothing. Our guide on how to calculate enterprise value walks through each adjustment.
Quick reference
| Measure | Formula | Best used for | Main weakness |
|---|---|---|---|
| Price-to-sales (P/S) | Market cap / TTM revenue | Loss-making or depressed-earnings companies | Ignores debt and margins |
| EV/sales | Enterprise value / TTM revenue | Comparing companies with different balance sheets | Ignores margins |
| Gross margin | Gross profit / revenue | Testing whether sales can ever be profitable | Varies by cost accounting choices |
| Operating margin | Operating income / revenue | Converting P/S into an implied P/E | Distorted by one-off charges |
| EV/EBIT | Enterprise value / operating income | Checking that cheap sales also earn | Meaningless when EBIT is negative |
Why margins decide what cheap sales are worth
Revenue is not profit. A dollar of sales is worth what the company keeps from it. That is why P/S and margin have to be read together.
The link is simple. If a company earns a net margin of m on its sales, then:
P/E = P/S / net margin
A company at 0.5 times sales with a 5% net margin is on 10 times earnings. The same 0.5 times sales with a 1% margin is 50 times earnings. With a negative margin, there are no earnings at all.
So the useful question is not "is P/S low?" but "what P/E does this P/S imply if margins recover to a normal level?" To answer it you need two things:
- A normal margin for this business. Look at the company's own history across a full cycle and at peers with similar products. Gross margin tells you whether the core product is profitable. Operating margin tells you whether the cost base fits the revenue.
- A reason to believe the margin will get there. Margin recovery needs a mechanism: input costs falling, a restructuring removing overhead, a loss-making unit being sold or closed, or prices rising.
Comparing P/S across industries
P/S ratios differ widely by industry because margins do. A grocery chain may keep two or three cents of each sales dollar as profit. A software company may keep twenty or more. Grocers therefore trade at low multiples of sales and software companies at high ones, and neither tells you which is cheaper.
Some rules for comparison:
- Compare within an industry. Use peers that sell similar products to similar customers.
- Compare with the company's own history. A P/S far below the company's range over a full cycle is more interesting than a P/S below an unrelated sector.
- Adjust for revenue quality. Recurring contract revenue usually deserves a higher multiple than one-time project revenue. Pass-through revenue, where the company resells goods at a thin markup, inflates sales without adding much profit.
- Watch the revenue trend. A P/S on falling sales gets more expensive each quarter even if the price does not move.
Worked example
The following companies and numbers are illustrative only.
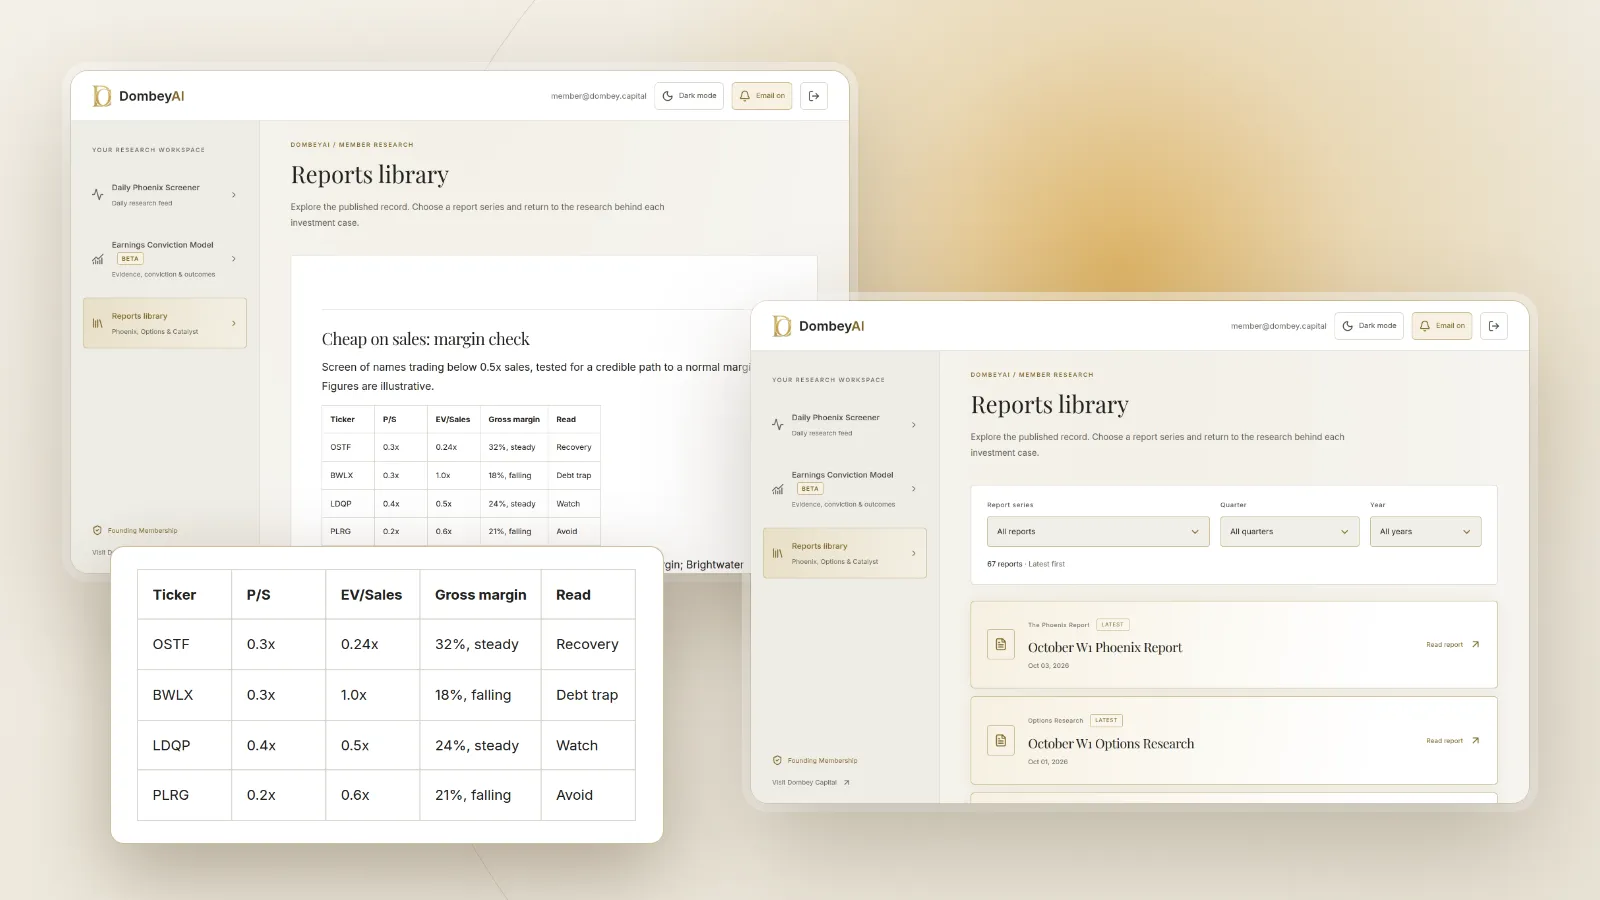
Company A and Company B each have a market cap of $150 million and TTM revenue of $500 million, so both trade at a P/S of 0.3.
Company A
- Net debt: none; $30 million of net cash
- EV/sales: 0.24
- Gross margin: 32%, steady for five years
- Operating margin: negative 2% this year, against 6% to 8% historically
- Reason for the drop: a one-year freight cost spike and a loss-making division the company has agreed to sell
Company B
- Net debt: $350 million
- EV/sales: 1.0
- Gross margin: 18%, down from 26% three years ago
- Operating margin: 1%
- Reason: a competitor has cut prices, and revenue has fallen 6% a year
On P/S alone, the two look the same. Underneath, they are not.
If Company A returns to a 7% operating margin on $500 million of sales, operating income is $35 million. Against an enterprise value of $120 million, that is about 3.4 times EV/EBIT. The low P/S reflects a temporary problem with a dated fix: the division sale.
Company B has no such path. Its gross margin, the part least affected by overhead, is shrinking. Even if it held a 3% operating margin, $15 million of operating income against a $500 million enterprise value is about 33 times EV/EBIT, and most of that income goes to interest first. Its low P/S is a measure of how little the equity owns after the lenders.
This is the comparison to run on every low P/S screen result. Dombey's published research applies this margin check before each catalyst; see the research archive.
When cheap sales matter
A low P/S is more likely to point to real value when several conditions hold together:
- Gross margin is stable, so the core product still earns money and the problem sits lower in the income statement.
- Margins are depressed for a reason that can reverse, and you can name it.
- EV/sales is also low, so debt is not absorbing the value.
- Revenue is stable or growing, and the sales are the company's own rather than pass-through.
- There is a dated event that could close the gap, such as an asset sale, the end of a restructuring, a new contract or a spin-off. A clear stock catalyst turns a cheap ratio into a thesis with a date.
Low P/S often shows up alongside other balance sheet signals. A company trading below sales and below net cash per share is a different case from one cheap on sales because of heavy debt. The same goes for companies cheap on both sales and book; the price-to-book ratio and the guide to how to value a company below book cover that side.
- If gross margin is falling and revenue is shrinking, treat the low P/S as a warning, not an opportunity.
- If gross margin is stable and operating margin is down for a named reason, model the recovery and test the implied P/E.
- If EV/sales is far above P/S, read the debt maturities before anything else.
- If the company is selling or closing a division, recalculate P/S on the revenue that will remain.
Where this goes wrong
P/S has real limits that no adjustment fully fixes.
- Revenue can be bought. A company can grow sales by cutting prices, extending generous payment terms or acquiring other businesses. Revenue rises while profit does not.
- Revenue recognition involves judgment. Timing on long contracts, gross versus net reporting and bundled products all affect the top line. Read the revenue recognition note in the 10-K.
- Normal margins may not return. A margin that was 8% for a decade can settle at 3% after a new competitor arrives. Using the old margin to value the company is the most common error with P/S.
- Debt changes everything. P/S ignores leverage. A highly indebted company can look cheap on sales while the equity is worth little.
- Cheap can stay cheap. Without a catalyst or a visible margin recovery, a stock can trade at a low multiple of sales for years.
The bottom line
The price-to-sales ratio divides market capitalization by trailing revenue. It is useful when earnings are negative or distorted, which makes it common in turnarounds and special situations. A low P/S only means value when the company can earn a normal margin on those sales and debt is not taking the proceeds. Read it next to gross margin, operating margin and EV/sales, and look for a named reason the margin will recover.