

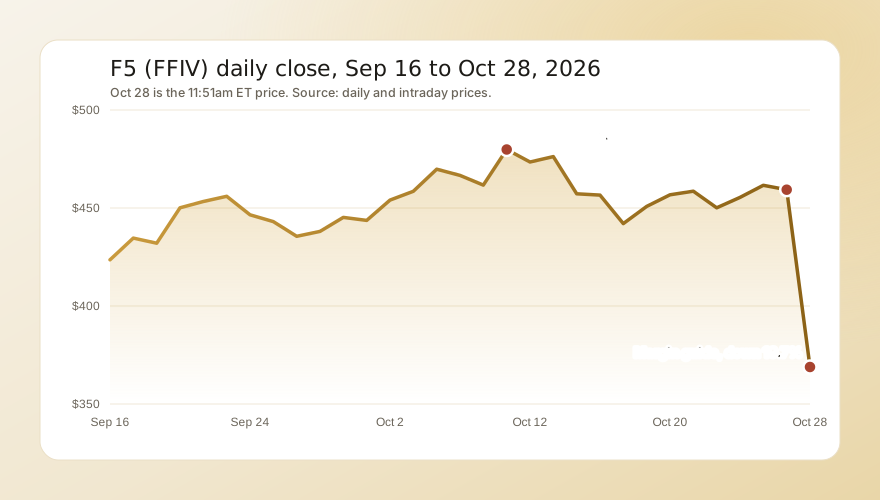
Oct 28, 2026: a steady slide from the open to a midday low
F5 reported after the close on Oct 27. The stock traded at $440.01 when premarket trading opened at 4am, already down 4.2%, and slipped to $415.01 by 9am. It opened the regular session at $421.30, touched $429.46 in the first minutes, and then fell almost without a pause to $368.08 at 11:50am, down 19.9%. At 11:51am it was $368.86 on 1.56 million shares.
What pushed it down:
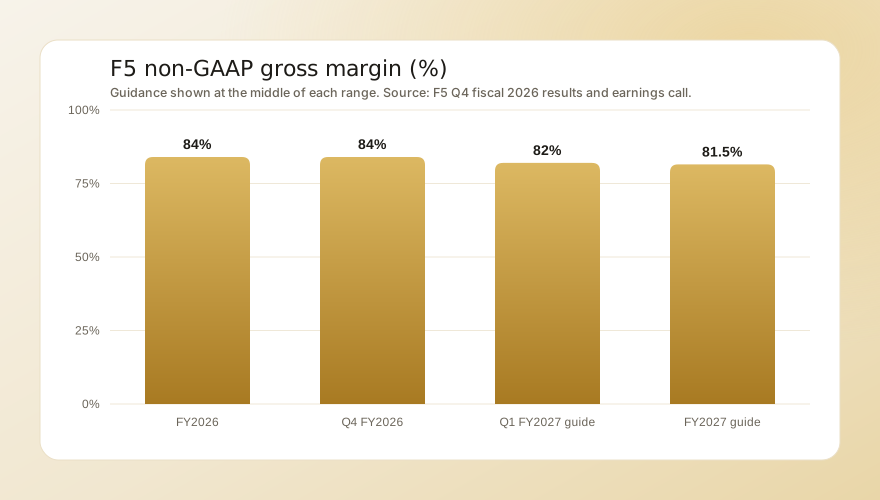
- The margin guide. Non-GAAP gross margin was 84.0% in both the fourth quarter and the full year. F5 guided the first quarter to about 81.5% to 82.5% and fiscal 2027 to 80.5% to 82.5%. CFO Cooper Werner tied the range to "the higher component costs we have discussed previously," and said memory and storage were the area "most at risk." He said F5 plans to keep raising prices once a year, with an off-cycle move possible if costs speed up.
- The refresh is maturing. Systems revenue rose 29% in the quarter and 31% for the year as customers replaced older hardware. F5 now expects upper-single-digit systems growth in fiscal 2027, stronger in the first half. Werner said, "That growth likely will be slower in the second half just from the cyclical part of the refresh," and told Morgan Stanley's Meta Marshall that replacement bookings will likely decline from a year earlier in the second half.
- A downgrade. Piper Sandler moved the stock to Neutral from Overweight with a $461 target, 24/7 Wall St. reported. Investing.com said the firm sees the iSeries refresh nearing its end and no clear near-term catalyst. Evercore ISI went the other way, raising its target to $500.
- Cash flow dipped. Operating cash flow was $118 million in the quarter and free cash flow $91 million, held down by inventory builds and supplier prepayments that F5 says secure parts for fiscal 2027 demand.
From the Oct 27 close, at 11:51am:
| Stock or fund | Oct 27 close | Oct 28, 11:51am | Change |
|---|---|---|---|
| Arista Networks (ANET) | $187.00 | $187.38 | +0.2% |
| Invesco QQQ (QQQ) | $721.25 | $722.02 | +0.1% |
| iShares software ETF (IGV) | $111.78 | $110.98 | -0.7% |
| Cisco (CSCO) | $111.38 | $110.20 | -1.1% |
| Akamai (AKAM) | $99.59 | $97.99 | -1.6% |
| Cloudflare (NET) | $327.80 | $318.88 | -2.7% |
| F5 (FFIV) | $459.36 | $368.86 | -19.7% |
After the drop, RSI(14) stood at 28, the shares sat 14% below their 50-day average and 2% above their 200-day average, volume ran 2.7 times its 20-day average, and the stock was 24% below its 52-week high of $483.30.
The numbers behind the move
The fourth quarter was strong. Product revenue rose 23% to $510 million, the ninth straight quarter of double-digit product growth, and software revenue rose 19% to $271 million. For the year, revenue rose 11% to $3.42 billion and non-GAAP EPS was $17.49. CEO François Locoh-Donou said "Q4 closed out an exceptional fiscal year."
The outlook is where the market looked:
| Measure | Fiscal 2026 | Fiscal 2027 guide |
|---|---|---|
| Revenue growth | 11% | 8% to 9% |
| Non-GAAP gross margin | 84.0% | 80.5% to 82.5% |
| Non-GAAP operating margin | 35.1% | 33% to 35% |
| Non-GAAP EPS | $17.49 | $18.00 to $18.30 |
EPS growth of 3% to 5% is slow for a company that grew product revenue 19% last year, and that gap is the case Piper Sandler is making. The other reading is that F5 is holding EPS growth through a jump in component costs with price increases and a lower share count, and that the analyst average already sat at $18.16 before the report. Our page on why guidance changes move stocks covers why a beat paired with a softer outlook often draws this reaction, and our guide on how to read an earnings release shows where margin guidance sits in a report like this one.
The bull case
- The earnings outlook held. The $18.00 to $18.30 range brackets the $18.16 analyst average, and revenue guidance of 8% to 9% growth implies about $3.69 billion to $3.72 billion for fiscal 2027.
- AI is starting to show up. Bookings tied directly to AI use cases passed $100 million in fiscal 2026, up nearly 300%, and active AI customers grew fourfold to more than 200, MarketBeat reported from the call. Management sizes the AI market it can sell into at about $11 billion by 2030.
- The buyback is large. About $1.8 billion of authorization is roughly 9% of the market value at $368.86, and F5 has no net debt. Our page on buybacks as catalysts explains when repurchases move a share count enough to matter.
- The multiple reset. At about 20 times the middle of the EPS guide, the stock is cheaper than at any point in the past six weeks; see our page on forward and trailing P/E.
The risks
- Memory costs can rise further. Werner said the supply chain is not fully derisked, and an off-cycle price increase could slow orders.
- The refresh comparison. Replacement bookings will likely fall from a year earlier in the second half, and strong sovereignty projects in Europe make the comparisons harder.
- Spending on sales. Operating expenses step up as F5 hires AI security specialists, which is why operating margin guidance of 33% to 35% sits below fiscal 2026's 35.1%.
- Analysts may cut targets. The average target is $430.50, and the Piper downgrade may not be the last if estimates follow the margin guide lower.
What comes next
- Estimate revisions over the next two weeks. If fiscal 2027 EPS estimates stay near $18, the drop was about the multiple, not the earnings. Our page on earnings estimate revisions explains why the direction of revisions matters.
- Buyback pace. The first-quarter 10-Q will show how much stock F5 bought after the drop.
- The first-quarter report, expected around January 26, 2027. Watch gross margin against the 81.5% to 82.5% guide, systems growth, and any change to the full-year EPS range.
For more of the day's large moves, see today's biggest stock moves.