

Nov 4, 2026: a second profit cut in three months
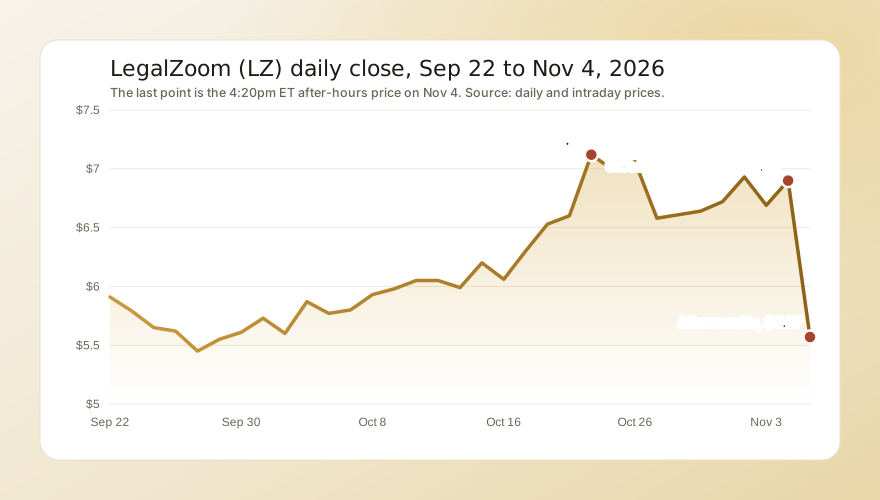
LegalZoom rose 3.1% in the regular session to close at $6.90, about in line with other small business software names: GoDaddy rose 4.3%, Wix 7.8%, Intuit 3.5% and Thomson Reuters 6.4%, while the software fund IGV rose 0.9%. The stock had gained 27% from its Sept. 28 close of $5.45 into the report.
The results came out at 4:01pm, with a call at 4:30pm. The first after-hours trade was $6.09 at 4:03pm, the low of $5.30 came at 4:10pm, and at 4:20pm the stock was $5.57, down 19.3%. StockStory put the drop at 20.3% shortly after the release.
What moved the stock:
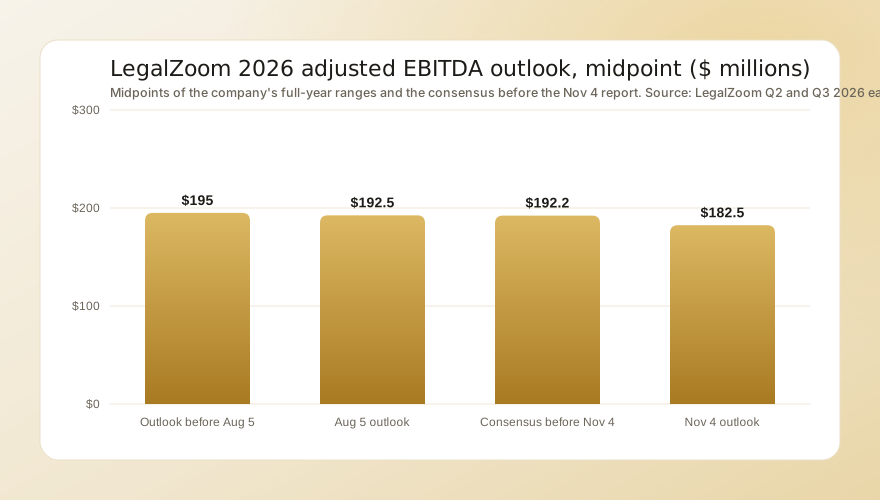
- Profit outlook cut. The full-year adjusted EBITDA range fell by $10 million to $180 million to $185 million, a 23% margin at the midpoint instead of 24%. The midpoint of $182.5 million is about 5% below the $192.2 million consensus. In August the company had already trimmed the top of the range to $195 million from $200 million.
- Why it was cut. The release says "more than half of the change reflects continued investment in channel diversification, including partnerships, affiliates" and that "approximately one quarter reflects higher costs in paid customer acquisition channels." Chief financial officer Noel Watson said the new outlook "reflects the cost of that environment."
- Fewer new businesses. Business formations, LegalZoom's main way of signing new customers, fell 13% to 110,000. Transaction revenue fell 14% to $55.5 million, and average order value fell 12% to $222.
- Slowing growth. Fourth-quarter revenue guidance of $190 million to $196 million implies about 1% growth. Its $193 million midpoint is about 0.9% below the $194.7 million consensus, StockStory reported.
The setup made the miss sharper. In August the stock fell 30.1% in a day after the company cut its revenue outlook to about $800 million from $820 million, announced a 13% workforce reduction and said its Google search losses were structural, Tickeron reported. JPMorgan and William Blair downgraded it that day. The October rally priced in some relief that did not come.
Before the report, RSI(14) stood at 61, the shares sat 12.0% above their 50-day average and 5.9% above their 200-day average, volume ran 1.6 times its 20-day average, and the stock was 44.4% below its 52-week high of $12.40. The after-hours price is close to the 52-week low of $5.22 from June 22. More of today's biggest stock moves are on the market page.
The numbers
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $195.1 million | $190.2 million | +3% |
| Subscription revenue | $139.7 million | $125.4 million | +11% |
| Transaction revenue | $55.5 million | $64.8 million | -14% |
| Business formations | 110,000 | 126,000 | -13% |
| Subscription units | 1.854 million | 1.959 million | -5% |
| ARPU | $280 | $256 | +9% |
| Adjusted EBITDA | $50.0 million | $46.3 million | +8% |
| Free cash flow | $34.1 million | $47.0 million | -27% |
The quarter itself was not bad. Adjusted EBITDA of $50.0 million matched the $49.9 million consensus, gross margin rose to 71% from 67%, and net income rose to $8.1 million from $4.5 million. Non-GAAP earnings were $0.19 a share, in line with estimates of about $0.19. GAAP earnings of $0.05 a share missed the $0.07 StockStory cited. Our guide to reading an earnings release shows how to separate the quarter from the outlook, and our page on adjusted EBITDA covers what the measure leaves out.
The problem is the trend under the totals. Revenue growth slowed from 7% in the second quarter to 3% in the third, and subscription units fell from 1.892 million at June 30 to 1.854 million. Free cash flow fell 27% and operating cash flow 26%.
The bull case
Subscriptions are doing the work. Chief executive Jeff Stibel said "revenue from human-in-the-loop subscription services grew 17% year-over-year and now represents 49% of total revenue." Those plans, which pair software with access to attorneys and other experts, raise revenue per customer, and ARPU rose 9% even as units fell. Stibel said the results "give us confidence to accelerate our investment in bringing expert support into the customer relationship."
The balance sheet gives it room. LegalZoom has $181.7 million of cash and no debt, and it has cut its share count to 166.2 million from 177.6 million at the end of 2025 with buybacks. At $5.57 the company is worth about $926 million, or about $744 million net of cash, roughly four times the new EBITDA midpoint. Short interest is 11.4% of the float, which can add to a rebound if the next report steadies. Our page on buybacks as catalysts covers when repurchases at low prices matter.
The risks
The business is paying more to stand still. Sales and marketing rose about 13% to $76.9 million while revenue rose 3%, and the company now says paid channels cost more. In August Stibel said "demand for what we do is intact, discovery is moving," meaning fewer small business founders find LegalZoom through search as AI tools answer their questions. New channels such as partnerships and affiliates take time and money, and this quarter showed the money before the results.
Two cuts in three months also hurt trust in the outlook. Estimates for 2027 will likely come down, and our guide to earnings estimate revisions explains why falling forecasts often keep weighing on a stock after the first drop. Our explainer on guidance changes covers why a lower profit range can matter more than a beat on the quarter. A low multiple on shrinking earnings can also be a value trap.
What comes next
The fourth-quarter report is expected in mid to late February 2027, with the 2027 outlook. Before then, watch for analyst rating and target changes on Nov 5, whether the stock holds the $5.30 after-hours low and the $5.22 low from June, and any update on partnership traffic or the pace of buybacks under the $65.8 million left on the authorization. The 2027 outlook will show whether this year's extra spending turns into steadier formations or simply becomes the new cost of doing business.