

Where the idea comes from
Buffett introduced owner earnings in an appendix to the 1986 letter. Berkshire had bought Scott Fetzer, and purchase accounting added large non-cash charges, mostly amortization and depreciation on the higher values assigned to the acquired assets. Reported earnings fell, yet the business itself had not changed. The same company, owned by Berkshire, appeared to earn less than it had the year before.
His point was that accounting earnings and economic earnings can diverge, and that owners should care about the second. He also warned against the opposite error. Many people at the time quoted "cash flow" as net income plus depreciation, and he called this misleading because it ignored the capital spending that most businesses must make just to stay in place. He added that for most businesses the required spending usually exceeds depreciation, so the popular cash flow figure overstated what owners earned.
Owner earnings sit between these two errors. They add back charges that do not reflect real economic cost, and they subtract spending that does.
The owner earnings formula
The formula has three parts, labeled (a), (b) and (c) in the letter:
- (a) Reported earnings. Net income from the income statement.
- (b) Plus non-cash charges. Depreciation, depletion, amortization and certain other non-cash charges.
- (c) Minus maintenance capital spending. The average annual amount spent on plant and equipment that the business needs to fully maintain its long-term competitive position and its unit volume.
Buffett added one more adjustment: if the business needs additional working capital to maintain its position and unit volume, that amount is also subtracted.
Items (a) and (b) come straight from the filings. You can find them in the income statement and the cash flow statement of a 10-K; our guide on how to read a cash flow statement shows where each line sits. Item (c) is the hard part. No standard accounting rule splits capital spending into maintenance and growth, so it is a guess. Buffett said as much: the figure for (c) is an estimate, and sometimes a difficult one.
Owner earnings vs other earnings measures
Owner earnings overlap with several common measures, but each answers a different question.
| Measure | How it is built | What it captures | Main blind spot |
|---|---|---|---|
| Net income | Revenue minus all expenses under GAAP | Accounting profit | Non-cash charges can distort it either way |
| EBITDA | Earnings before interest, taxes, depreciation and amortization | Operating earnings before capital costs | Treats capital spending as if it were free |
| Operating cash flow | Net income plus non-cash charges, adjusted for working capital | Cash generated by operations | Ignores capital spending entirely |
| Free cash flow | Operating cash flow minus all capital spending | Cash left after all investment | Penalizes growth spending; swings with working capital |
| Owner earnings | Net income plus non-cash charges minus maintenance capital spending | Cash owners could take out without shrinking the business | Depends on an estimate that is not disclosed |
The contrast with free cash flow matters most. A company that spends heavily to build new capacity will show low free cash flow even if its existing business is very profitable. Owner earnings separate the two: they measure what the current business earns and leave the growth spending to be judged as an investment decision. Our explainer on free cash flow yield covers the standard measure and how investors use it.
The contrast with EBITDA is just as sharp. EBITDA adds back depreciation and stops there. Owner earnings add it back and then subtract the real spending that depreciation is meant to approximate. Our piece on EV/EBITDA and its blind spots explains why ignoring capital spending flatters capital-heavy businesses.
How to estimate maintenance capital spending
Since companies rarely report maintenance capital spending, investors use a few methods. Using two of them and comparing the answers is better than relying on one.
Start from depreciation
Depreciation is an accounting estimate of how fast fixed assets wear out, so it is a natural starting point. It works poorly when assets were bought long ago at lower prices, because replacement costs more than the historical cost being depreciated. In that case maintenance spending will run above depreciation. It also works poorly after an acquisition, when assets are written up and depreciation rises without any change in real spending needs.
Back out growth spending
A common approach estimates growth spending and subtracts it from total capital spending. Take the ratio of average net fixed assets to sales over several years. Multiply it by the year's increase in sales. The result approximates the spending needed to support the extra sales. Total capital spending minus that amount is an estimate of maintenance spending. The method assumes new sales need fixed assets in the same proportion as old sales, which is not always true.
Read what management says
Some companies discuss maintenance and growth spending in the 10-K, in the management discussion section or on earnings calls. Treat these figures with care, since management has a reason to label as much spending as possible "growth". Compare their figures with depreciation and with the company's history. You can search filings for terms like "maintenance capital" with SEC EDGAR full-text search.
Do not forget working capital
A business with rising prices or a growing order book may need more inventory and receivables just to keep the same unit volume. That extra working capital is a real cost to owners. Our explainer on working capital for equity investors covers how to read those balance sheet lines.
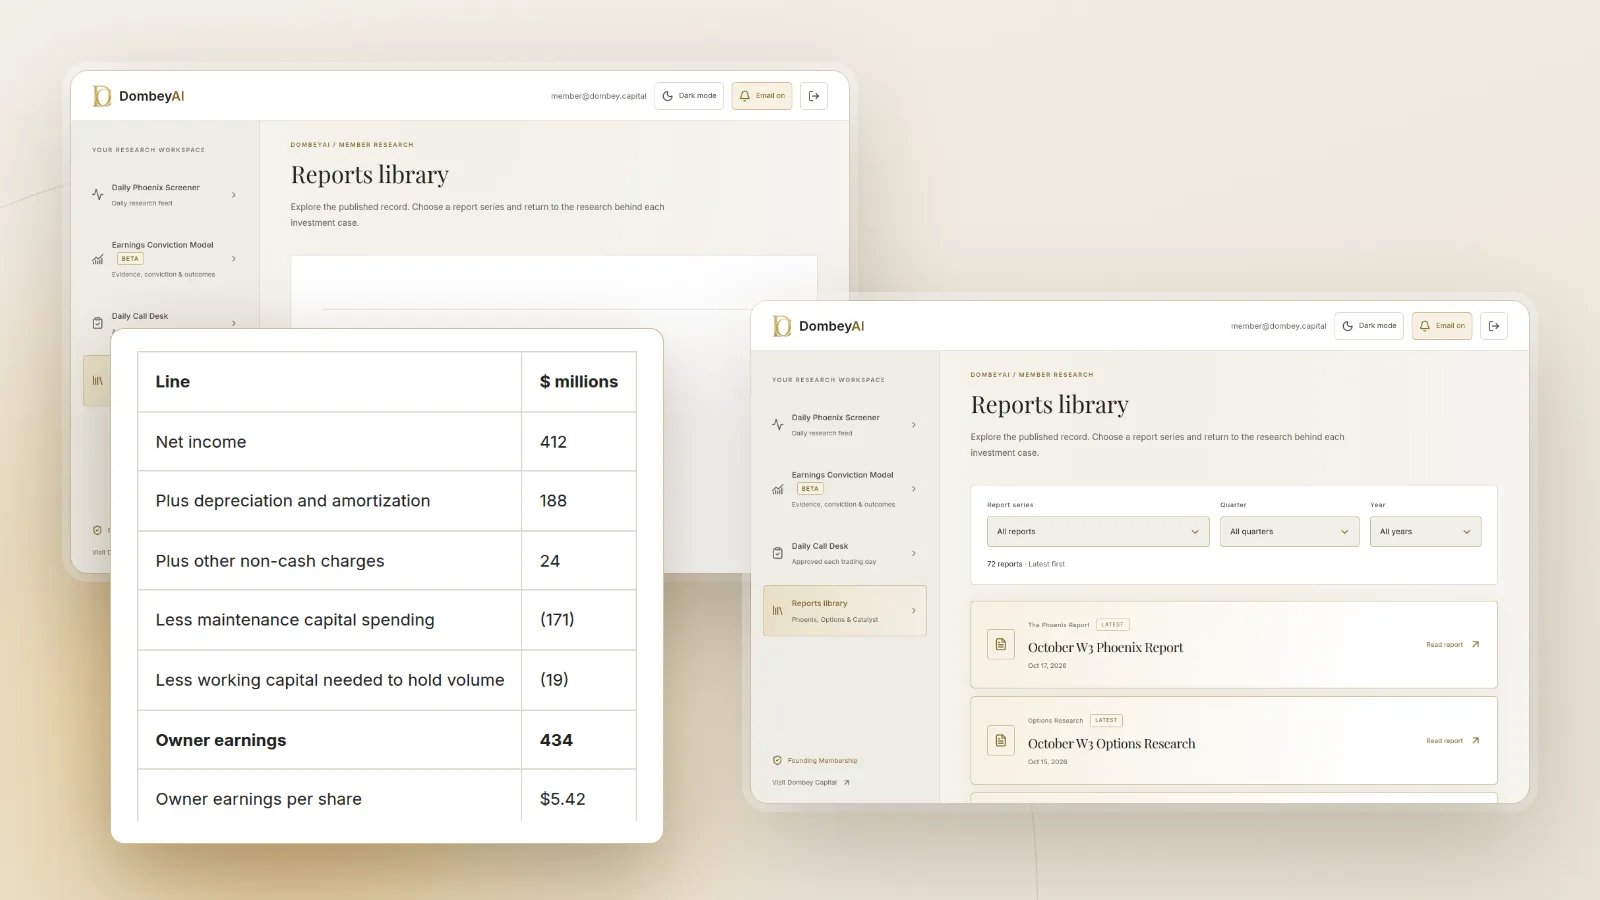
Worked example: Company A
The figures below are illustrative and describe a hypothetical company.
Compare that with the other measures for the same year. Assume operating cash flow is $195 million. Free cash flow is $195 million − $110 million = $85 million. A simple "cash flow" figure of net income plus depreciation is $200 million.
So the range is wide: $85 million of free cash flow, $120 million of owner earnings, $200 million of the popular cash flow figure. The owner earnings number says the current business earns about $120 million a year for its owners, and the company chose to reinvest about $40 million of that in growth. Whether that reinvestment is worth making is a separate question, best judged with return on invested capital.
Worked example: Company B after an acquisition
This second case shows the situation Buffett was describing. The figures are again illustrative.
With 50 million shares outstanding, reported earnings per share are $0.60 and owner earnings per share are $1.56. At a hypothetical share price of $20, the stock trades at about 33 times reported earnings but at an owner earnings yield of 7.8%. A screen based on the price-to-earnings ratio would show the stock as expensive. Owner earnings show a different picture.
The adjustment rests on a judgment: that the acquired intangibles do not need to be replaced. If customer relationships fade and must be won back with marketing spending, part of that amortization is a real cost after all. Our piece on goodwill and impairments covers how acquired intangibles are recorded and when they are written down.
How investors use owner earnings
Owner earnings are an input, not a conclusion. Investors put them to work in a few ways.
- As a yield. Owner earnings per share divided by the share price gives a yield you can compare with bond yields and with your own required return.
- As the base of a valuation. Owner earnings can stand in for the cash flow in a discounted cash flow model, with growth spending modeled separately.
- As a check on reported earnings. A large gap between net income and owner earnings is worth explaining. It may reflect acquisition accounting, a heavy reinvestment cycle or a business that needs more capital than its depreciation suggests.
- As a margin of safety test. Buying at a price well below a conservative estimate of value built on owner earnings is one way to apply a margin of safety.
Gathering the inputs across several years of filings takes time. Many investors use a data platform for the raw figures and do the maintenance estimate themselves; our list of the best stock research tools for individual investors compares the options.
Where this goes wrong
Owner earnings correct some accounting problems and create others. The common failures are these.
- An optimistic maintenance estimate. Calling most capital spending "growth" makes owner earnings look large. If the spending is really needed to keep up with competitors, the business is earning less than the estimate says.
- Ignoring working capital. Businesses that sell on credit or hold large inventories can need steady increases in working capital just to stand still. Leaving that out overstates owner earnings.
- Adding back stock-based pay. Stock-based compensation is a non-cash charge, but it transfers part of the business to employees. Adding it back without counting the dilution from a rising share count treats a real cost as free.
- Adding back amortization that is real. Some intangibles, such as software or customer relationships, do need ongoing spending to maintain. Adding back their amortization in full overstates earnings.
- Cyclical peaks. A single year of owner earnings at the top of a cycle can mislead. Average several years, as Buffett's own wording on average annual spending suggests.
- Businesses where the measure does not fit. Banks and insurers do not have capital spending in the usual sense, and early-stage companies with losses have no stable base to adjust.
The bottom line
Owner earnings measure what a business earns for its owners after the spending needed to keep it competitive. The formula is simple: reported earnings, plus non-cash charges, minus maintenance capital spending and any working capital the business needs to hold its position. The difficulty is the maintenance figure, which is never disclosed and has to be estimated from depreciation, sales growth and management's comments. Used carefully, owner earnings cut through acquisition accounting and heavy growth spending to show what the existing business produces. Used carelessly, they become a way to make any company look cheap.