

Where terminal value fits in a DCF
A discounted cash flow model values a business as the present value of its future free cash flow. Forecasting every year forever is impossible, so the model splits time in two:
- The explicit forecast, usually five to ten years, where you model revenue, margins, reinvestment and free cash flow year by year.
- The terminal period, everything after, summarized in one terminal value at the end of the forecast.
Enterprise value is the present value of the forecast cash flows plus the present value of the terminal value. Subtract net debt and other claims to get equity value. Our explainer on enterprise value covers that bridge.
The forecast should run until the business reaches a steady state, where growth, margins and reinvestment are stable. Terminal value assumes that state continues. If the business is still changing fast at the end of year five, extend the forecast instead of asking the terminal value to absorb the change.
Method 1: perpetuity growth
The perpetuity growth method, also called the Gordon growth method, treats the business after the forecast as a cash flow growing at a constant rate forever.
Terminal value = FCF in year n+1 / (discount rate - g)
Here FCF is free cash flow to the firm, the discount rate is usually the weighted average cost of capital and g is the long-run growth rate. The year n+1 cash flow is the final forecast year's cash flow grown by g once.
Two rules keep the method honest:
- g must be below the discount rate. If it is equal or higher, the formula produces infinity or a negative number. In practice g should sit at or below long-run nominal economic growth, since no company can outgrow the economy forever.
- Growth must be paid for. A business that grows needs to reinvest. If the terminal cash flow assumes the same reinvestment as a no-growth business while g is 4%, the value is overstated. A useful check is reinvestment rate equals g divided by the return on new capital. Our guide to ROIC explains that return.
Method 2: exit multiple
The exit multiple method assumes the business could be sold, or would trade, at a market multiple at the end of the forecast.
Terminal value = final-year metric x multiple
The metric is usually EBITDA, EBIT or, for some sectors, earnings or book value. The multiple usually comes from comparable companies or past deals. Our explainer on EV/EBITDA covers what the most common multiple does and does not capture.
The method is simple and anchored to market prices. Its weakness is the same anchor: it imports today's market mood into a value five or ten years out, and today's multiples for fast-growing peers may not fit a mature business at the end of your forecast.
The two methods compared
| Feature | Perpetuity growth | Exit multiple |
|---|---|---|
| Core input | Long-run growth rate g | A valuation multiple, such as EV/EBITDA |
| Anchored to | Cash flow and economic limits on growth | What similar companies trade or sell for |
| Main strength | Forces you to think about reinvestment and returns | Simple, and easy to compare with the market |
| Main weakness | Very sensitive to g as it nears the discount rate | Imports current market pricing into a future date |
| Best used for | Mature businesses with stable cash flow | Sectors with deep sets of comparable companies and deals |
| Cross-check | The multiple it implies | The growth rate it implies |
A worked example
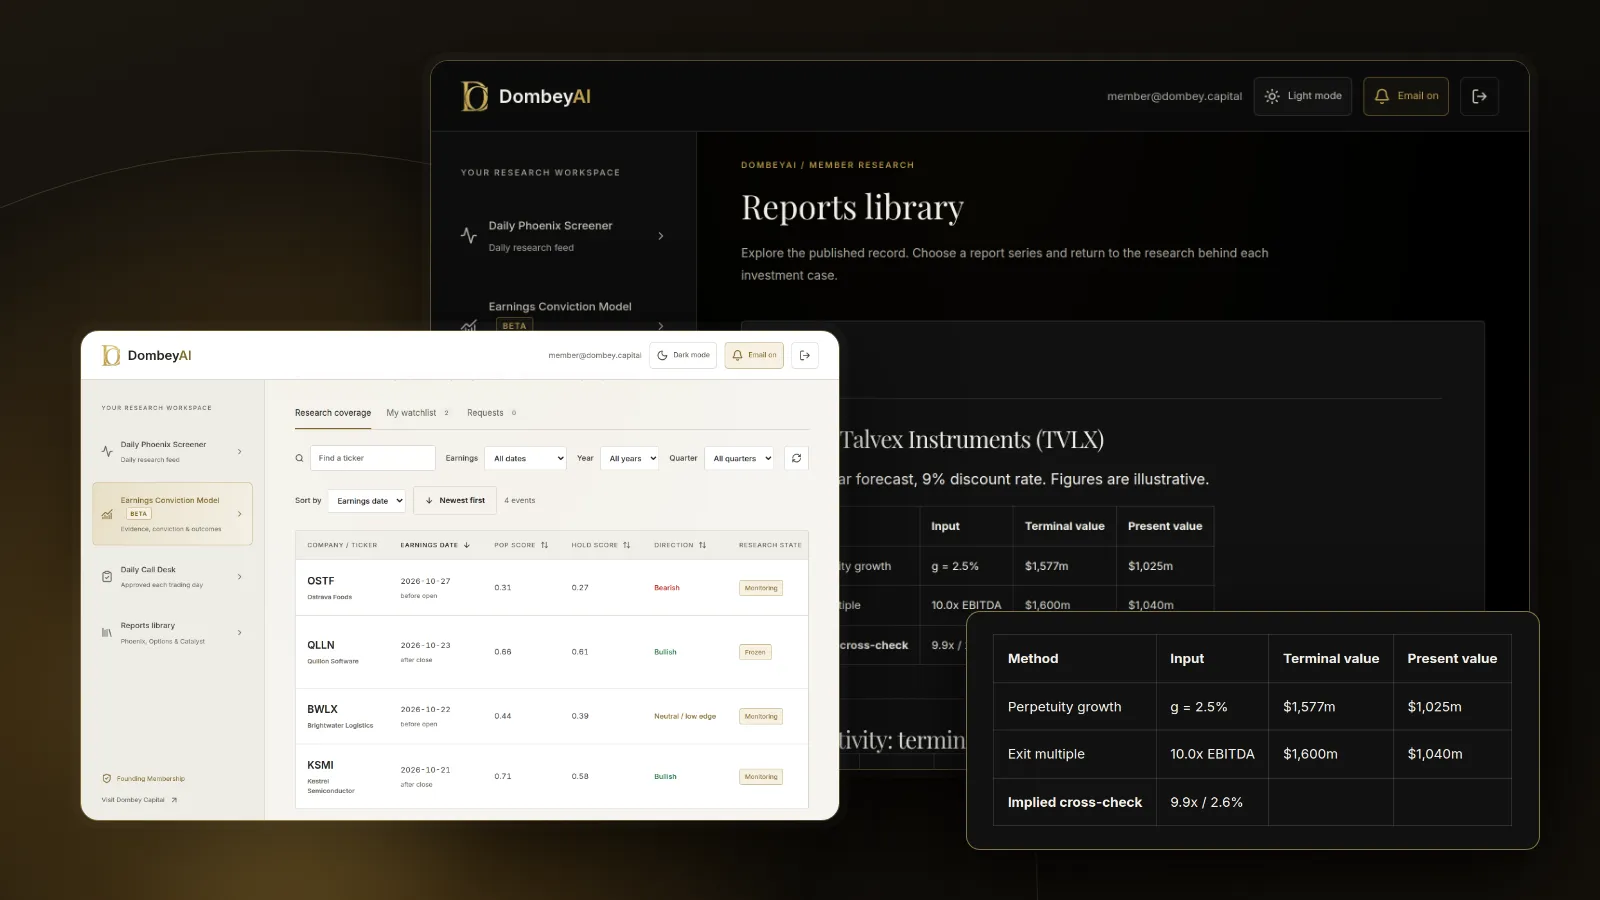
The share of value in the terminal period is normal for a DCF and is the reason to test it. Now change g to 3.5%: terminal value becomes $103.5 million / 5.5% = about $1,882 million, almost 20% higher, from one percentage point of growth.
Test the answer with a sensitivity table
Because terminal value moves so much with its inputs, show a grid rather than one number.
| Discount rate / g | 1.5% | 2.5% | 3.5% |
|---|---|---|---|
| 8% | $1,562m | $1,864m | $2,300m |
| 9% | $1,353m | $1,577m | $1,882m |
| 10% | $1,194m | $1,367m | $1,592m |
The table uses the same year-five cash flow of $100 million grown by each g, and the values are terminal values at year five, before discounting. They are illustrative.
Then cross-check the methods against each other:
- The implied exit multiple of the perpetuity result is terminal value divided by final-year EBITDA. In the example, $1,577 million / $160 million is about 9.9x. If peers trade at 6x, your growth rate is generous.
- The implied growth rate of the exit multiple result solves the perpetuity formula for g. If a 14x multiple implies 5% growth forever, the multiple is too high for a mature business.
If the two methods disagree badly, one of the inputs is wrong. Resolve the gap before you trust either. Our guide to building a base and worst case shows how to carry those ranges into the final valuation, and a reverse DCF turns the question around by solving for the growth the current price already implies.
Where this goes wrong
Terminal value errors tend to repeat.
- Growth near the discount rate. As g approaches the discount rate, terminal value explodes. One percentage point of growth can add a fifth or more to the answer.
- Growth without reinvestment. Holding reinvestment flat while assuming higher growth inflates cash flow.
- A forecast that ends too early. If margins or growth are still moving in the final year, the terminal value locks in an unfinished picture.
- Peak-cycle multiples. For cyclical companies, applying today's multiple to a peak-year EBITDA can overstate value twice.
- Forgetting to discount. Terminal value is a future value. It must be brought back to today.
- Mismatched cash flows. Free cash flow to the firm goes with the cost of capital and enterprise value. Cash flow to equity goes with the cost of equity and equity value. Mixing them gives a wrong answer that can look plausible.
For readers comparing tools that build these models, our list of the best stock research tools for individual investors covers platforms with DCF templates, and the best DCF calculators goes deeper on that one job.
Dombey's published research states its key valuation assumptions so readers can test them; see the research archive.
The bottom line
Terminal value stands in for every year after a DCF's forecast and usually carries most of the model's value. Estimate it with the perpetuity growth method, the exit multiple method or both, and discount the result back to today. Keep growth below the discount rate and pay for it with reinvestment. Then test the answer with a sensitivity grid and a cross-check between the two methods, because a terminal value you have not tested is a guess dressed as a figure.