

Oct 29, 2026: a beat, a raise and an acquisition
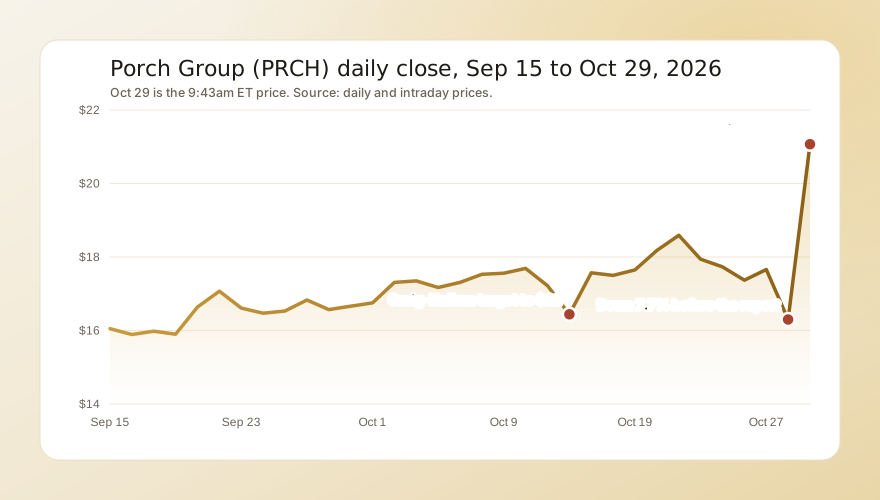
Porch opened at $19.46 at 9:30am, up 19.4%. It touched a low of $19.29 and a high of $20.85 in the first five minutes, reached $21.00 in the next five and was $21.07 at 9:43am. The stock needed no help from the market: the Invesco KIE insurance fund was up 1.6% and the financial sector fund XLF up 1.5% at the same time, so about 27 points of the gain belong to Porch.
What happened:
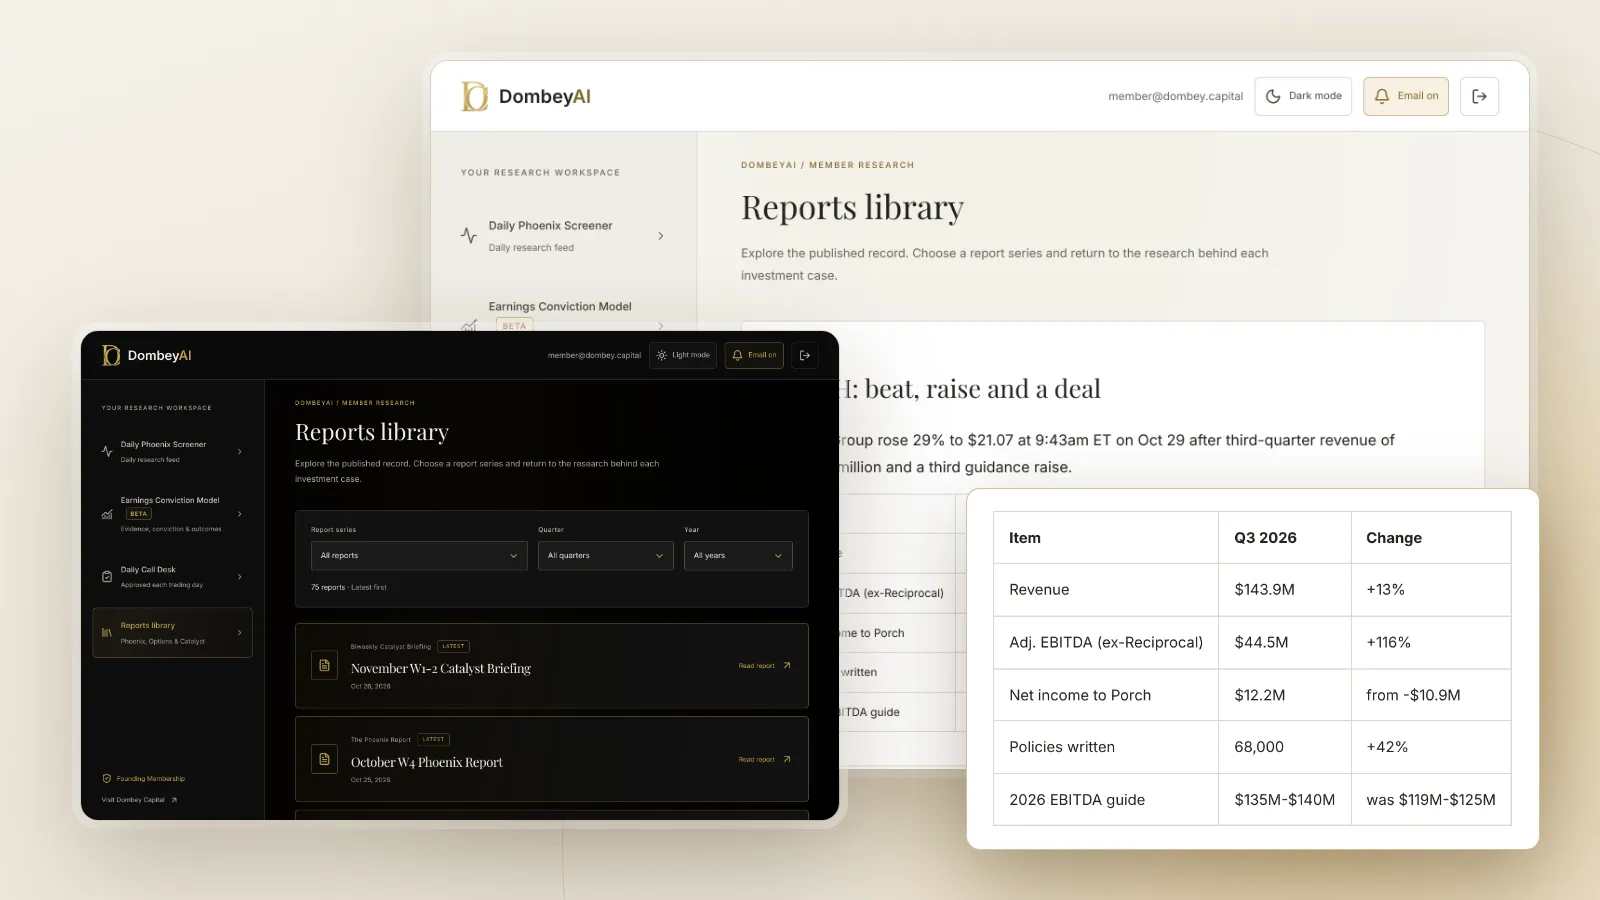
- A large beat. Revenue of $143.9 million rose 13% from $127.3 million. Net income attributable to Porch was $12.2 million, a $23 million swing from last year's loss of $10.9 million. Adjusted EBITDA excluding the Reciprocal was $44.5 million, up 116% from $20.6 million, the company said in its Oct 28 release. CEO Matt Ehrlichman said, "Porch continues to execute at a high level."
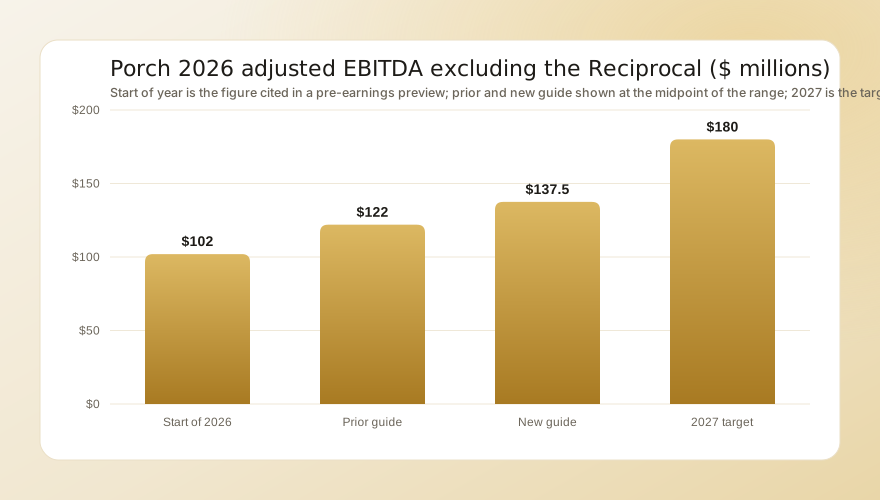
- Guidance up again. For the Porch-owned segments, 2026 revenue is guided to $518 million to $523 million (24% to 25% growth), gross profit to $438 million to $443 million and adjusted EBITDA to $135 million to $140 million (76% to 83% growth). Before the report the consensus for full-year revenue was about $500.6 million, below even the bottom of the old range.
- Allied Trust. Porch will pay about $200 million in total, or about $140 million net of the surplus it acquires. The Reciprocal pays $105 million for the carrier and Porch pays $95 million, $75 million in cash and $20 million in stock, for the managing general agency and reinsurance entities. Management expects about $25 million of adjusted EBITDA in the first full year and a close in the first quarter of 2027, and set 2027 targets of more than $900 million of Reciprocal written premium and more than $180 million of adjusted EBITDA excluding the Reciprocal.
From the Oct 28 close, at about 9:42am:
| Stock or fund | Price | Change |
|---|---|---|
| Porch Group (PRCH) | $21.07 | +29.2% |
| Root (ROOT) | $52.93 | +1.6% |
| Invesco KIE insurance fund (KIE) | $63.28 | +1.6% |
| Financial Select Sector fund (XLF) | $56.98 | +1.5% |
| Lemonade (LMND) | $45.92 | +1.2% |
| iShares Russell 2000 fund (IWM) | $283.47 | +0.8% |
| Hippo (HIPO) | $37.58 | -0.3% |
The other small insurers moved with the market. Porch moved on its own numbers. After the move, RSI(14) stood at 68 at about $20.79, the shares sat 21% above their 50-day average and 74% above their 200-day average, and the stock was 1% below its prior 52-week high of $21.00.
The numbers behind the raise
The third quarter had three engines, and the insurance one did most of the work.
- Insurance Services: revenue of $103 million rose 39%, with an adjusted EBITDA margin of 49%, the sixth quarter in a row in which growth and margin together topped 80.
- Reciprocal: about 68,000 policies written, up 42% from 38% growth in the second quarter. Written premium was $161 million, up 17%. The gross loss ratio was 24%. Statutory surplus rose to $174 million.
- Software and Data and Consumer Services: revenue of $22 million and $18 million, held back by a trough housing market. Monetized services fell 11% at Consumer Services.
Cash and investments outside the Reciprocal were $165 million, up $38 million from the second quarter, and net leverage was 2.4 times trailing adjusted EBITDA, inside the company's target of 2 to 3 times.
A guidance raise of this size matters more than the quarter itself. Our explainer on why guidance changes move stocks shows why: analysts reset their next four quarters from the new range, and estimate revisions tend to follow for weeks. The average target of $21 was set before the report, so it is the number most likely to change next. Our guide to reading an earnings release covers how to check a raise against the prior range, as the table above does.
The bull case
Three facts carry the most weight on the bullish side.
- Earnings power rose faster than the stock's multiple. The midpoint of 2026 adjusted EBITDA moved up about 13% in one report, and the 2027 target of more than $180 million is about 31% above that midpoint.
- Growth is speeding up, not slowing. Policies written grew 42% against 38% a quarter earlier, new-customer written premium rose 178%, quote volume rose 79% and the number of producing agency branch locations rose 114%.
- The insurer has room to grow. With $174 million of statutory surplus, management said premium capacity is approaching $1 billion from surplus alone, and Allied adds a second state footprint in Texas and Louisiana.
The bear case
The three facts that carry the most weight on the other side:
- Premium is growing slower than policies. Written premium rose 17% against 42% more policies. Before the report, a preview noted that management had acknowledged rivals cutting prices and that premium per new customer had fallen 4% in the prior quarter.
- The price has caught the targets. The stock is at the $21 consensus, 74% above its 200-day average and at a 52-week high, after climbing from a 52-week low of $6.36.
- Supply of shares. Porch said it expects to set up an at-the-market program that lets the Reciprocal sell some of its Porch shares over time to turn non-admitted assets into surplus, and it will issue $20 million of stock for Allied.
Risks and what comes next
Management said it has not finished assessing how much of Allied's book may be non-renewed or repriced after closing, and the deal must still close, which it expects in the first quarter of 2027. A catastrophe quarter is the other tail: the previous quarter included a $14 million storm hit, according to a pre-earnings preview. Weather losses sit mostly in the Reciprocal, but they can slow its surplus growth and so its capacity.
The next dated events are the close of Allied Trust and the fourth-quarter report, which last year came in mid-February. Readers who follow the setup into a report can use our guide to analyzing an earnings call transcript and the explainer on preparing for an earnings catalyst. Interest coverage matters here too, since Porch carries debt; see the interest coverage ratio. More of the day's swings are in today's biggest stock moves, and Dombey's own published work is in the research archive.