

Nov 18, 2026: a 10% jump that built through the morning
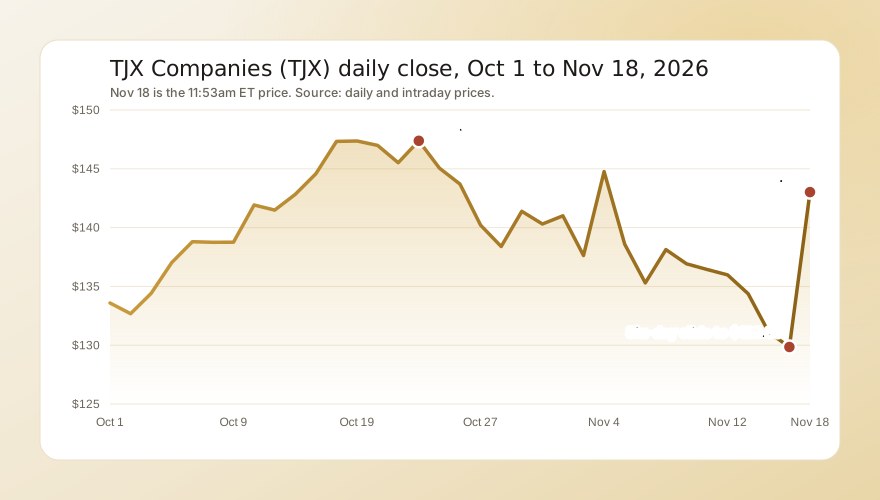
TJX closed Tuesday, Nov 17, at $129.85, its sixth straight decline. Extended trading that evening stayed between $129.65 and $130.80. The release came out before the open on Wednesday, and premarket trading reached $141.00 at 7:40am, 8.6% above the close, then eased to $138.00 by 9:25am.
The stock opened at $137.01 and dipped to $134.05 in the first minutes as some of the premarket gain came out. Buyers came back as the 11am call started, and the shares rose steadily to $143.70 at 11:30am, 10.7% above the close. At 11:53am they were $143.02, up 10.1%, on 8.5 million shares, already more than a full day's average.
What pushed it up:
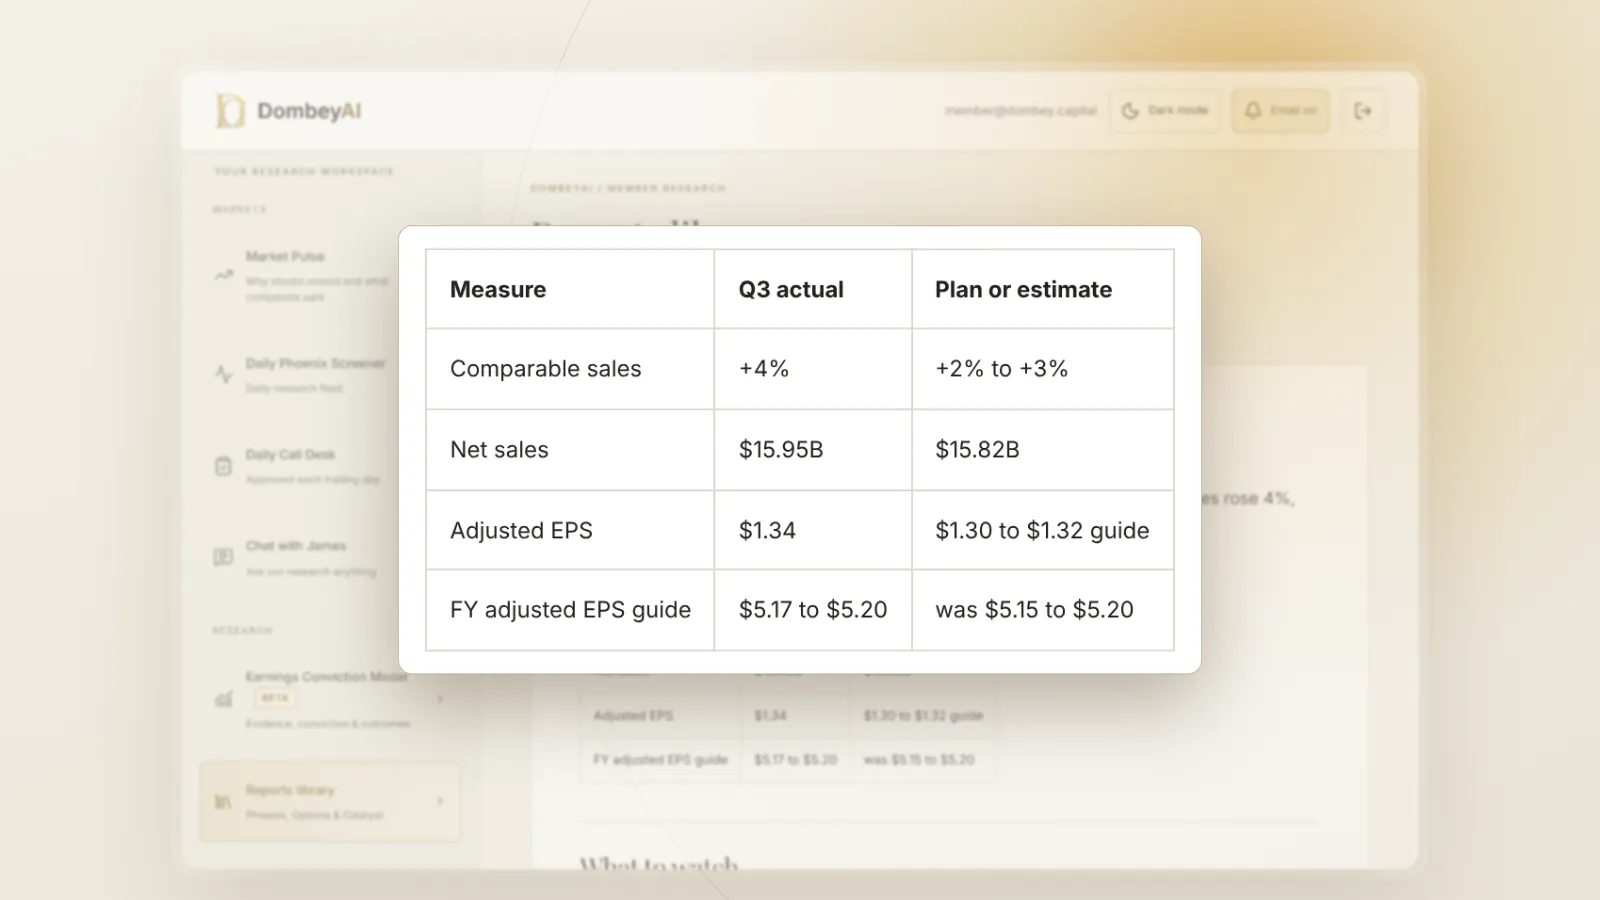
- Comparable sales above plan. Consolidated comparable sales rose 4% against a plan of 2% to 3%, and every division grew: Marmaxx 2%, HomeGoods 5%, TJX Canada 6% and TJX International 8%.
- A higher outlook. TJX raised the low end of its full-year adjusted earnings guide to $5.17 to $5.20 a share, from $5.15 to $5.20 after the second quarter, and now expects 4% comparable growth for the year.
- A holiday call. "We are expecting sales momentum to accelerate throughout the holiday season," Herrman said, adding that the company expects further improvement at Marmaxx in the fourth quarter.
- A stock that had already fallen. The shares lost 11.9% from $147.38 on Oct 22 to $129.85 on Nov 17, so expectations were low going in.
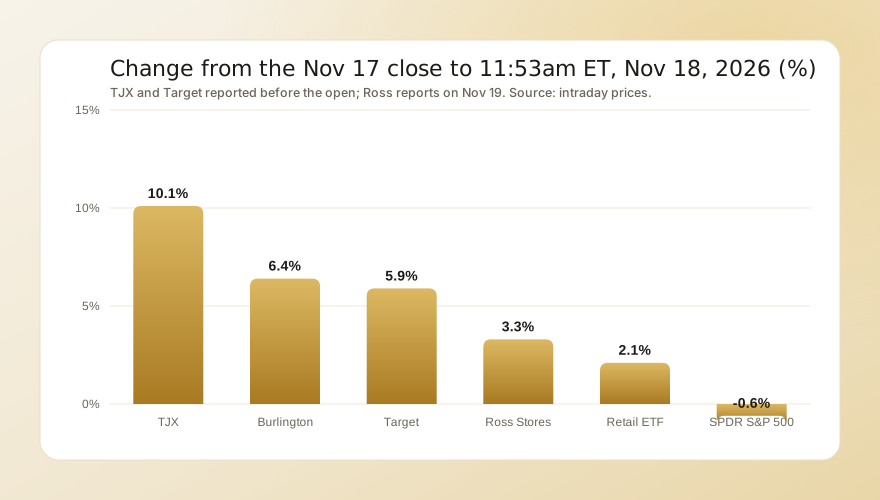
The report lifted the other off-price chains with it. Burlington rose 6.4% and Ross 3.3%, a day before Ross reports, and Target rose 5.9% after its own report, while the S&P 500 fund fell 0.6%. Short interest was only 1.4% of the float, so the move was buying, not a squeeze. Our explainer on why guidance changes move stocks covers why a higher outlook can matter more than a small beat, and the rest of the session's movers are in today's biggest stock moves.
After the jump, RSI(14) stood at 56, the shares sat 5% above their 50-day average and 5% below their 200-day average, volume ran 1.3 times its 20-day average, and the stock was 16% below its 52-week high of $170.00.
The numbers
| Measure | Q3 fiscal 2027 | Q3 fiscal 2026 |
|---|---|---|
| Net sales | $15.95B | $15.12B |
| Comparable sales | +4% | +5% |
| Marmaxx comparable sales | +2% | +6% |
| Adjusted pretax margin | 12.5% | 12.7% |
| Adjusted gross margin | 32.1% | 32.6% |
| Diluted EPS | $1.39 | $1.28 |
| Adjusted diluted EPS | $1.34 | $1.28 |
The quarter's headline earnings include a 5 cent net benefit from tariff refunds under the International Emergency Economic Powers Act, which TJX strips out of its adjusted figures. On the adjusted basis, the pretax margin of 12.5% was above plan but 0.2 points lower than a year earlier: freight and fuel cost 0.5 points of gross margin, and lower incentive pay plus lapping a foundation gift saved 0.3 points of selling and administrative cost. Our guide to reading an earnings release shows how to separate one-off items like these refunds from the core result, and our explainer on what gross margin changes signal covers why a freight-driven dip differs from a pricing problem.
Inventories were $9.8 billion, against $9.4 billion a year earlier, but flat per store, and the company said it is seeing "outstanding availability" of merchandise. It ended the quarter with $4.6 billion of cash after repaying a $1.0 billion note in September.
The bull case
TJX has now beaten its own comparable sales plan in a quarter when the U.S. consumer has been uneven, and the growth was broad: the international business grew sales 12% in constant currency, and HomeGoods grew 8%. The company opened 64 stores in the quarter, bringing the total to 5,349, and it returned $1.5 billion to shareholders, including $1.0 billion of buybacks. It now expects to buy back about $3.0 billion of stock this year. Off-price chains tend to gain when department stores and specialty retailers are left with excess inventory, and Herrman's comment on merchandise availability points that way. The consensus target of $174.15 sits about 22% above the 11:53am price.
The risks
- Freight and fuel. The fourth-quarter outlook now assumes higher fuel costs than the company planned in August, and transport costs already took 0.5 points off the gross margin.
- A slower fourth quarter. Planned comparable growth of 2% to 3% is below the third quarter's 4%, and warm weather in the U.S. and Canada has been holding back demand in some categories.
- Marmaxx. The largest division grew comparable sales only 2%, against 6% a year earlier, and it carries thinner margins than the international business.
- Valuation. At about 25 times forward earnings, the stock prices in steady growth. Our explainer on post-earnings drift covers why a large first-day move does not always hold.
What comes next
- Ross Stores reports on Nov 19. The consensus is $1.87 a share on about $6.25 billion of sales. Ross is the closest read on whether off-price demand held up into November.
- Thanksgiving weekend, Nov 27 to 30. The first test of the holiday acceleration Herrman described.
- Fourth-quarter results, expected in late February 2027. TJX reported its last fourth quarter on Feb 25, 2026, and the next report will bring the first fiscal 2028 outlook.