

Nov 5, 2026: a launch date for the glasses and a faster fourth quarter
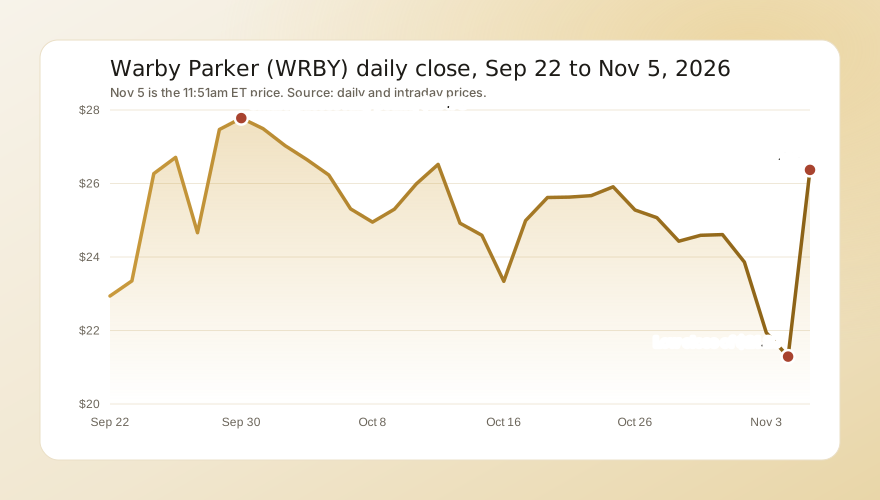
Warby Parker had fallen for three straight sessions into the report, closing Nov 4 at $21.29. Results came out before the open on Nov 5. Premarket trading began near $21.55 and reached $26.20 by 7:25am. The stock opened at $25.93, dipped to its low of $24.85 in the first minutes, then climbed to $27.00 at 11:35am. At 11:51am it was $26.37 on about 4.7 million shares, while the S&P 500 fund SPY was down 3.2%.
What moved it:
- A date and a partner for the glasses. Co-chief executive Dave Gilboa said Warby Parker will share the full collection and pricing next week, and that "we expect production and customer deliveries to build throughout 2027." The glasses run on Google's Gemini assistant and are meant to compete with Meta's Ray-Ban smart glasses, Seeking Alpha reported.
- A faster fourth quarter. The guide of $243 million to $253 million implies growth of about 15% to 20%, with adjusted EBITDA of $26 million to $28 million.
- The full year held up. The 2026 revenue range narrowed to $966 million to $976 million from $959 million to $976 million, Seeking Alpha reported, and adjusted EBITDA guidance stayed at $117 million to $119 million, including the launch costs.
- Talk of 2027. Gilboa said, "Looking ahead to 2027, we anticipate a rapid acceleration and growth," with details due in February.
Other eyewear and retail stocks did not move with it. Over the same period National Vision fell 0.5% and the retail fund XRT fell 2.5%. The rest of the session's movers are in today's biggest stock moves.
At 11:51am RSI(14) stood at 56, the shares sat 5.9% above their 50-day average and 5.2% above their 200-day average, volume was already 1.5 times its 20-day average, and the stock was 14.9% below its 52-week high of $31.00.
The numbers
| Measure | Q3 2026 | Change from a year earlier |
|---|---|---|
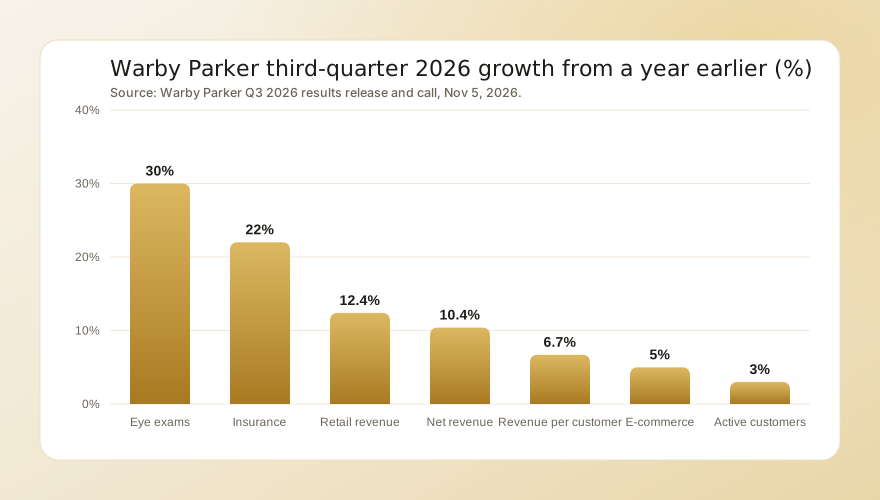
| Net revenue | $244.7 million | +10.4% |
| Gross margin | 54.4% | from 54.1% |
| Net income | $5.6 million | down $0.3 million |
| Adjusted EBITDA | $28.6 million | 11.7% margin, up 0.1 point |
| Active customers | 2.74 million | +3.0% |
| Average revenue per customer | $342 | +6.7% |
Warby Parker opened 12 net new stores in the quarter for a total of 364, and it ended September with $287.9 million of cash. Retail revenue grew 12.4% and e-commerce 5%, and in-network insurance penetration reached 8.4% from 7.4%. Our page on adjusted EBITDA covers what the adjusted figure leaves out, and our guide to guidance changes covers why a faster next-quarter guide can move a stock more than the quarter just reported.
The bull case
The glasses give Warby Parker a product with a higher price than traditional eyewear, management said, sold through stores and labs it already controls. Gilboa said the company is expanding capacity at its two optical labs and that partner reimbursements offset part of the launch costs. The core business is also changing in useful ways: eye exams and insurance bring in customers who come back more often, and average revenue per customer rose 6.7%. If pre-orders are strong, the 2027 outlook in February could be well above this year's 11% to 12% growth. Our page on post-earnings announcement drift covers why a stock that gaps on news of a new product line can keep moving for a while.
The risks
The stock already ran on this idea once. It jumped to $27.78 at the end of September on smart glasses enthusiasm and gave all of it back in five weeks. This time the price and demand arrive within days, on Nov 12, and an unappealing price or slow pre-orders would leave the stock resting on a core business growing about 10%. Analysts asked about cannibalization of regular glasses sales, the pace of deliveries against pre-orders and weak industry unit trends, which management put down mainly to consumer pressure and longer purchase cycles. Profit is thin: net income was $5.6 million on $244.7 million of revenue. Our page on price-to-sales ratios covers how to judge a valuation when margins are this slim.
What comes next
Pricing and pre-orders open on Nov 12, deliveries begin in mid-December, and the fourth-quarter report with 2027 guidance is expected around February 25, 2027. Watch the price point against Meta's glasses, any pre-order figures, and whether the stock holds above the $21.29 close it gapped from. A close above $27.78 or a fourth quarter above $253 million would undercut the Bearish case.