

The NCAV formula
The formula has three parts:
NCAV = Total current assets - Total liabilities - Preferred stock
NCAV per share = NCAV / Diluted shares outstanding
- Current assets are, in the SEC's words, things a company expects to convert to cash within one year. They include cash, short-term investments, accounts receivable, inventory and prepaid expenses.
- Total liabilities means all of them: current liabilities such as payables and accrued expenses, plus long-term debt, lease liabilities, pension obligations, deferred taxes and anything else on the liability side.
- Preferred stock ranks ahead of common shareholders. Subtract its liquidation preference when that is higher than its carrying value.
- Diluted shares include options, warrants, restricted stock units and in-the-money convertibles.
The key feature is what the formula leaves out. Property, plant and equipment, goodwill, intangibles and long-term investments all count as zero. Yet every liability, short-term or long-term, is subtracted in full. That asymmetry is deliberate. It produces a deliberately harsh floor.
The net-net test and the two-thirds rule
When a company's market capitalization is below its NCAV, the market is paying less than the current assets left after all debts are settled. The buyer receives the fixed assets and the operating business at a price below zero. Graham called these bargain issues, and investors now call them net-nets.
Graham did not stop at a price below NCAV. His test looked for a price at or below two-thirds of NCAV per share. The remaining third was a margin of safety, a cushion for the fact that current assets rarely realize their full book value and that the business may keep losing money.
Price to NCAV = Share price / NCAV per share
A ratio below 1.0 marks a net-net. A ratio at or below 0.67 meets the two-thirds test. Neither ratio says anything about whether the gap will close.
How NCAV compares with related measures
NCAV sits between two measures Dombey covers elsewhere. Net cash per share counts only cash and marketable securities, less debt. Tangible book value counts every tangible asset, including plant and equipment. NCAV counts all current assets but no long-term ones.
| Measure | Assets counted | Liabilities subtracted | Strictness |
|---|---|---|---|
| Net cash | Cash and short-term investments | Debt | Strictest on assets |
| Net-net working capital | Cash, plus haircut receivables and inventory | All liabilities | Very strict |
| NCAV | All current assets at book | All liabilities and preferred | Strict |
| Net working capital | All current assets at book | Current liabilities only | Loose |
| Tangible book value | All tangible assets | All liabilities and preferred | Loosest of the floors |
Two points matter most. First, NCAV subtracts long-term liabilities, so it is far stricter than net working capital. A company with a large term loan can show healthy working capital and negative NCAV. Second, NCAV is looser than net cash because receivables and inventory may not convert at book value. That is where the haircuts come in.
Haircuts: from NCAV to net-net working capital
Book values on the balance sheet assume a going concern. In a wind-down, or even a hard year, the liquid assets are worth less. A more conservative version, often called net-net working capital (NNWC), applies a discount to each current asset before subtracting liabilities.
Typical ranges analysts use, which are judgment calls rather than rules:
- Cash and short-term investments: 100%, less any restricted cash.
- Accounts receivable: around 75% to 90%, lower if customers are concentrated, overdue or in trouble.
- Inventory: around 50% to 75%, lower for fashion, technology or perishable goods, higher for commodities with a liquid market.
- Prepaid expenses and other current assets: often zero, since many cannot be sold.
Read the notes before choosing a haircut. The receivables note shows the allowance for doubtful accounts and aging. The inventory note splits raw materials, work in progress and finished goods and shows reserves for obsolete stock. A company that just raised its inventory reserve is telling you something about realizable value.
Worked example: Company B
The numbers below are illustrative. Company B is hypothetical.
Company B's latest 10-Q balance sheet shows:
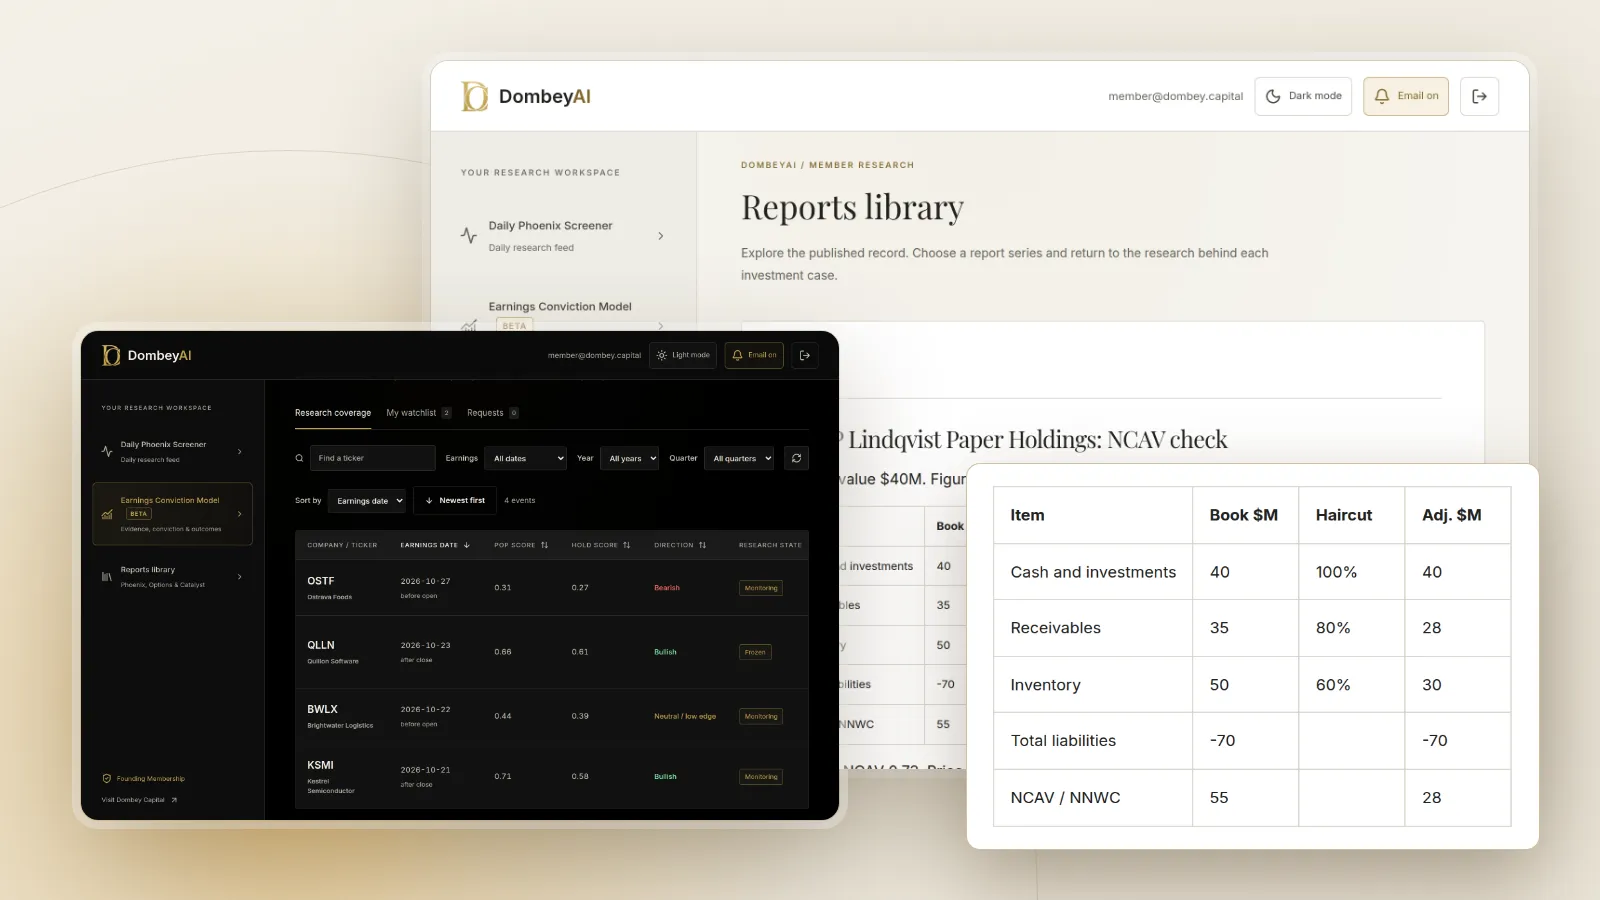
| Line item | Book value ($M) | Haircut | NNWC value ($M) |
|---|---|---|---|
| Cash and short-term investments | 40 | 100% | 40 |
| Accounts receivable | 30 | 80% | 24 |
| Inventory | 50 | 60% | 30 |
| Prepaid and other current | 5 | 0% | 0 |
| Total current assets | 125 | 94 |
Total liabilities are $70 million: $35 million of current liabilities and $35 million of long-term debt and leases. There is no preferred stock. Diluted shares are 20 million, and the share price is $2.00, for a market value of $40 million.
NCAV. $125M - $70M = $55M, or $2.75 per share. Price to NCAV is $2.00 / $2.75 = 0.73. Company B is a net-net, but it misses the two-thirds test, which would require a price of $1.83 or less.
NNWC. $94M - $70M = $24M, or $1.20 per share. On haircut values the stock trades at 1.67 times its liquid floor. The discount disappears.
After cash burn. Company B used $4 million of operating cash per quarter over the last year. If the most plausible catalyst is a sale process expected to take three quarters, the burn is $12 million. NCAV falls to $43 million, or $2.15 per share, and the stock now trades at 0.93 times NCAV.
The headline ratio of 0.73 looked like a wide margin. After a reasonable view of inventory and nine months of losses, the margin was close to nothing. That pattern is typical, which is why the adjustments matter more than the formula.
Why net-nets exist
A company priced below its current assets after paying every debt looks like an error. Usually the market has a reason.
Losses. The most common cause. A business losing money converts current assets into expenses each quarter. The market prices in the NCAV the company will have later, not the one it has today.
Doubtful asset quality. Inventory that is obsolete or receivables from a struggling customer may be worth far less than book. The market may be applying its own haircut.
Capital allocation. Management may hold the assets indefinitely, spend them on acquisitions, or pay itself generously. Value that never reaches holders is worth less to them.
Neglect and forced selling. Small companies with no analyst coverage, recent index removals, tax-loss selling and delisting risk can push a price below NCAV for reasons unrelated to value. These are the cases where the discount is more likely to be real.
The discount closes only through a path such as a buyback, a tender offer, a sale, an activist campaign, a return to profit or a liquidation. Without one, a net-net can stay a net-net for years.
How to screen for NCAV stocks
Few screeners calculate NCAV directly, and those that do use stale or standardized data. A practical approach:
- Screen for low price to book and low debt, or for a high ratio of current assets to market value. The 10 best free stock screeners covers tools with balance-sheet filters.
- For each candidate, pull the latest balance sheet from the 10-Q or 10-K on SEC EDGAR and compute NCAV by hand.
- Read the receivables, inventory, debt, lease and commitments notes, then compute NNWC.
- Subtract the expected cash burn until a dated catalyst.
- Check for dilution: warrants, convertibles and any shelf registration that could fund losses with new shares.
How to find stocks trading below net cash walks through the same process with the stricter cash-only floor, and how to value a company below book covers marking long-term assets when you want to give them some value. Dombey's published research runs this kind of balance-sheet floor before each catalyst; see the research archive.
Where this goes wrong
NCAV has clear limits.
- The balance sheet is a snapshot. It reflects the last day of the quarter. A seasonal business may look very different a month later.
- Off-balance-sheet obligations. Purchase commitments, guarantees, environmental costs, pending litigation and severance in a wind-down do not appear as liabilities but consume current assets.
- Liquidation costs. Closing a business costs money: legal fees, retention bonuses, lease exits and taxes. A formal wind-down rarely returns the full NCAV to holders.
- Dilution. A company funding losses by issuing shares lowers NCAV per share even when total NCAV holds steady.
- It ignores earning power. A profitable company with a small balance sheet will never screen as a net-net, and a net-net with collapsing sales may be worth less than NCAV. The measure suits asset-heavy, troubled or neglected companies and says little about service or software businesses.
- No catalyst. A discount without a path to realize it is a value trap. Compare with negative enterprise value stocks, which share the same problem.
The bottom line
Net current asset value is current assets minus all liabilities and preferred stock, a floor that gives no credit for long-term assets. A stock below NCAV per share is a net-net, and Graham's classic test looked for a price at or below two-thirds of that figure. Haircut receivables and inventory, subtract cash burn until a dated catalyst, and check for dilution before trusting the ratio. A stock that still trades below adjusted NCAV is a reason to read the filings closely, not a conclusion.