

Nov 3, 2026: a premarket climb, a gap at the open and a hold above $10.50
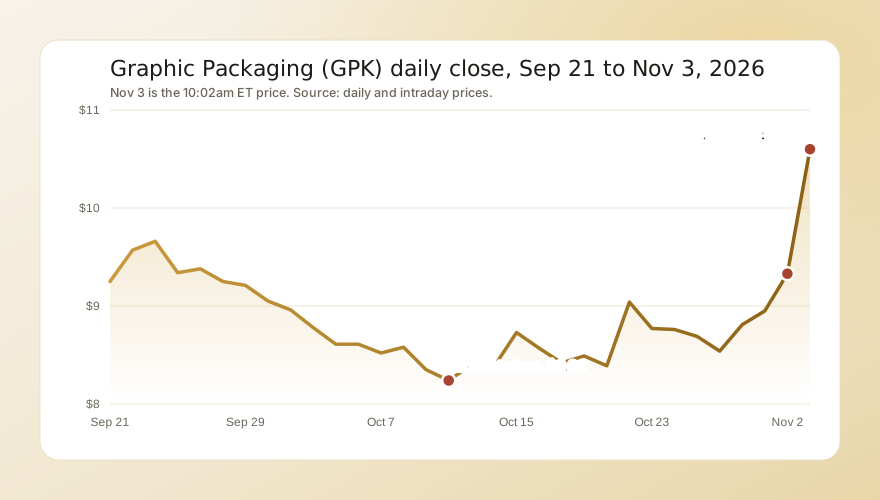
Graphic Packaging closed at $9.33 on Nov 2, up 4.2% on the day. The release came at 6:30am ET, and the shares traded at $9.40 at that time. They climbed through the morning, reaching $10.18 by 7:30am and a premarket high of $10.39 at 9:05am. The stock opened at $10.67 and the first five-minute bar ran from $10.17 to the day's high of $11.00. From 9:35am it traded in a narrow band of $10.56 to $10.66, and it was $10.60 at 10:02am, up 13.6%, on 2.0 million shares. The earnings call began at 10:00am ET.
The move reverses a slide, though not the whole of it. The shares fell from $9.66 on Sep 23 to a closing low of $8.24 on Oct 12 and traded as low as $8.15 on Oct 22. After the move, RSI(14) stood at 72, the shares sat 13% above their 50-day average and level with their 200-day average, and volume ran 0.3 times its 20-day average with the session still young. They remain 38% below the 52-week high of $17.22.
What happened:
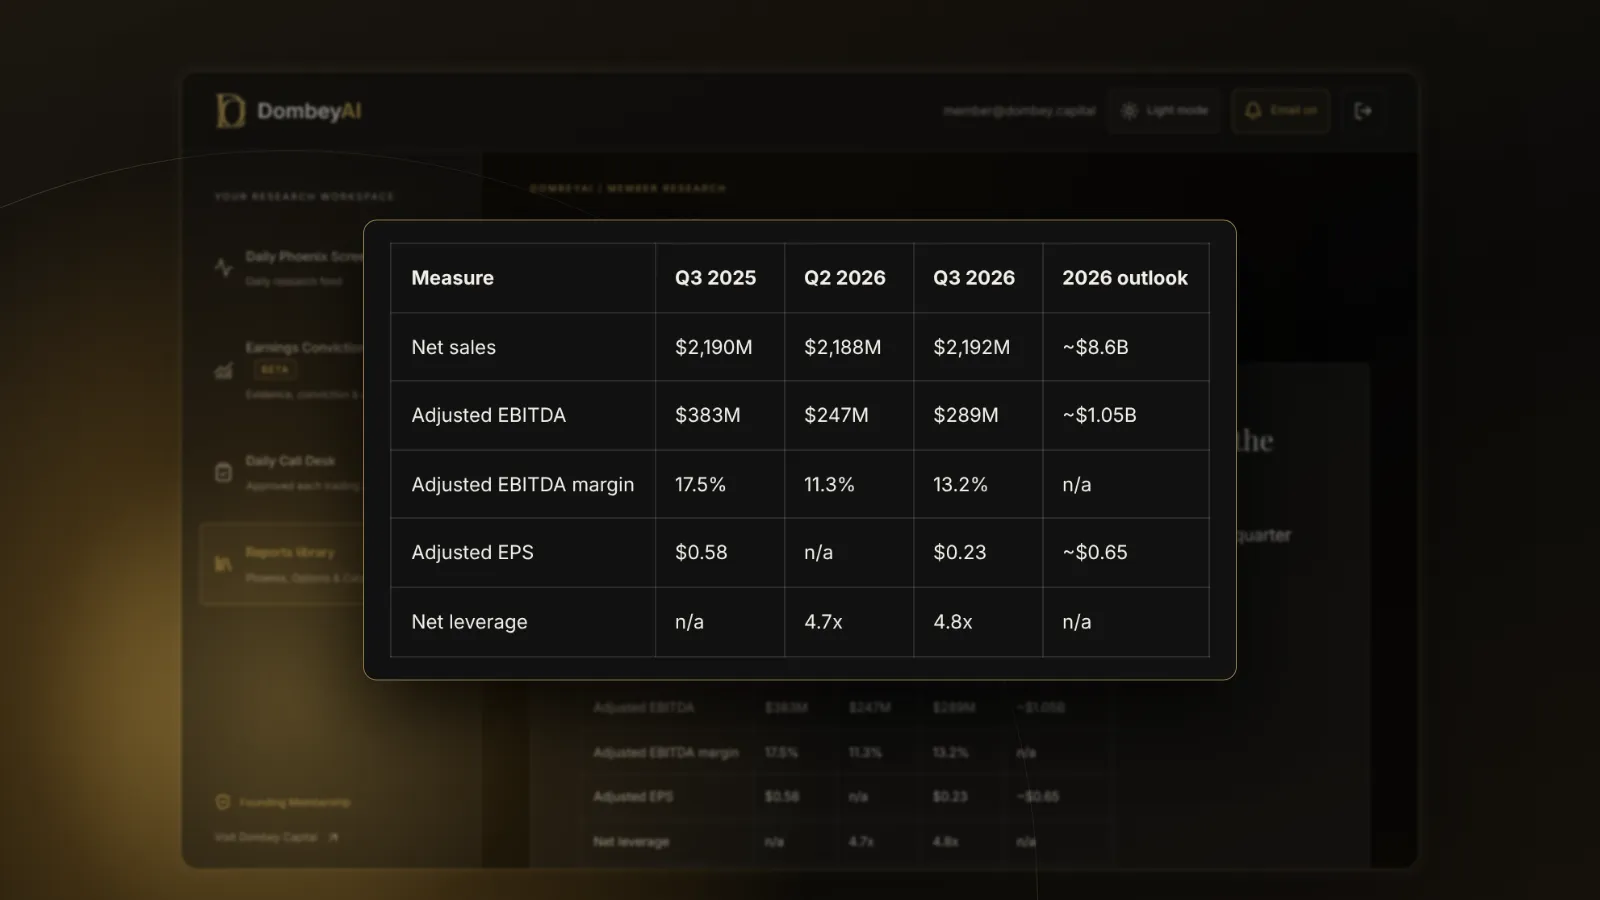
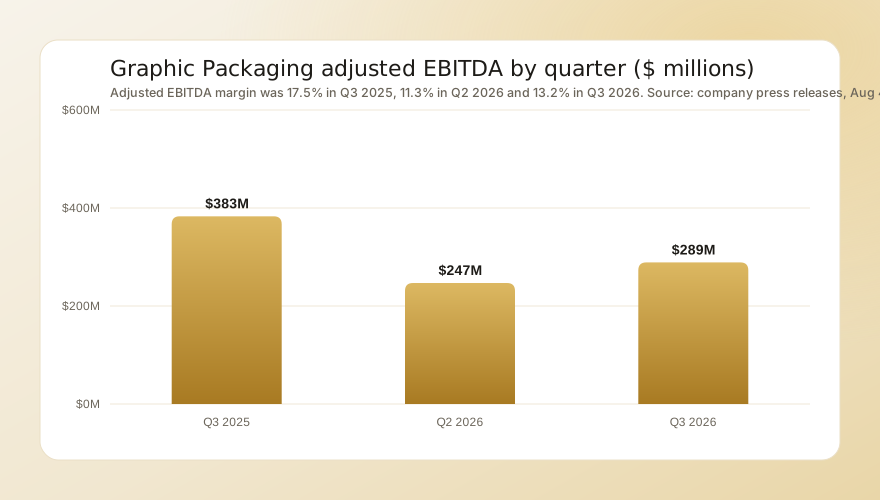
- Margins improved from a low base. Adjusted EBITDA of $289 million compares with $247 million in the second quarter and $383 million a year earlier. The adjusted margin was 13.2%, up from 11.3% and down from 17.5%.
- Cost inflation still did the damage. The $94 million year-over-year decline in adjusted EBITDA came from $83 million of higher commodity input and operating cost inflation and $15 million of lower price, with $3 million from volume and mix. Net performance added $2 million and currency $5 million.
- Profit per share is well below last year. Net income was $22 million, or $0.07 a share, against $142 million, or $0.48. Adjusted EPS of $0.23 compares with $0.58 a year ago.
- The outlook held. Management expects 2026 net sales of about $8.6 billion, adjusted EBITDA of about $1.05 billion and adjusted EPS of about $0.65, the top, bottom and bottom of the ranges set in August. It reaffirmed adjusted cash flow of $600 million to $700 million, up from $169 million in 2025.
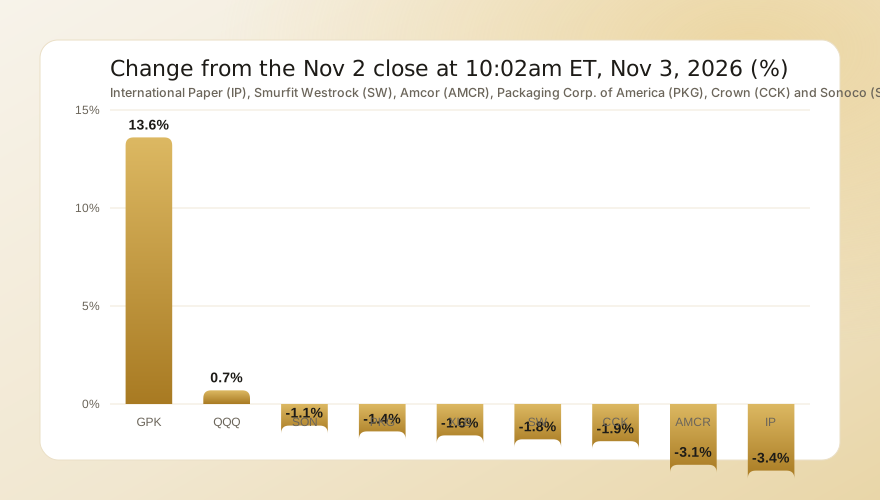
- Peers fell. International Paper dropped 3.4%, Amcor 3.1%, Smurfit Westrock 1.8%, Crown 1.9%, Packaging Corp. of America 1.4% and Sonoco 1.1%, against 1.6% for the materials fund XLB and a 0.7% gain for the Nasdaq 100 fund QQQ.
What the numbers say
The quarter was a beat only in a narrow sense. Sales and EPS came in close to estimates, and sales were flat on a year earlier. What changed the mood was the direction of the margin. CEO Robbert Rietbroek said the company expanded its adjusted EBITDA margin sequentially for the second consecutive quarter, that structural cost cuts and productivity gains have produced positive operating leverage, and that it expects to capture price improvements in the fourth quarter and into 2027, with a return to EBITDA growth next year. For how to read a release like this one, see how to read an earnings release.
Cash is the strongest part of the report. Net cash from operations was $295 million for the nine months, and adjusted cash flow of $314 million is $646 million above the same period of 2025, helped by capital spending of $287 million against $808 million. Net debt of $5,183 million is $148 million below year-end and $300 million below the end of June. Gross debt is $5,520 million, with cash of $337 million.
The leverage ratio went the other way. Net leverage was 4.8 times at Sept 30, against 4.7 times at June 30 and 3.8 times at year-end, because the earnings base shrank faster than debt fell. Interest expense rose to $69 million in the quarter from $53 million. Of the debt, $854 million is due within a year or is the current portion of longer debt, which makes refinancing risk a live question if earnings do not recover.
The outlook needs a look too. Adjusted EPS of $0.09 in the first quarter, $0.14 in the second and $0.23 in the third adds to $0.46, so the $0.65 outlook leaves about $0.19 for the fourth quarter. That is below the third quarter even though management expects price gains. The comparison with last year is also hard: the company earned $0.58 in the third quarter of 2025. For how outlook changes move stocks, see our guide to guidance changes.
The bull case
- The margin is recovering. Two straight quarters of sequential margin gains, from 11.3% to 13.2% in the last one, suggest the cost program is working while inflation continues.
- Debt is falling. Net debt is down $300 million in a quarter, and capital spending of $64 million against $267 million a year ago leaves cash for repayment. The 2026 cash flow target of $600 million to $700 million is intact.
- Prices should help. Price was a $15 million drag in the quarter, but management is counting on gains in the fourth quarter and 2027.
- The valuation is low. The stock trades at about 0.97 times book value and 0.36 times sales, and the forward P/E is about 11. See our explainers on price to book and price to sales.
- Estimates can rise. If the margin trend holds, estimate revisions could follow. The consensus price target is $10.13, within a range of $9 to $13.
The risks
- Guidance at the bottom. Both EBITDA and EPS sit at the low end of the August ranges, and the implied fourth-quarter EPS is lower than the third quarter's.
- Leverage. At 4.8 times net debt to EBITDA, a small miss in earnings has a large effect on equity. Interest costs are rising.
- Price still falling. Price reduced sales by 1% in the quarter. A price increase has to stick in a market where input costs, not demand, are the pressure.
- The dividend. The $0.44 annual dividend is a yield of about 4%, and it uses a large part of adjusted EPS of about $0.65. See what dividend cuts signal.
- A crowded bounce. About 9% of the float is sold short, and the rally has put the stock above the average target. If shorts cover and then stop, the move can fade.
What comes next
The next dated test is the fourth-quarter report, which should carry the 2027 outlook. A calendar estimate puts it on February 2, 2027, but the company has not announced a date. Watch the adjusted EBITDA margin against 13.2%, net leverage against 4.8 times, and whether price increases show up as positive price in the sales bridge. The company will also file its quarterly report with the SEC, which gives debt maturities in full. To follow the call, read how to analyze an earnings call transcript. More of today's biggest stock moves are on our market page, and our published work is in the research archive.