

Nov 17, 2026: an early 3.8% drop, a quick recovery, then a fade
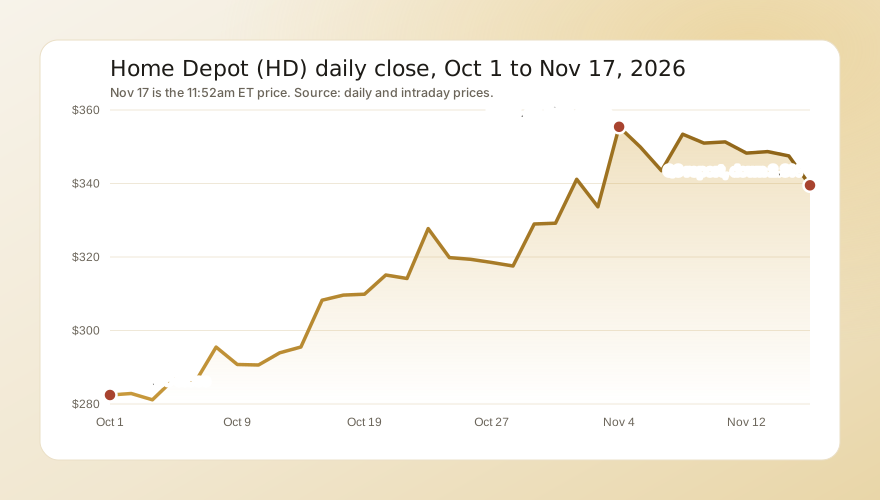
Home Depot closed Monday, Nov 16, at $347.51. Extended trading that evening ended at $344.35. The release came before the open on Tuesday, and premarket trading first rose to $353.00 at 6:25am, 1.6% above the close, as the beat registered. It then slid as investors read the outlook, reaching $334.01 at 9:25am, 3.9% lower.
The stock opened at $335.07, touched $334.44 in the first minutes and rallied to $346.90 by 9:50am, 0.2% below the close. It faded from there with the broader market, which fell through the late morning. At 11:52am it was $339.52, down 2.3%, on 2.8 million shares.
What pushed it down:
- Profit at the low end. Adjusted earnings per share are now guided up about 2%, against a prior range of flat to 4%, and the operating margin to about 12.4%, the bottom of its prior 12.4% to 12.6% range, Zacks reported.
- A soft fourth quarter. Full-year comparable sales of about 1.4% imply about 1% in the fourth quarter, against the 1.5% the Street expected, by Zacks's math.
- Fewer shoppers. Comparable transactions fell 0.5% while the average ticket rose 3.0% to $93.09. 24/7 Wall St. pointed to the drop in transactions as a reason the shares fell despite the beat.
- A leadership change. McPhail replaces Ted Decker, who returned from medical leave and will stay as chair. McPhail told CNBC, "We're not going to change course."
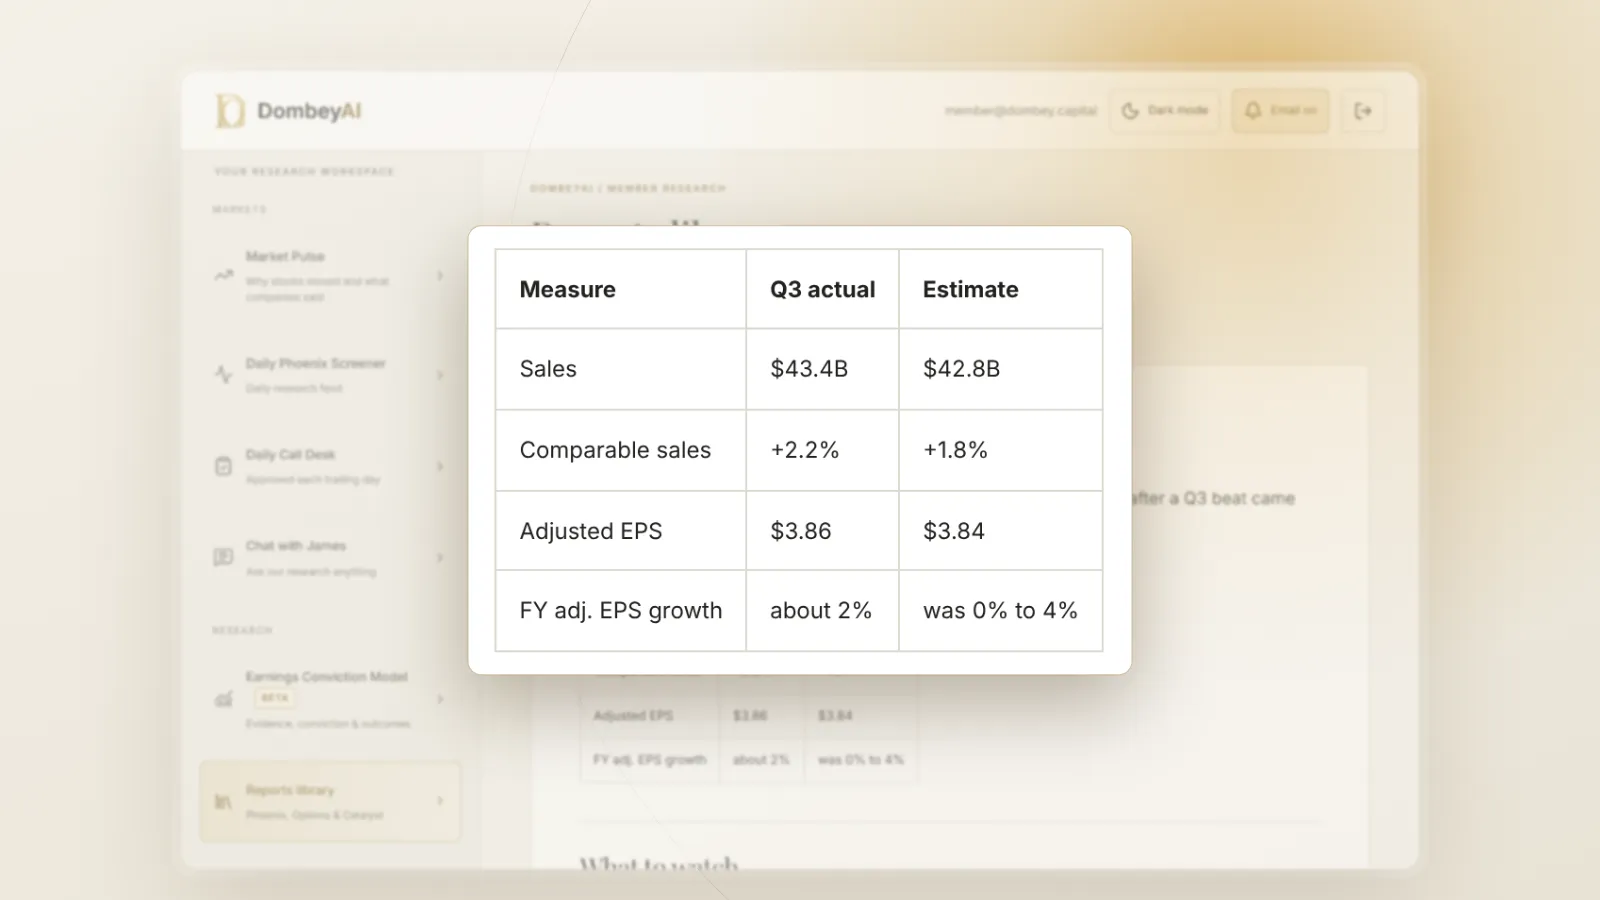
What helped it recover: the beat itself. Sales of $43.4 billion topped the $42.8 billion LSEG estimate and comparable sales of 2.2% topped the 1.8% StreetAccount estimate, CNBC reported, and the full-year sales guide of about 4.5% sits at the top of the prior 2.5% to 4.5% range.
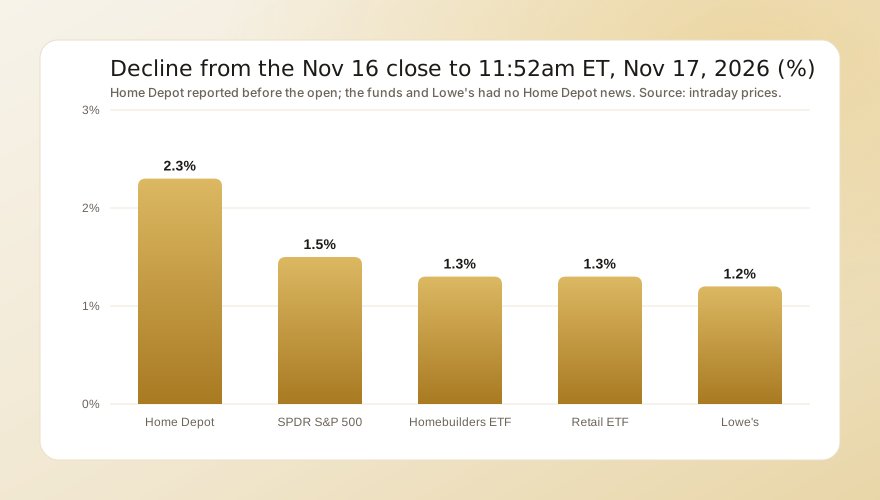
Home Depot fell about one point more than Lowe's and the retail and homebuilder funds, which slid with the S&P 500 as the Nasdaq 100 fund QQQ fell 1.7% ahead of Nvidia's report after the close. Our explainer on why guidance changes move stocks covers why an outlook can matter more than the quarter, and the rest of the session's movers are in today's biggest stock moves.
After the drop, RSI(14) stood at 56, the shares sat 8% above their 50-day average and 2% above their 200-day average, volume of 2.8 million shares by midday was 0.6 times the 20-day average, and the stock was 15% below its 52-week high of $397.63.
The numbers
| Measure | Q3 fiscal 2026 | Q3 fiscal 2025 |
|---|---|---|
| Sales | $43.40B | $41.35B |
| Comparable sales | +2.2% | +0.2% |
| Comparable transactions | -0.5% | |
| Average ticket | $93.09 | $90.39 |
| Diluted EPS | $3.72 | $3.62 |
| Adjusted diluted EPS | $3.86 | $3.74 |
| Operating margin | 12.6% | 12.9% |
Net earnings rose 3.1% to $3.71 billion, slower than sales, because the gross margin fell to about 32.8% from about 33.4%. Zacks estimates that acquisitions, led by SRS, added about 2.5 points of sales growth. For the full year Home Depot now guides a gross margin of about 33.0%, an effective tax rate of about 24.6% and net interest expense of about $2.2 billion. Our guide to reading an earnings release shows where to find the transaction and ticket figures that drove the reaction, and our explainer on what gross margin changes signal covers why a 0.6 point drop matters at this scale.
The bull case
The quarter was Home Depot's best comparable sales result of the year, and it came in a weak housing market: Zacks cites existing home sales of 3.75 million, down 8.8% from a year earlier, and a 30-year mortgage rate that averaged 7.33% in October. McPhail told CNBC the company is taking "material share" from competitors, comparable sales were positive in 13 of 16 merchandising departments, and online sales have grown at double digits for six straight quarters. The professional customer, which SRS serves, has held up better than the do-it-yourself shopper. The consensus target of $380.73 sits about 12% above the 11:52am price, and a new chief executive who was finance chief knows the cost lines well.
The risks
- Valuation. Home Depot trades at about 23 times forward earnings against about 18 for Lowe's, Zacks reported, while its earnings are guided to grow about 2% this year.
- Margin pressure. The gross margin is down and the full-year operating margin is at the bottom of its range, so higher sales are not reaching profit.
- Traffic. Transactions have fallen in the second and third quarters, and a higher ticket can reflect prices as much as demand.
- Leadership change. A new chief executive, a new chief operating officer and a new finance chief all start at once. Our explainer on how chief executive departures move stocks covers what usually follows.
What comes next
- Lowe's third-quarter report, Nov 18. The consensus is $2.88 a share. Its comparable transactions are the cleanest read on whether Home Depot's traffic problem is industry wide.
- McPhail takes over, Nov 23. Any early word on margins or the fourth quarter would test the guide.
- Fourth-quarter results, expected in late February 2027. The first full quarter under McPhail, and the first fiscal 2027 outlook.