

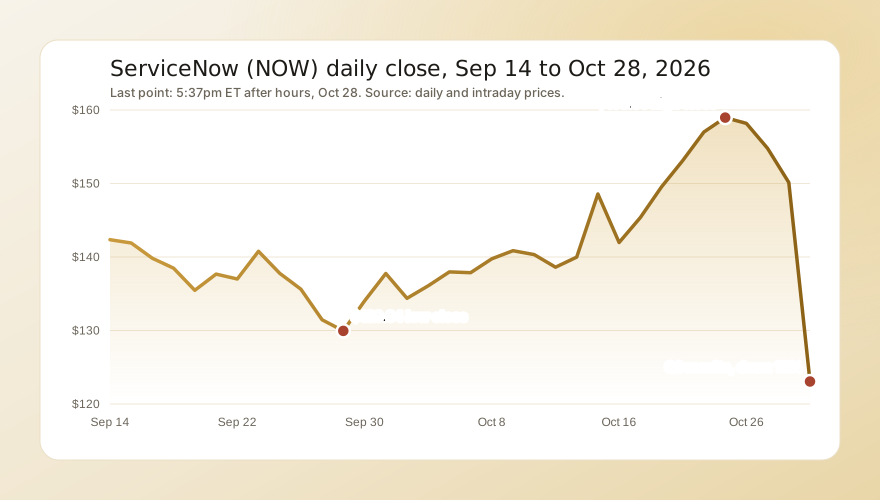
Oct 28, 2026: a soft session, then an 18% drop after the release
ServiceNow opened near $152.60 and drifted lower all day, closing at $150.13, down 3.0% from $154.78. Volume was 26.3 million shares, 2.3 times its 20-day average, before the results came out. The release crossed at 4:10pm ET. By 4:15pm the stock was $126.81, it bounced to about $128 at 4:40pm, and it slid again after the call began at 5pm, touching $121.48 at 5:24pm before trading at $123.06 at 5:37pm. At that price the shares sat about 12% below their 50-day average of $139.53 and about 7% above their 200-day average of $115.28, and about 36% below the 52-week high of $192.97.
What pushed it down:
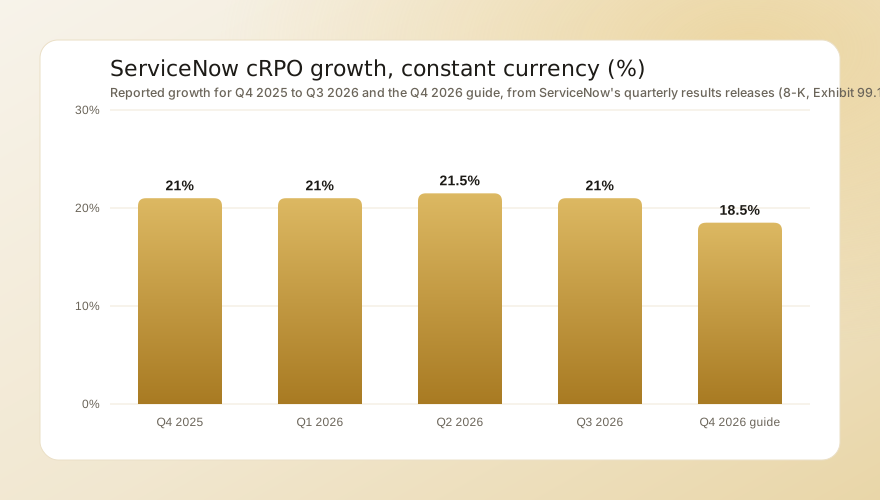
- A slower backlog guide. Fourth-quarter cRPO growth of 18.5% in constant currency compares with 21% in the third quarter, 21.5% in the second and 21% in the first. cRPO is the closest thing to a preview of next year's subscription revenue, so a step down reads as slower growth in 2027.
- A small earnings miss. Adjusted earnings of $1.00 a share missed the $1.02 consensus, Reuters reported, and 24/7 Wall St. noted it ended a run of six straight quarterly beats. GAAP earnings fell to $0.27 a share from $0.48 as acquisition costs, amortization and financing expense rose.
- Thinner margins. The non-GAAP subscription gross margin was 80%, against 83% a year earlier, and the GAAP operating margin fell to 9.5% from 17%. In July the company said more customers running on hyperscaler partnerships and faster AI adoption would weigh on gross margin.
- A bad night for software. Alphabet fell after its own results in the same hour (see why Alphabet stock fell), and software stocks sold off with ServiceNow. At about 5:35pm:
| Stock or fund | Oct 28 close | After hours | Change |
|---|---|---|---|
| ServiceNow (NOW) | $150.13 | $123.06 | -18.0% |
| Alphabet (GOOGL) | $324.89 | $290.18 | -10.7% |
| Salesforce (CRM) | $242.11 | $227.01 | -6.2% |
| Workday (WDAY) | $204.36 | $195.03 | -4.6% |
| iShares Expanded Tech-Software (IGV) | $111.91 | $107.05 | -4.3% |
| Adobe (ADBE) | $249.76 | $241.82 | -3.2% |
| Microsoft (MSFT) | $531.01 | $549.00 | +3.4% |
ServiceNow fell about three to four times as much as its software peers, so the cRPO guide, not the sector, explains most of the move. We covered earlier software selloffs on the same AI worry in why Wix stock fell and why Palantir stock fell.
The numbers against the guide
ServiceNow guides conservatively, and the third quarter followed the pattern. Every growth figure landed above the range it set in July:
| Measure | Q3 guide (July) | Q3 actual | Q4 guide (Oct 28) |
|---|---|---|---|
| Subscription revenue | $3.975B to $3.98B | $3.988B | $4.245B to $4.255B |
| Subscription growth, constant currency | 20% | 20.5% | 21.5% |
| cRPO growth, constant currency | 20% | 21% | 18.5% |
| Non-GAAP operating margin | 31% | 32.5% | 32% |
| Full-year subscription revenue | $15.76B to $15.78B | n/a | $15.78B to $15.79B |
| Full-year free cash flow margin | 35% | n/a | 36% |
Two details matter. First, the subscription revenue guide for the fourth quarter, 21.5% in constant currency, is faster than the third quarter's 20.5%; in July the company said strong U.S. federal demand pulled some on-premise revenue from the third quarter into the second, which flattered one quarter and held back the next. Second, total remaining performance obligations, which include contracts beyond 12 months, grew 22.5% in constant currency to $29.7 billion, faster than cRPO. Customers are signing longer commitments even as the 12-month figure slows. For how markets weigh a guide like this, see why outlooks move stocks, and for how estimates shift after it, earnings estimate revisions.
The case for the stock
- The guide has been a floor. In 2026 ServiceNow guided cRPO growth to 20%, 19.5% and 20%, and reported 21%, 21.5% and 21%. A beat of the same size would put fourth-quarter growth near 19.5% to 20.5%.
- AI is adding contracts, so far. The company raised its 2026 target for AI annual contract value to $1.7 billion, from $1 billion at the start of the year. It signed 19 deals worth more than $5 million in net new annual contract value, up more than 135%, and ended the quarter with 680 customers above $5 million, up from 553. The renewal rate was 98%.
- Cash flow is rising. The full-year free cash flow margin target went to 36% from 35%, and CFO Gina Mastantuono said capital spending was cut.
- The price already assumes a slowdown. At $123.06 the stock trades near 24.5 times forward earnings, down from about 30 times at the close and 32 times next-year earnings a day earlier, Reuters reported. The market value fell to about $127 billion. Our forward vs trailing P/E guide covers why the forward figure is the one to watch here.
The risks
- The slowdown may be real. If the fourth quarter only meets 18.5%, it would be the slowest cRPO growth of the last five quarters and would point to subscription growth below 20% in 2027.
- Margins are moving the wrong way. AI workloads and hyperscaler hosting cost more to run. The subscription gross margin is three points lower than a year ago, and acquisitions cut GAAP operating margin to 9.5%.
- The AI debate cuts both ways. ServiceNow sells AI agents that automate help desk and back-office work. Bloomberg reported that the outlook revived fears that AI disrupts software sellers, and if customers need fewer seats, growth slows even as AI sales rise.
- The rally left room to fall. The stock rose about 63% from its July low into the report, so some of the after-hours drop is the market taking back that gain, and it may not be finished.
For how to read the release and the call behind a move like this, see how to read an earnings release and how to analyze an earnings call transcript, and more of today's biggest stock moves.
What comes next
- The regular session on Oct 29. After-hours prices move on thin volume, so the open will show where the first wave of selling settles.
- Analyst updates. Target and estimate changes are likely over the next days. The median target was $162.45 before the report, Reuters reported.
- Investor conferences. Management speaks at BMO on Nov 12, RBC on Nov 17, Wells Fargo on Dec 8 and Barclays on Dec 9, where cRPO and 2027 demand will come up.
- Fourth-quarter results in late January. The cRPO print against 18.5% and the first 2027 subscription guide decide the view.
Dombey's published work on event-driven moves is in the research archive.