

Nov 5, 2026: Recorlev nearly doubles and the outlook goes up twice
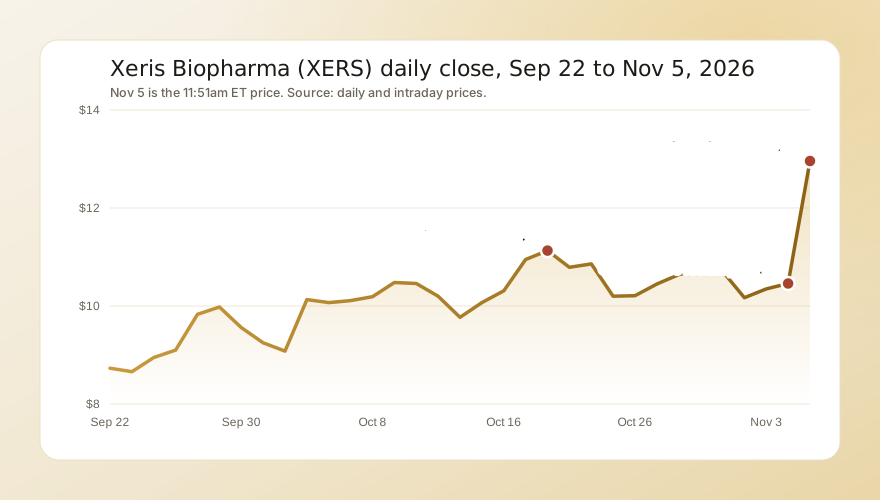
Xeris closed Nov 4 at $10.46 and released results at 7:00am ET on Nov 5. Premarket trading started near $10.55 and reached $12.56 by 9:25am. The stock opened at $12.51, made its low of $12.32 at 9:30am and its high of $13.74 at 9:35am, a new 52-week high. At 11:51am it was $12.96 on about 5.6 million shares.
What moved it:
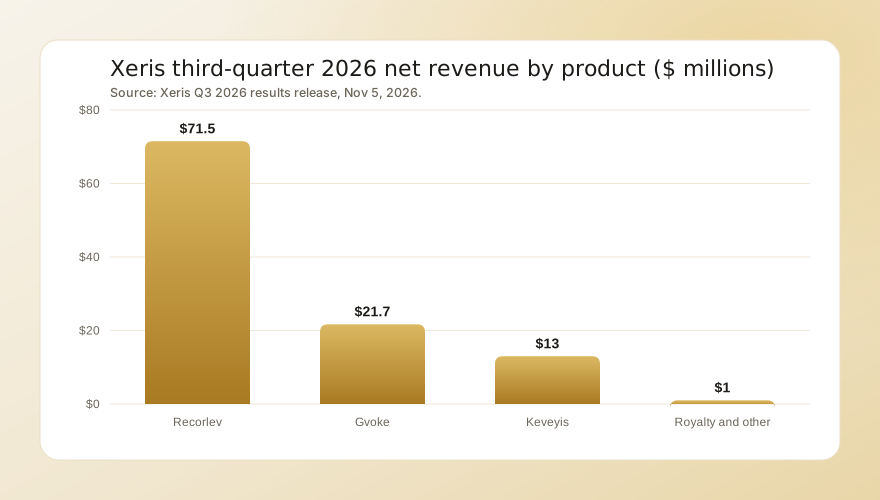
- Recorlev kept speeding up. Net revenue of $71.5 million was up 93% from a year earlier and up from $56.8 million in the second quarter. Chief executive John Shannon said Recorlev is now on a path to nearly $1 billion in annual net revenue three to four years sooner than previously expected.
- The 2026 guide went up again. The new range of $395 million to $405 million compares with $385 million to $390 million set on Aug 6.
- 2030 went up by a third. "We are now on a path to reach more than $1 billion in total revenue in 2030," Shannon said, against a prior outlook of about $750 million.
- Profit arrived. Net income was $11.3 million, against $0.6 million a year earlier, and adjusted EBITDA rose to $30.8 million from $17.4 million. Earnings of $0.06 a share compared with a consensus of about $0.03.
The move was company news. Biotech stocks fell with the wider market, with XBI down 5.3% and the S&P 500 fund SPY down 3.2% over the same period. The rest of the session's movers are in today's biggest stock moves.
At 11:51am RSI(14) stood at 75, the shares sat 37.1% above their 50-day average and 71.9% above their 200-day average, volume was already 2.5 times its 20-day average, and the stock was 5.3% below the 52-week high it set that morning.
The numbers
| Measure | Q3 2026 | Change from a year earlier |
|---|---|---|
| Total revenue | $107.2 million | +44% |
| Recorlev | $71.5 million | +93% |
| Gvoke | $21.7 million | -14% |
| Keveyis | $13.0 million | +9% |
| Gross margin | 88% | from 85% |
| Adjusted EBITDA | $30.8 million | from $17.4 million |
For the first nine months revenue rose 37% to $282.5 million. The nine-month net loss of $17.6 million includes a one-time, non-cash charge of about $30.8 million in the second quarter tied to exchanging its 2028 convertible notes. Xeris ended September with $131.1 million of cash and $189.7 million of long-term debt. Our guide to guidance changes covers why a raise on top of a beat tends to move a stock, and our page on adjusted EBITDA covers what the adjusted figure leaves out.
The bull case
Recorlev is a rare-disease drug with a long runway, and the numbers show the launch is still building rather than leveling off. Its sales added $14.7 million from the second quarter to the third, and the raised guide implies more growth in the fourth. Xeris also has patent news on its side: a third U.S. patent for XP-8121 was granted on Oct 6, expected to run to 2043, and a new Keveyis patent issued on Oct 13 is expected to protect it through at least 2043. The pivotal Phase 3 study of XP-8121, a once-weekly levothyroxine injection, is due to start by the end of 2026. Our page on earnings estimate revisions covers why a guide raise this large usually pulls analyst estimates and targets up behind it, and our page on post-earnings announcement drift covers why the move often continues.
The risks
One drug now carries the story. Recorlev is two thirds of revenue, and Gvoke fell 14%, so any slowdown in Recorlev prescriptions or pricing would show up quickly. XP-8121 is years away: topline data are expected in late 2028 and a possible launch in 2030, so it adds little before then. The stock has already risen from $5.25 at its 52-week low, it trades near the $15 average target and the $16 high, and a gain this fast can fade on any weak day for biotech. Debt of $189.7 million is more than its cash, although the company is now profitable. Our guide to estimating cash runway covers how to judge a balance sheet like this.
What comes next
The fourth-quarter report is expected around March 1, 2027, with 2027 guidance. Before then, watch whether analysts raise targets above $16, whether the stock holds above the $10.46 close it gapped from, and the start of the XP-8121 Phase 3 study by year end. Fourth-quarter revenue below $112.5 million or a drop in Recorlev sales would undercut the Bullish case.