

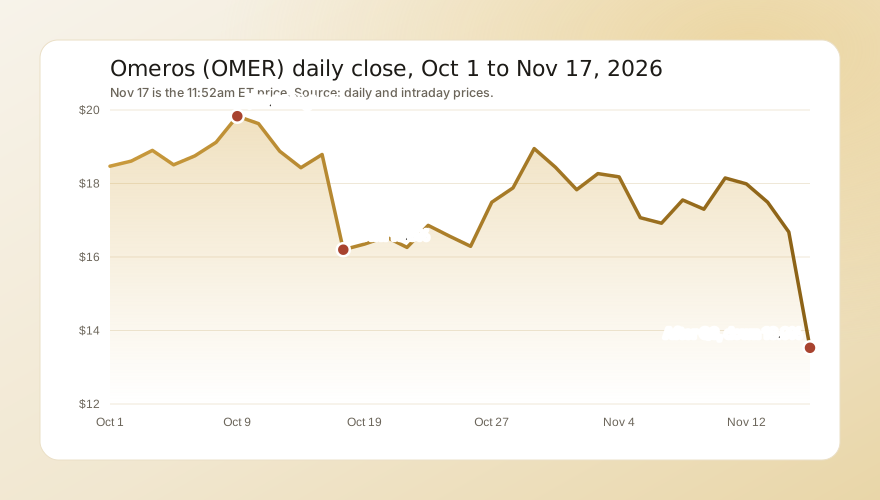
Nov 17, 2026: a 13% drop after hours, then a lower open
Omeros closed Monday, Nov 16, at $16.68 and released its results at 4:02pm, with a call at 4:30pm. The stock fell to $14.45 in the first 10 minutes of extended trading, 13.4% below the close, and recovered to $15.40 by 7:55pm. Investing.com reported a 10.4% after-hours drop and pointed to the GAAP loss, the widening gross-to-net adjustment and the European opinion.
Premarket trading on Tuesday opened at $15.52 and slid all morning to $14.50 at 9:25am, 13.1% lower. The stock opened at $14.50, fell to $12.96 in the first five minutes, 22.3% below the close, and recovered part of that. At 11:52am it was $13.53, down 18.9%, on 2.2 million shares, already more than twice its 20-day average for a full day. The SPDR S&P Biotech ETF was down 1.4%.
What pushed it down:
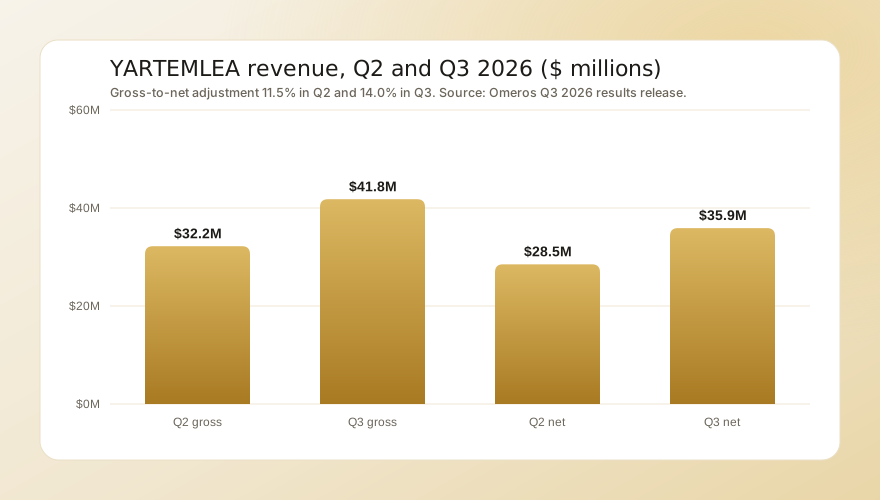
- A wider discount. The gross-to-net adjustment rose 2.5 points to 14.0%. Demopulos said on the call that "somewhere in the high teens would be what we would think we might be approaching at some point."
- A GAAP loss. The $62.0 million derivative charge turned a second-quarter profit of $13.2 million into a $57.4 million loss.
- No guidance. Asked by Needham's analyst about 2027, Demopulos said guidance would begin "at some point in 2027." Operating expenses will be "slightly higher" in the fourth quarter, chief accounting officer Borges said.
- Europe. The Committee for Medicinal Products for Human Use confirmed its negative opinion after re-examination in October, and Omeros is closing its compassionate use program to new patients.
What limited the damage: adjusted net income of $4.7 million, or $0.06 a share, beat forecasts, and Demopulos said "we are seeing continued growth in Q4."
The rest of biotech fell far less, so the selling was about Omeros's own report. Our explainer on earnings estimate revisions covers how a quarter with no guide can still move estimates, and the rest of the session's movers are in today's biggest stock moves.
After the drop, RSI(14) stood at 30, the shares sat 25% below their 50-day average and 2% below their 200-day average, volume ran 2.2 times its 20-day average, and the stock was 36% below its 52-week high of $21.24.
The numbers
| Measure | Q3 2026 | Q2 2026 |
|---|---|---|
| YARTEMLEA gross revenue | $41.8M | $32.2M |
| YARTEMLEA net revenue | $35.9M | $28.5M |
| Gross-to-net adjustment | 14.0% | 11.5% |
| Operating income | $4.5M | $0.1M |
| GAAP net income (loss) | ($57.4M) | $13.2M |
| Adjusted net income | $4.7M | $1.8M |
| Operating cash flow | $13.3M | |
| Cash and short-term investments | $95.3M |
Research and selling expenses rose to about $30.6 million from $27.7 million. In July Omeros repurchased $30.5 million of its 2029 notes for $60.2 million, which left about $40.3 million outstanding and cut the shares issuable on conversion to 6.5 million from 11.4 million. The derivative charge will disappear once those notes are gone, Demopulos said. Our guide on reading a cash flow statement shows why operating cash flow is the cleaner measure here, and our explainer on convertible arbitrage covers how convertible notes trade against the stock.
The bull case
YARTEMLEA is the only approved treatment for transplant-associated thrombotic microangiopathy, an often-fatal complication of stem cell transplants, and its sales are still climbing. Since Oct 1, hospitals can claim up to $287,079 of extra Medicare payment per eligible inpatient case through the NTAP program, and from Jan 1, 2027 Medicare's outpatient payment for 340B-bought YARTEMLEA improves, which supports the shift to outpatient use that is widening the discount today. Demopulos told analysts that "the 340B discount has no impact on our ASP," the average selling price that sets Medicare payment. Novo Nordisk is moving zaltenibart toward Phase 3, and Omeros is eligible for up to $100 million in near-term milestones and more than $1.8 billion in total. The consensus price target of $27.50 is about twice the 11:52am price.
The risks
- Net price. A discount in the high teens would mean net revenue grows several points slower than gross revenue.
- No guidance. Investors will judge each quarter without a company number until some time in 2027.
- Europe. The negative opinion leaves Omeros dependent on the U.S. market and named-patient programs elsewhere.
- Investor claims. Pomerantz LLP said on Nov 5, 10 and 12 that it is investigating claims on behalf of Omeros investors. Our explainer on securities class actions covers what such notices usually mean for a stock.
What comes next
- Medicare outpatient payment change, Jan 1, 2027. Favorable outpatient reimbursement for 340B-acquired YARTEMLEA begins.
- Novo milestones. Up to $100 million in near-term payments as zaltenibart moves toward Phase 3.
- New studies. Investigator studies in ARDS and in preventing TA-TMA are expected to start in late 2026 or early 2027.
- Fourth-quarter results, estimated for March 2027. Net revenue, the gross-to-net adjustment and whether cash flow stays positive.