

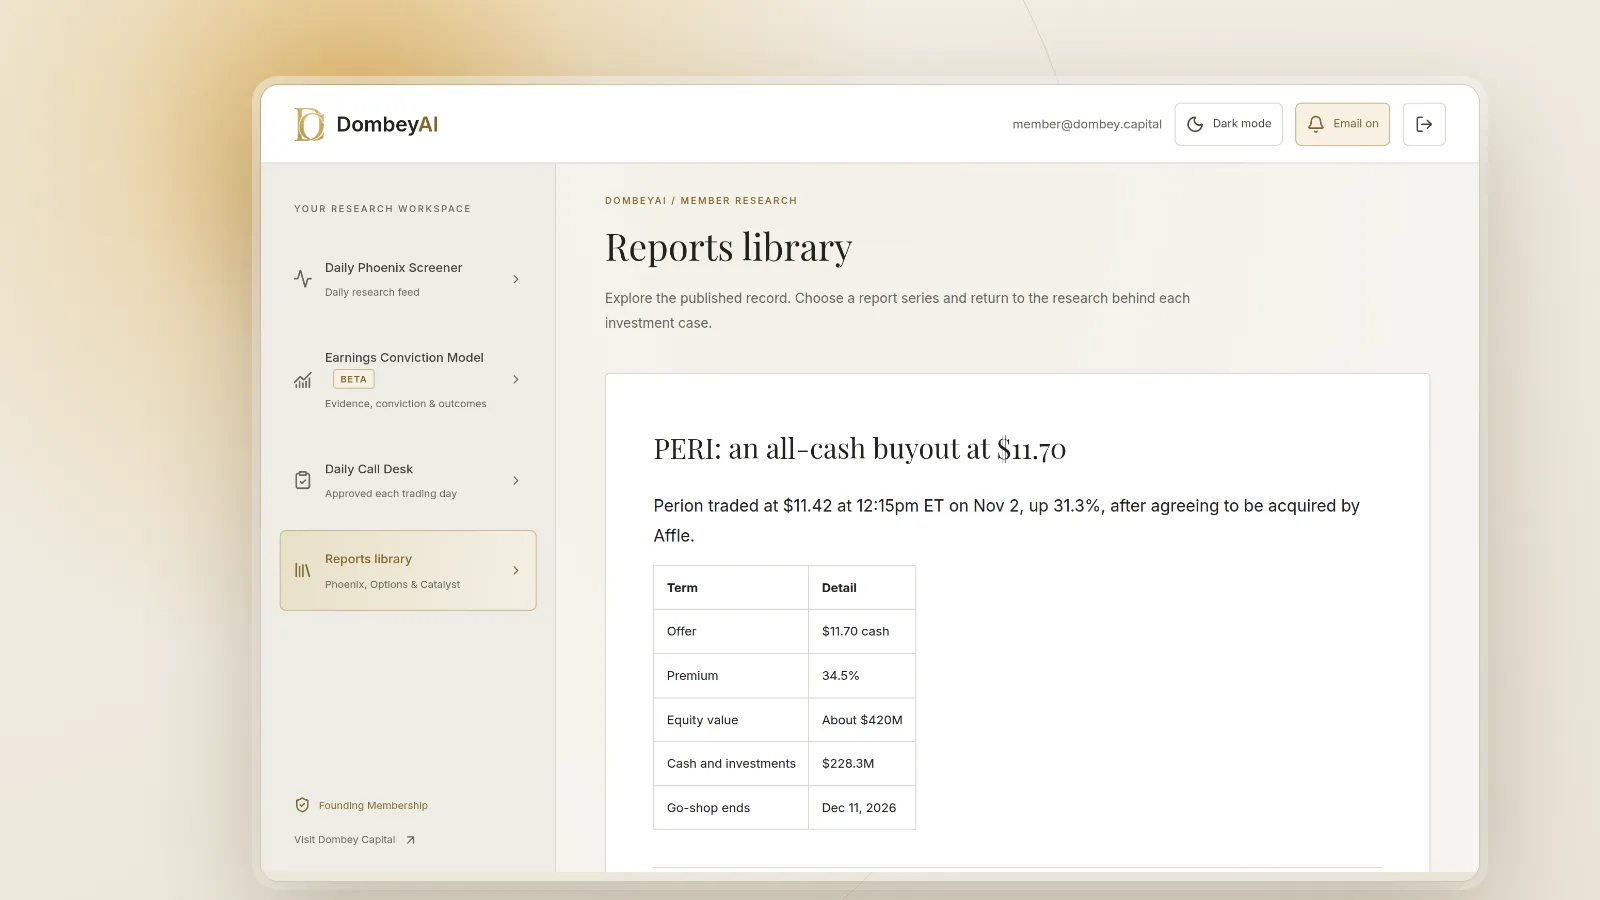
Nov 2, 2026: an all-cash offer and a 31% gap higher
Premarket trading opened at $11.19 at 4am, touched $11.43 by 7:40am and held near $11.40 into the bell. The stock opened at $11.41, dipped to $11.37 in the first five minutes, then traded in a 6-cent band all morning. It was $11.42 at 12:15pm, a new 52-week high, on about 6.0 million shares by midday against a 20-day average of about 200,000.
What happened:
- The merger agreement. Perion signed an Agreement and Plan of Merger with Affle 3iL Ltd. and a merger subsidiary on Nov 1. Each Perion share converts into $11.70 in cash at closing, and the shares will then leave Nasdaq and the Tel Aviv Stock Exchange.
- The premium. At $11.70 holders get 34.5% more than the Oct 30 close. Before the deal the stock had spent six weeks between $8.44 and $9.10.
- Financing in place. Citibank is lending to fund the purchase, and the deal is not conditioned on that financing.
- A go-shop. Perion's financial adviser, Canaccord Genuity, can solicit other offers until Dec 11, 2026.
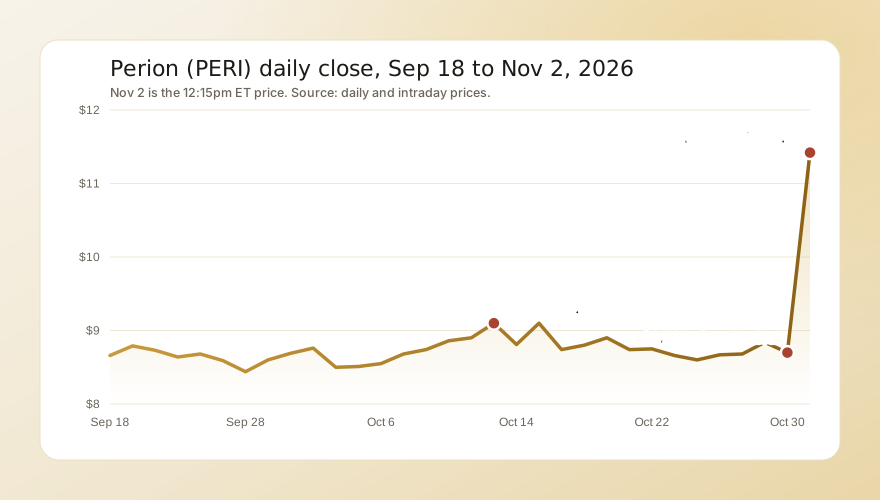
After the jump, RSI(14) stood at 81, the shares sat 27% above their 50-day average and 23% above their 200-day average, and midday volume ran about 30 times the 20-day average. In a cash deal those readings matter less than usual: the price is now pinned to the offer and the odds of closing.
The terms, in numbers
The merger is structured under the Israeli Companies Law, with Perion surviving as a wholly owned subsidiary of Affle. Closing requires:
- a majority of Perion shares voted at a special meeting, excluding shares held by the buyer side;
- expiration or termination of the waiting period under the Hart-Scott-Rodino Act;
- Israeli statutory waiting periods of at least 50 days after the merger proposal is filed and at least 30 days after shareholder approval; and
- no law or order blocking the deal.
Some directors, officers and shareholders signed voting and support agreements to back the deal. Either side can terminate if the merger has not closed 180 days after signing, which puts the outside date near the end of April 2027.
| Term | Detail |
|---|---|
| Offer | $11.70 a share in cash |
| Premium to Oct 30 close | 34.5% |
| Equity value | About $420 million |
| Go-shop ends | 11:59pm Israel time, Dec 11, 2026 |
| Break fee in go-shop | $10.5 million |
| Break fee after go-shop | $14.7 million |
| Expected closing | Early 2027 |
For the mechanics of trading a pending deal, see our guide to merger arbitrage.
What Affle is paying for
Perion reported $228.3 million of cash, short-term deposits and marketable securities at Sep 30, 2026, after spending $26.0 million on buybacks and $10.9 million on an acquisition in the third quarter. Netting that against the $420 million equity value leaves about $192 million for the operating business.
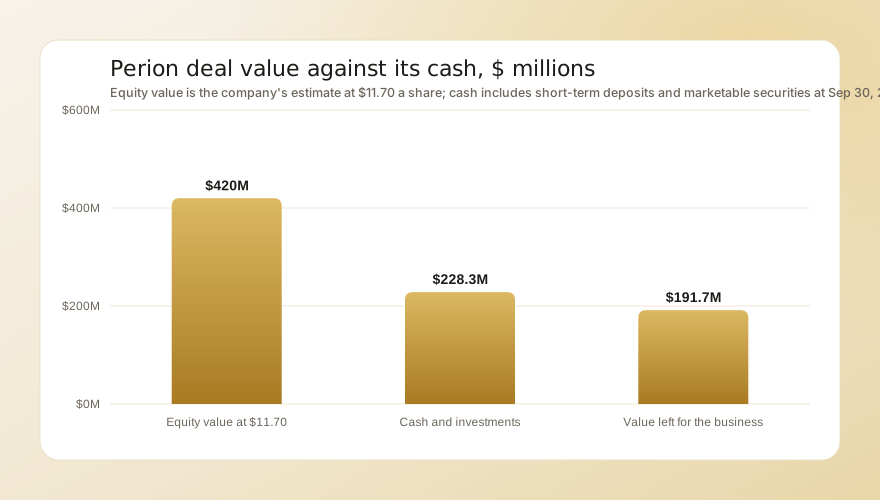
That business is not small. Perion reported second-quarter revenue of $98.2 million, and the consensus expected about $118 million for the third quarter before the deal. Before the offer the stock traded at about 8 times forward earnings and 0.7 times book value, and analysts' average price target was $13.50, above the deal price. A takeover premium of 34.5% sounds generous, but much of what Affle buys is Perion's own cash.
The case for the stock
Three facts carry the Bullish view:
- The financing risk is low. Citibank has committed debt financing and there is no financing condition, so the most common reason a leveraged buyer walks away does not apply.
- The go-shop is real. For 40 days Perion can actively seek bids, and the lower $10.5 million break fee in that window is about 2.5% of the deal value. A buyer that values Perion's retail media, connected TV and digital out-of-home units above $192 million net of cash has a clear path. Our explainer on the go-shop period covers how often these windows produce a higher bid.
- The regulatory path is short. The announced conditions are a U.S. antitrust waiting period and Israeli waiting periods. Affle is a mobile advertising company and Perion works in other channels, so the overlap is limited.
The risks
- The downside is large if the deal breaks. The pre-deal price was $8.70, about 24% below today's price. Our guide to deal breaks shows how fast spreads can blow out.
- The vote. Approval needs a majority of the votes cast, excluding the buyer's side. Holders who think Perion is worth more could vote no, though the support agreements reduce that risk.
- Time. Closing is expected in early 2027, and a cash offer pays no interest along the way. A 2.5% spread over several months is a modest return for the risk.
- The go-shop may produce nothing. Perion said it does not plan to disclose go-shop developments unless required, so a quiet Dec 11 would remove the upside case.
What comes next
The next date is Dec 11, 2026, when the go-shop ends. Before then Perion is due to file proxy materials for the special meeting and its merger proposal with the Israeli Companies Registrar, which starts the 50-day clock. Perion was due to report third-quarter results around Nov 11; companies under a pending sale often report without a call. More of the day's swings are in today's biggest stock moves, and our special situations primer explains why pending deals behave differently from ordinary stocks.
This is a view on direction over that window, not a recommendation to trade the stock.