

Why companies use a liquidating trust
A company that sells its main business and dissolves often has assets that take time to turn into cash: escrows from the sale, earn-outs, litigation claims, tax refunds, real estate or minority stakes. It also has liabilities that are not yet settled. Keeping the corporation alive to handle them means paying for a board, audits and public reporting.
A liquidating trust moves the remaining assets and liabilities into a simpler vehicle. A trustee, often a former executive or a professional fiduciary, sells what is left, settles claims and distributes cash. The corporation can then finish its dissolution, and its shares are canceled.
Liquidating trusts appear in two settings:
- Voluntary dissolution. Shareholders approve a plan of dissolution, usually after an asset sale, and the plan allows a transfer to a trust. Our guide to liquidation plays covers how these wind-downs get valued before that point.
- Chapter 11. A plan of reorganization or liquidation can create a trust to pursue causes of action, sell residual assets and pay creditors. See what happens to stock in Chapter 11 for where equity usually ranks.
How trust units work
| Feature | Common shares before the trust | Liquidating trust units |
|---|---|---|
| What you own | Equity in an operating or dissolving company | A beneficial interest in a pool of assets |
| Trading | Listed or quoted | Usually non-transferable |
| Governance | Board elected by shareholders | Trustee under a trust agreement |
| Reporting | 10-K, 10-Q, 8-K | Reduced filings or reports to holders |
| Tax treatment | Taxed on dividends and on sale | Usually a grantor trust: holders report their share of income yearly |
| Time limit | None | Fixed term, often three to five years |
The transfer to the trust usually happens on a record date. Shareholders of record receive one unit per share, and the stock is delisted. Investors who want to keep exposure have to hold the shares through that date; those who do not have to sell before it. After the transfer, the trust agreement governs distributions, reserves and the trustee's powers. Our article on delistings covers what happens to the listing itself.
Taxes on liquidating trust units
Liquidating trusts are usually set up to be treated as grantor trusts for federal tax purposes. The tax regulations define a liquidating trust as one organized mainly to liquidate assets and distribute proceeds, with no ongoing business. In practice:
- The transfer of assets to the trust is generally treated as a liquidating distribution to shareholders, measured at the assets' value on that date.
- Each holder then reports a share of the trust's income, gains and losses every year, even if the trust distributes nothing that year.
- Later cash distributions are mostly a return of the value already taxed at the transfer.
The trust sends annual statements with the figures holders need. The rules are technical and depend on each holder's situation, so read the trust's tax disclosure and check with a tax adviser.
A worked example
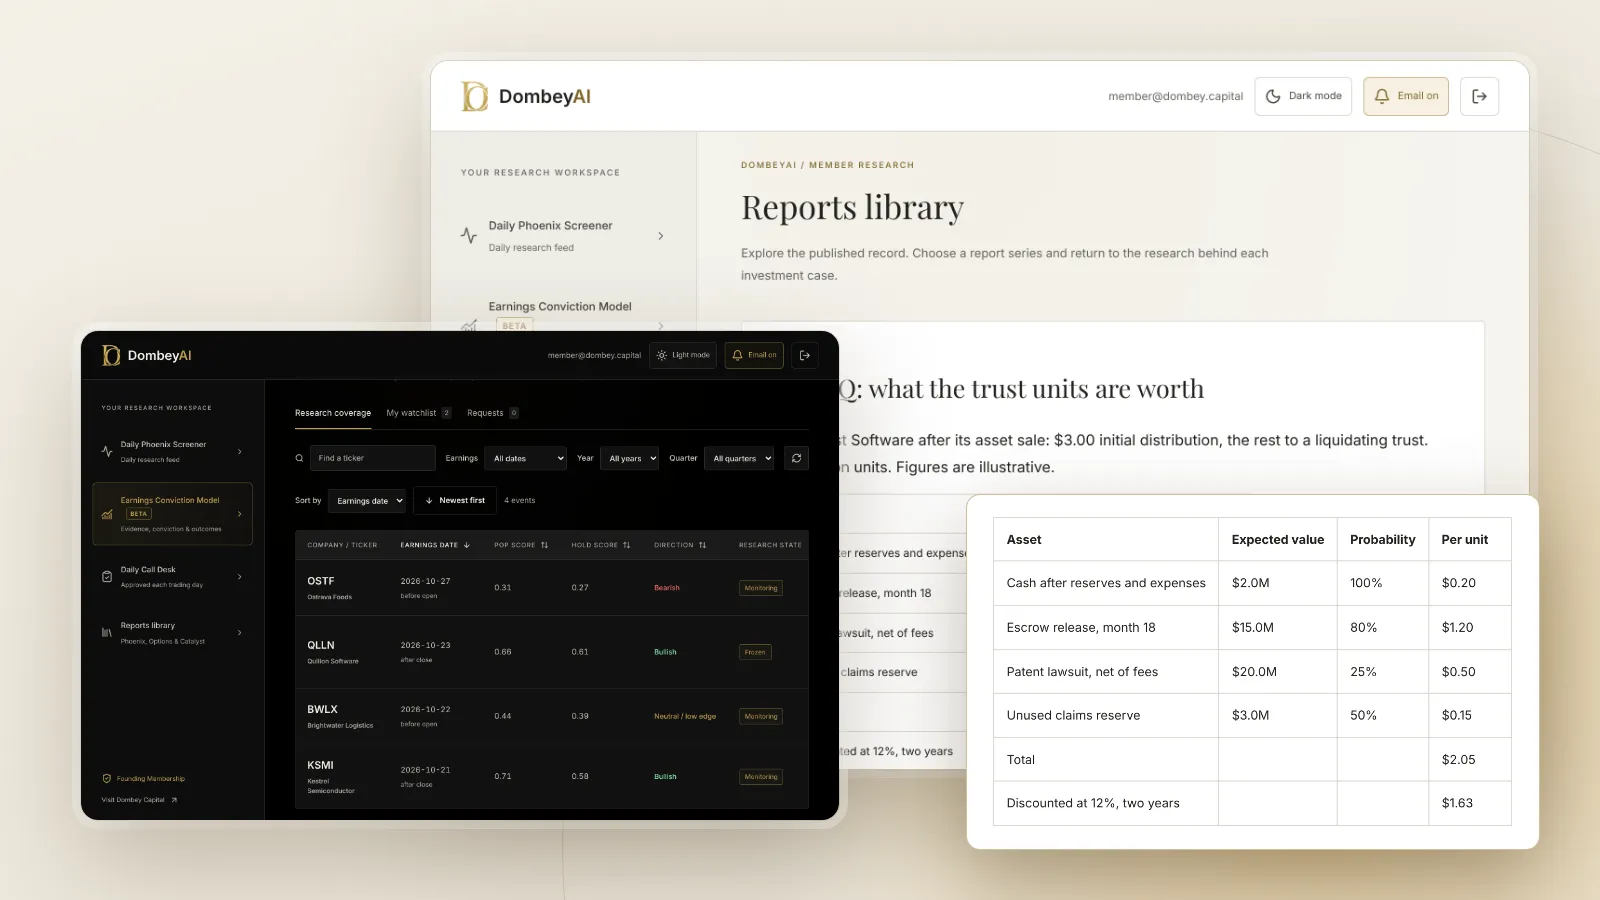
After the $30 million initial payment, the trust holds $10 million of cash, the escrow and the lawsuit. Its claims reserve is $6 million, and it budgets $2 million for trustee fees, legal and accounting over three years.
| Item | Expected value | Probability | Weighted, per unit |
|---|---|---|---|
| Cash after reserves and expenses | $2.0M | 100% | $0.20 |
| Escrow release | $15.0M | 80% | $1.20 |
| Lawsuit recovery, net of fees | $20.0M | 25% | $0.50 |
| Release of unused claims reserve | $3.0M | 50% | $0.15 |
| Total | $2.05 |
Discounted at 12% for an average of two years, the units are worth about $1.63 each. If the shares trade at $4.40 just before the record date, an investor is paying $1.40 above the $3.00 initial distribution for a claim the model values at $1.63, and that claim cannot be sold once the trust is formed.
The CVR framework helps here: break each asset into an outcome, a probability and a date, then discount.
How distributions usually arrive
Payouts from a liquidating trust tend to follow the assets. Cash that is not needed for reserves often goes out within the first few months. Escrows pay when their survival periods end, which is usually 12 to 24 months after a sale. Litigation, tax refunds and earn-outs come last and are the least certain.
The trustee also has to release reserves before they can be paid out. A claims reserve is held until the claims it covers are settled or the time to bring them has passed. Under state dissolution statutes, such as the claim procedures in Delaware, a dissolved company can set deadlines for known and unknown claims, and reserves often shrink as those deadlines pass. That is why the last distributions from a trust can be larger than expected: they include the reserves no one needed.
For valuation, this means the timing of each asset matters as much as its size. A trust that holds mostly cash and a near-term escrow is closer to a short-dated note. A trust built around one lawsuit is closer to an option on the verdict, with expenses running against it every year the case lasts. Our article on royalty trusts covers a very different kind of trust that also passes cash straight through to unit holders.
What to read before the record date
- The plan of dissolution or Chapter 11 plan. It sets what goes into the trust and what the trustee can do.
- The trust agreement. It names the trustee, the term, the transfer limits, the reserves and how expenses are paid.
- The proxy statement or disclosure statement. It usually contains management's estimate of total distributions, with a range. Our guide on reading a Chapter 11 disclosure statement covers the bankruptcy version.
- The last 10-Q. It shows the balance sheet the trust will inherit and the contingencies note.
- 8-K filings. Companies announce initial distributions, record dates and the trust's formation by 8-K, and the filings are searchable on EDGAR.
Where this goes wrong
- Slow asset sales. Escrows get disputed and lawsuits take years. Each year of delay lowers the present value and adds expenses.
- Claims above the reserve. A warranty claim, tax audit or lawsuit against the old company can consume the reserve and reach the assets meant for holders.
- Trust expenses. Trustee fees, lawyers and accountants are paid before holders. For a small trust, they can absorb a large share of what remains.
- No exit. Non-transferable units mean you cannot sell if you change your mind or need the cash. Treat the units as locked up for the full term.
- Phantom income. Holders can owe tax on trust income in a year with no cash distribution.
- Management estimates. The range in the proxy is management's view at the time and often assumes that contingencies resolve favorably.
The bottom line
A liquidating trust is the vehicle that holds a dissolving company's last assets, sells them and pays former holders. Its units are usually non-transferable and taxed as if the holder owned the assets directly, so the decision to hold through the record date is a decision to stay in until the end. Value the units asset by asset, subtract reserves and expenses, and discount for time. For more on this corner of the market, see our list of investing newsletters for special situations; Dombey's published wind-down research is in the research archive.