

Nov 9, 2026: up 15.5% into the report, up 29% after it, then back down
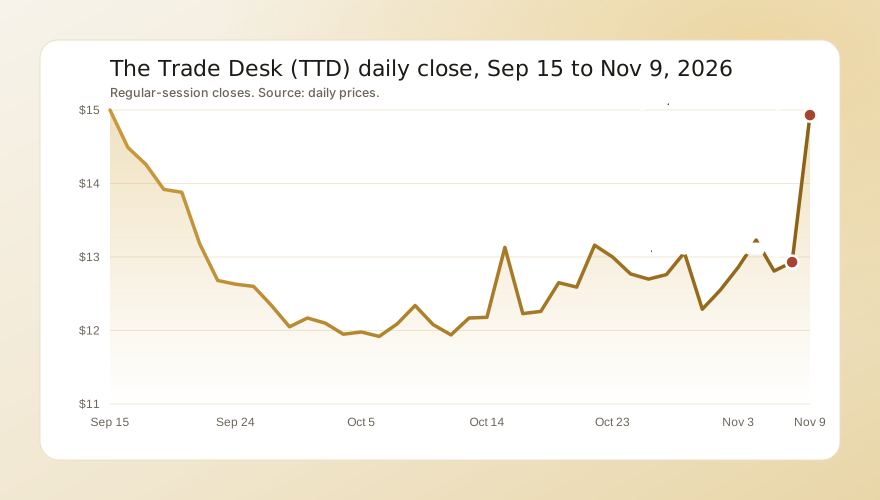
Before the report. The Trade Desk opened at $13.78 and climbed through the day to close at $14.93, up 15.5% from $12.93, on 96.5 million shares, about 6.7 times its 20-day average. Barron's said it was the stock's largest one-day gain since March 5. The company issued no news during the session. The market was strong, with the Nasdaq 100 fund QQQ up 3.5%, and other ad-tech names rose too, by about half as much or less. The bar was low: the consensus of $650.9 million that Barron's reported implied a 12% fall in third-quarter revenue from $739 million a year earlier, and the company itself had guided to at least $650 million.
From the Nov 6 close to the Nov 9 close:
| Stock or fund | Nov 6 close | Nov 9 close | Change |
|---|---|---|---|
| The Trade Desk (TTD) | $12.93 | $14.93 | +15.5% |
| Criteo (CRTO) | $15.42 | $16.61 | +7.7% |
| PubMatic (PUBM) | $17.81 | $19.03 | +6.9% |
| Magnite (MGNI) | $27.39 | $29.04 | +6.0% |
| AppLovin (APP) | $391.22 | $410.00 | +4.8% |
| Amazon (AMZN) | $259.30 | $266.93 | +2.9% |
| Alphabet (GOOGL) | $284.78 | $288.15 | +1.2% |
| Invesco QQQ (QQQ) | $656.10 | $679.35 | +3.5% |
The spike. In the first minutes after the release the shares traded up to $19.20 and were still near $18 an hour later. The numbers, from the company's results release:
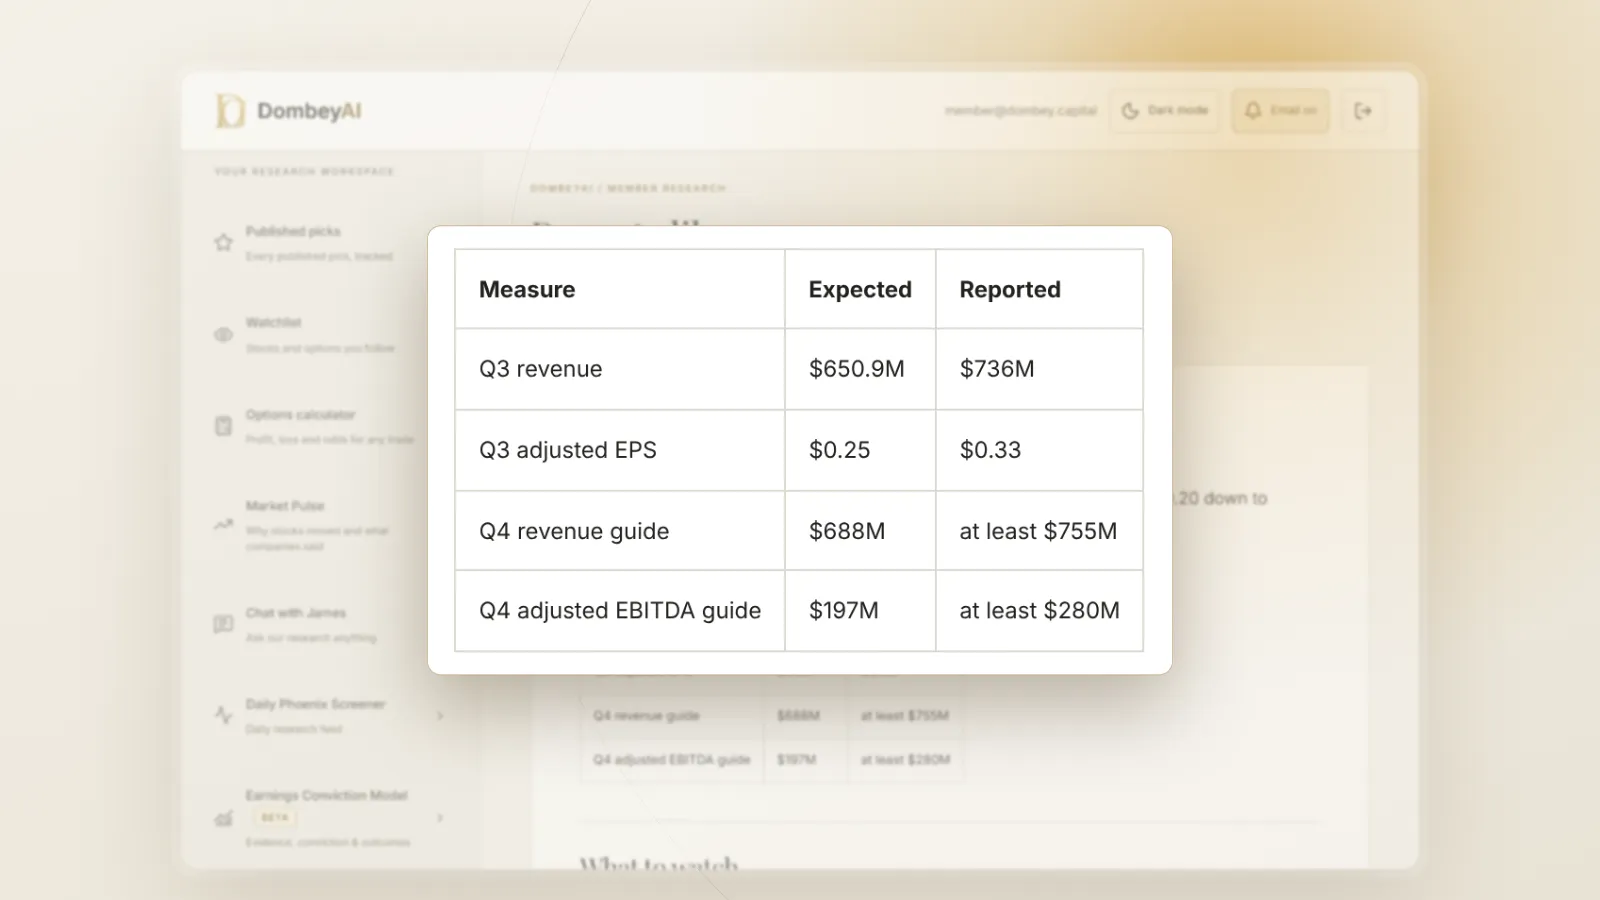
- Revenue beat the floor. Third-quarter revenue was $736 million, down 0.5% from $739 million, against the company's guide of at least $650 million and consensus of $650.9 million.
- Profit beat by more. Adjusted EBITDA was $266 million, a 36% margin, against guidance of about $160 million, though below $317 million a year earlier. Adjusted earnings were $0.33 a share against $0.25 expected and $0.45 a year ago. GAAP net income was $38 million, down from $116 million, after $44 million of restructuring charges from the September layoffs of about 15% of staff.
- The guide beat too. Fourth-quarter revenue of at least $755 million and adjusted EBITDA of at least $280 million compare with consensus of about $688 million, Barron's reported, and about $197 million, according to Stocktwits.
- The buyback grew. The board added $731 million to the repurchase authorization, which now stands at $1 billion. The company bought back $241 million of stock in the first nine months of 2026.
The fade. The call began just before 5pm. The shares were $17.65 at 5:10pm, $16.18 at 5:20pm and touched $14.41 near 5:45pm, a fall of 24.9% from the after-hours high. Three things came out of the call and the quarterly filing that took the shine off the beat:
- Part of the beat will not repeat. The 10-Q says third-quarter revenue included $15 million of nonrecurring revenue from a strategic partner. Without it, revenue was about $721 million, down 2.5%.
- No holiday lift. The CFO said the company does not expect the normal seasonal rise from the third quarter to the fourth, citing a still-difficult market and pressure on some large advertisers, Stocktwits reported. The floor of $755 million is only 2.6% above the third quarter. A year earlier revenue rose 14.5% from the third quarter to the fourth, to $846.8 million, so the guide implies a decline of at least 10.8%.
- Recovery is a 2027 story at best. Political advertising was a mid-single-digit share of third-quarter revenue and should be slightly higher in the fourth, and management pointed to 2027 for slower expense growth. Truist told clients management sees 2027 as a year of stabilization before growth in 2028, and StoneX called 2026 a "lost year," Barron's reported.
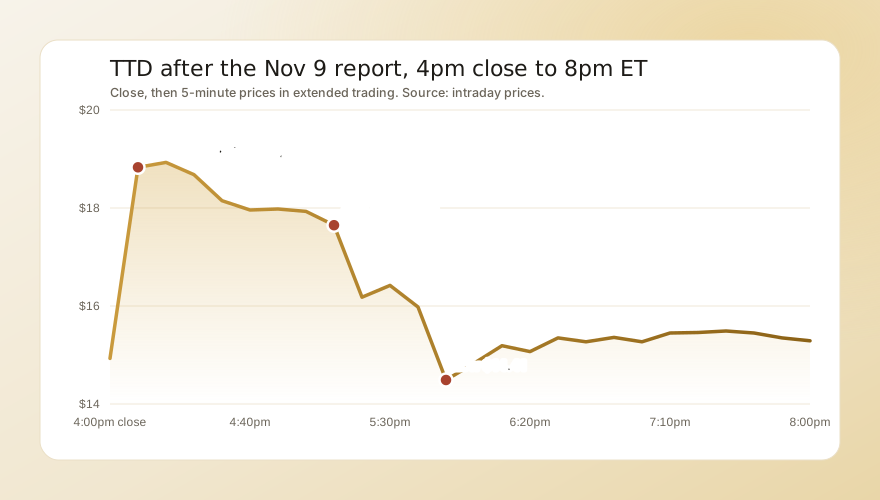
The stock ended the evening session at $15.29, up 2.4% from the close, and was about 3% higher in overnight trading, Stocktwits reported later that night. Our guide on why outlooks move stocks covers why the shape of a guide can matter more than the size of a beat, and Magnite's move after its own report shows how the rest of ad tech has been judged this season. More of the day's swings are in today's biggest stock moves.
What the numbers say
At the $14.93 close, with 472.9 million Class A and Class B shares outstanding on Oct 31, The Trade Desk was worth about $7.06 billion. It held $1.23 billion of cash and $420 million of short-term investments on Sep 30 and had nothing drawn on its $750 million credit line, which leaves an enterprise value near $5.4 billion. Annualizing the fourth-quarter EBITDA floor of $280 million gives $1.12 billion, so the stock trades near 4.8 times. Our explainer on EV to EBITDA covers why that multiple flatters a business whose revenue is still falling.
Cash generation is the other support. Operating cash flow was $804 million in the first nine months of 2026, and the company spent $241 million of it on buybacks. A $1 billion authorization against a $7 billion market value is large; our note on buybacks as catalysts covers when repurchases change the share count enough to matter.
Analysts are not convinced. Barron's reported that Truist and StoneX both see 2026 as a reset year, and Rosenblatt expected revenue declines to speed up in the fourth quarter even with political spending. The stock was down 60.7% in 2026 through the Nov 9 close, Barron's reported. Its 52-week range runs from $11.62 on Oct 7, 2026 to $45.50 on Nov 12, 2025.
The bull case
- The company under-promised. Third-quarter revenue beat its own floor by 13% and adjusted EBITDA beat its guide by about $106 million. If the fourth-quarter floor is set the same way, $755 million is a low bar.
- Cheap on cash flow. Near 5 times annualized EBITDA after cash, the shares price in further decline, not a flat year.
- A large buyback. $1 billion of authorization is about 14% of the market value, funded by $1.65 billion of cash and investments and an undrawn credit line.
- Customers are staying. Retention stayed above 95%, as it has for more than a decade, and Netflix expanded its integration so advertisers can use first-party and third-party data to target Netflix audiences through the company's Kokai platform from November.
- Costs are coming down. The September layoffs should cut expenses into 2027, and management expects expense growth to slow next year.
The risks
- Revenue is still shrinking. Third-quarter revenue fell even with the one-time partner revenue, and the fourth-quarter floor implies a decline of at least 10.8%.
- Agencies and rivals. Barron's reported that spending from Publicis, historically a mid-teens share of revenue, dropped after a dispute, with some moving to Google, and that Amazon is pressing on price.
- Insiders reset their own bar. On Oct 19 the company cut the exercise price of most underwater employee and executive options to $12.26, below where the stock now trades. That lowers the share price at which staff options pay off.
- The run-up is spent. The stock rose 15.5% before the report and gave back the whole after-hours gain within two hours, which suggests the good news was largely in the price.
- A swing this wide can repeat. A 28.6% rise and 24.9% fall in one evening show how thin the market for the stock is after hours. Our note on realized and implied volatility covers how to read moves like this.
What comes next
The fourth quarter ends on December 31, 2026, and the company has reported fourth-quarter results in February in past years; no date is set in the sources we checked. Before then, watch how the shares trade in the Nov 10 regular session against the $14.93 close, whether analysts lift their fourth-quarter estimates toward the $755 million floor, and whether the company uses the new authorization. The test of the Bullish view is fourth-quarter revenue at or above $755 million and a 2027 outlook that does not call for another year of decline.