

Why skew exists
If option prices followed the textbook model exactly, every strike in one expiry would carry the same implied volatility. They do not, for three practical reasons.
- Demand for protection. Investors who own a stock buy puts to cap losses. Few holders buy calls for insurance. Persistent demand on one side raises the price, and so the implied volatility, of those strikes.
- Stocks fall faster than they rise. Sharp declines tend to arrive as gaps on bad news, while gains tend to build more slowly. Volatility also tends to rise when prices fall. A put seller is exposed to both effects at once and charges for it.
- Market makers carry inventory. The dealers who sell those puts have to hedge them, and hedging a short put becomes more expensive just when the market is falling. That cost is passed on in the price.
Index options have priced downside protection at a premium for decades, because portfolio managers use them as hedges. Single stocks usually show a milder version, and some show the reverse.
How to measure skew
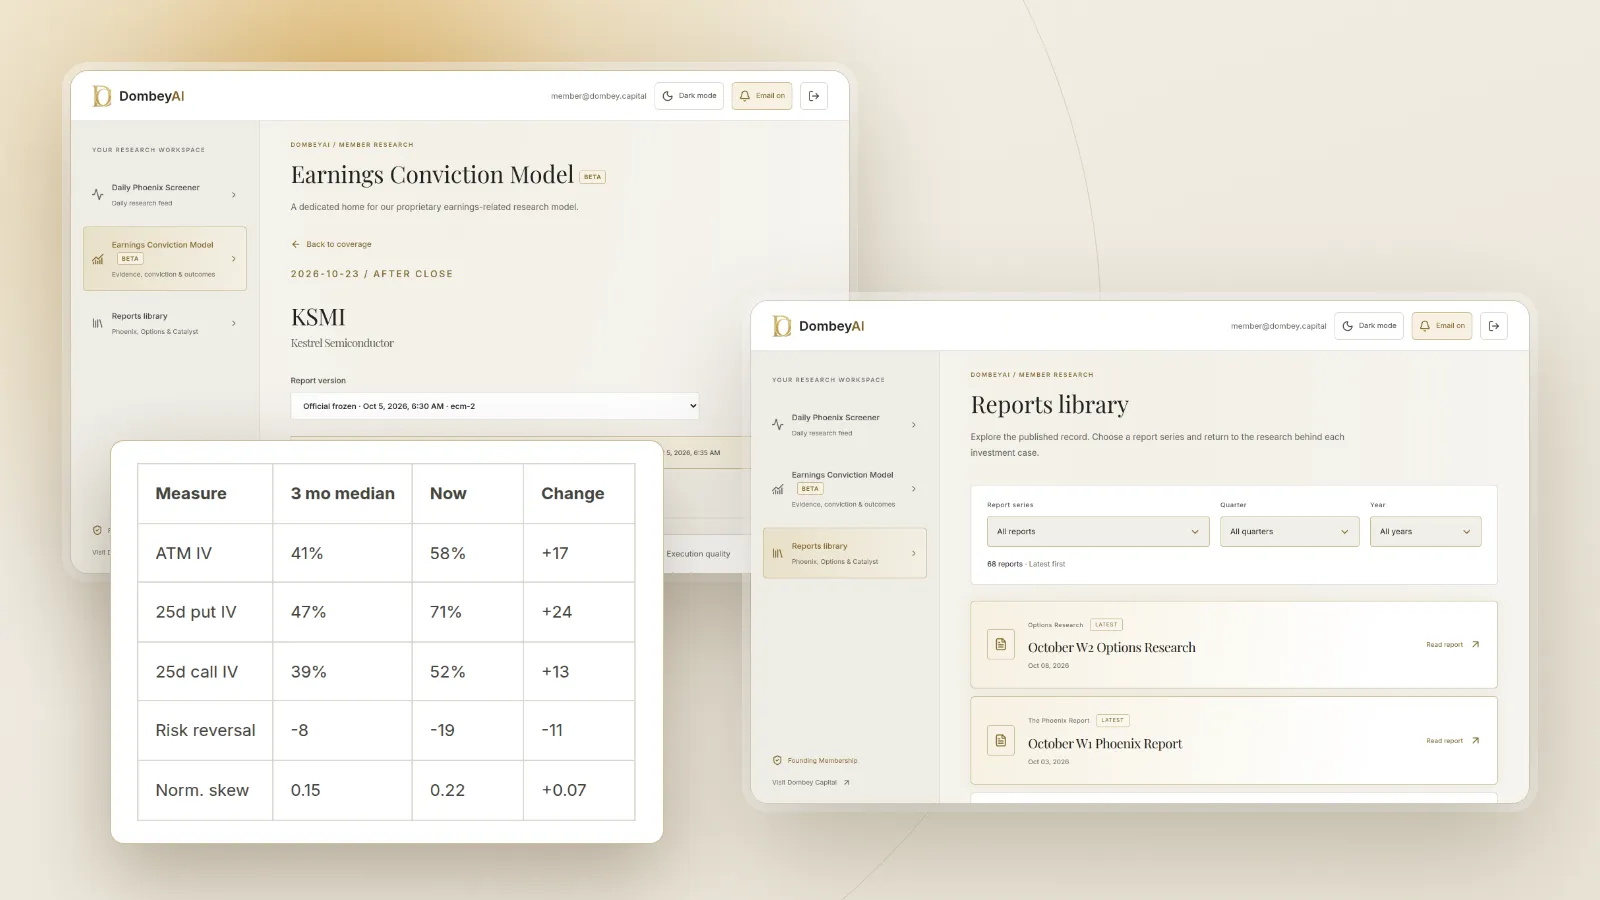
There is no single official skew number for a stock, so the first rule is to choose one method and use it every time. The common versions all compare two points on the same expiry.
| Measure | How it is calculated | What it shows | Where it misleads |
|---|---|---|---|
| 25-delta risk reversal | 25-delta call IV minus 25-delta put IV | Relative price of upside versus downside | Usually negative, so the sign alone says little |
| Put skew | 25-delta put IV minus at-the-money IV | How much extra the market pays for downside | Rises mechanically when at-the-money IV falls after an event |
| Normalized skew | Put skew divided by at-the-money IV | Skew comparable across stocks with different volatility | Unstable when at-the-money IV is very low |
| Fixed-strike spread | IV at, say, 90% of spot minus IV at 110% of spot | Simple, readable from any chain | Delta of a fixed strike changes as the stock moves |
| Skew slope | Change in IV per strike or per point of delta | Steepness of the whole curve | Needs several liquid strikes to be reliable |
Delta-based measures are the most common because a 25-delta option is roughly the same distance from the money in probability terms, whatever the stock price. Fixed-percentage strikes are easier to read off a chain but drift as the stock moves.
The shapes and what they say about risk
Plot implied volatility against strike for one expiry and you get one of a few shapes.
Smirk, or put skew
Implied volatility is highest on the low strikes and falls steadily toward the high strikes. This is the normal shape for most stocks and almost all indexes. It says the market prices a large fall as more likely, or more costly, than a large rise. A steeper smirk than usual means more demand for downside protection, less willingness to sell it, or both.
Smile
Both wings sit above the at-the-money level. The market is paying for a large move in either direction, which is common ahead of a binary event where the outcome could send the stock far up or far down. Small biotech names waiting on a regulatory decision often show this shape in the expiry that contains the date.
Call skew
The upside strikes carry more implied volatility than the downside. This is less common and usually has a specific cause:
- A possible takeover or strategic review, where buyers pay for exposure to a bid.
- A heavily shorted stock, where short sellers buy calls to cap their own risk. Our guide to short interest and squeeze risk covers that side.
- A binary event with a large upside payoff and a limited downside, because the stock already trades near what the company would be worth if the event fails.
- Hard-to-borrow shares, which distort put and call prices in ways that can show up as call skew.
Flat skew
Little difference across strikes. This can mean the market sees risk as symmetric, or simply that the outer strikes trade too rarely for their implied volatility to mean anything. Check the bid-ask spreads before reading a flat curve as information.
Skew around dated catalysts
Skew changes most around known events, and the change is often more useful than the level.
Before earnings. The expiry that holds the report lifts as a whole, which our guide to estimating an earnings move from options shows how to measure. Inside that expiry, skew often flattens, because the at-the-money level rises more than the wings. If the put wing rises faster than the at-the-money level instead, the market is paying specifically for a bad outcome.
After earnings. At-the-money implied volatility falls sharply, which is IV crush. Because the at-the-money level drops more than the wings, put skew measured in points can look steeper the next morning even if nothing about downside risk has changed. This is the most common misreading of skew, and it is why normalized measures exist.
Announced cash takeovers. Once a cash deal is announced, the target's upside is capped near the offer price, so upside strikes trade at very low implied volatility. The downside, a fall back toward the undisturbed price if the deal breaks, is large. The result is extreme put skew that reflects deal risk. A rise in that skew while the spread also widens is the options market agreeing that the deal is in trouble. Merger arbitrage investors watch both for this reason.
Binary events. Ahead of a court ruling, a regulatory decision or a shareholder vote, the expiry after the date often shows a smile. The relative height of the two wings is the market's rough view of which outcome would move the stock further.
Reading skew alongside other option data
Skew is one input among several. On its own, a steep put wing could mean fear, hedging or a single large trade.
- Open interest. Check whether the expensive strikes also show rising open interest. Skew that moves with no change in positions may be quote noise.
- Put-call ratio. The put-call ratio counts contracts, while skew measures price. Heavy put volume with no change in skew suggests sellers met the buyers easily. Rising skew on modest volume suggests sellers are scarce.
- Flow. Large prints on one wing can explain a sudden change. Our list of options flow and unusual activity tools covers where to see them.
- Filings and the calendar. A skew move with no news is a reason to check recent 8-Ks, insider filings and the event calendar, not a conclusion in itself.
A practical way to combine them:
- If put skew steepens, open interest rises in the put wing and nothing has been filed, look for an upcoming event or a holder hedging a large position.
- If call skew appears and short interest is high, the likely buyers are short sellers covering their risk, not investors expecting a bid.
- If skew moves only the morning after earnings, recompute it in normalized form before reading anything into it.
- If the outer strikes have wide spreads and little open interest, ignore the skew reading entirely.
Where this goes wrong
- Reading the level instead of the change. Almost every stock has put skew. A reading only means something against the same stock's own history, measured the same way, in a comparable expiry.
- Mixing expiries. Skew in a one-week option and a six-month option behave differently. Short-dated skew reacts to news; long-dated skew moves slowly. Compare like with like.
- Mechanical changes. When at-the-money implied volatility falls, point-based skew can rise with no change in the wings. Normalize, or look at the wing levels directly.
- Thin wings. In small companies, the far strikes may trade a few times a month. Implied volatility from a stale or wide quote is not a market price.
- Assuming informed buyers. Expensive puts are as often bought by long holders protecting a gain as by anyone with a view. Skew tells you what is being paid for, not who will be right.
- Borrow and dividends. Hard-to-borrow shares and large expected dividends change put and call prices for reasons unrelated to the market's view of risk.
How to use it in research
Skew is most useful as a question generator. When it moves out of line with the stock's history, it points to a part of the outcome range the market has started to price differently, and the next step is to find out why in the primary documents. Dombey's published research reads skew and the implied move alongside the filings before each catalyst; see the research archive.
Keep a simple record for the names you follow: one measure, one expiry window, recorded weekly. After a few months you will know what normal looks like for each stock, which is the only way a skew reading becomes informative.
The bottom line
Options skew is the gap in implied volatility between strikes in one expiry, and in most stocks it tilts toward puts because protection is in demand. Measure it one way, such as the 25-delta risk reversal, and judge it against the stock's own history rather than a fixed level. Call skew, smiles and sudden changes usually have a specific cause, such as a possible bid, a crowded short or a dated event. Read skew with open interest, flow and the filings, and treat it as the market's price for risk in each direction, not a forecast.