

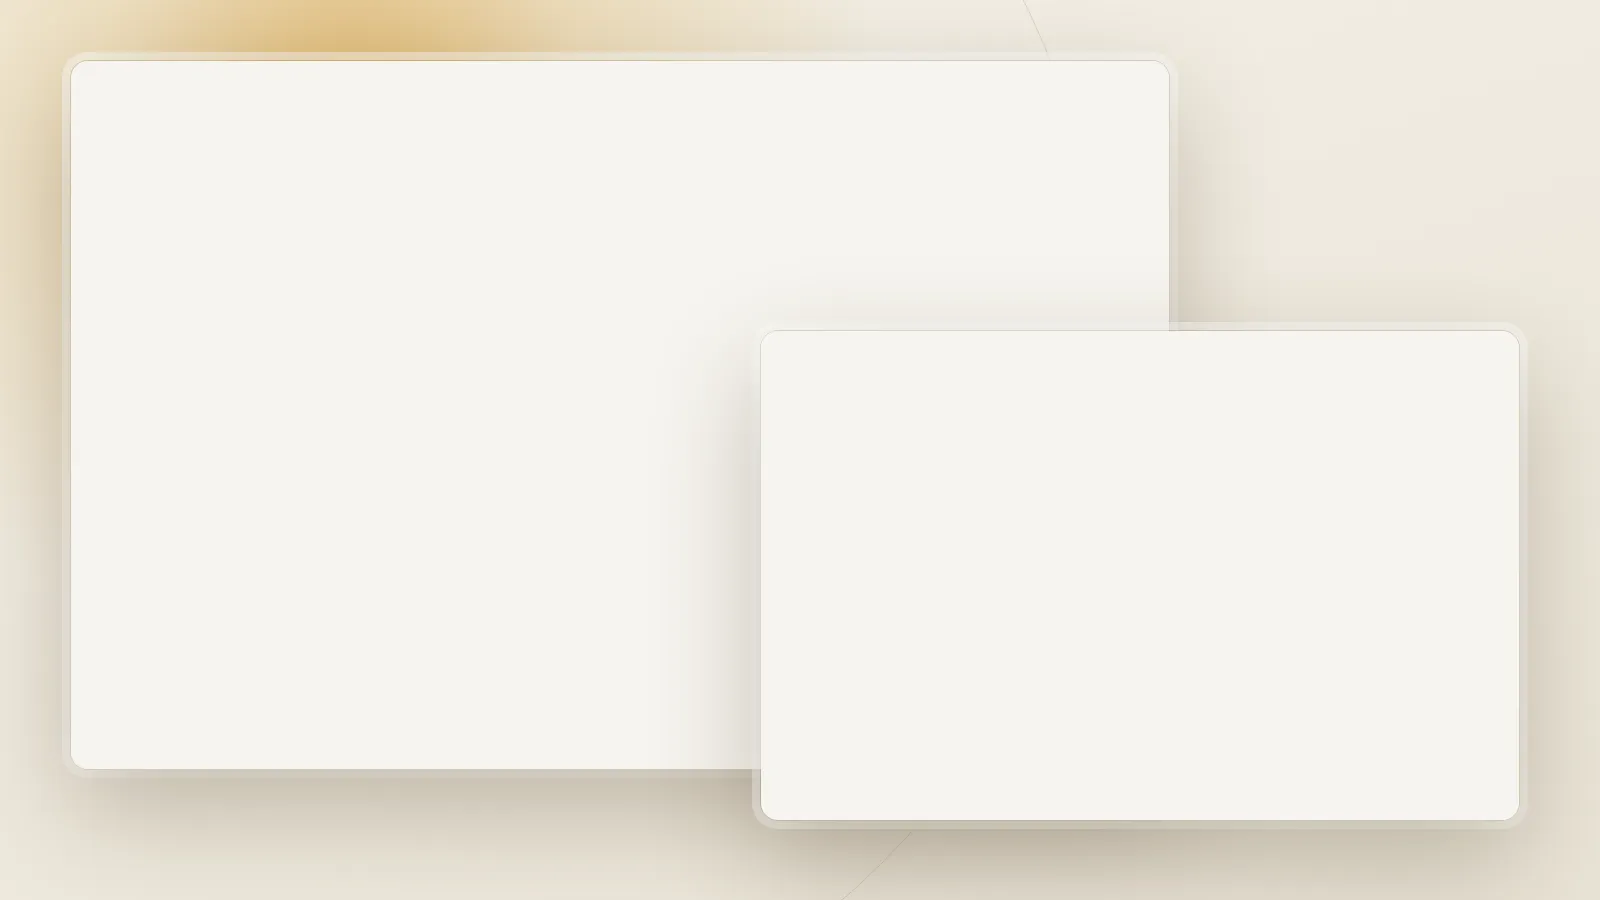
The formula
For a European call and put with strike K and time to expiry T, on a stock with price S that pays no dividend before expiry:
C - P = S - K / (1 + r)^T
With continuous discounting, the same thing is written C - P = S - K e^(-rT).
| Symbol | Meaning |
|---|---|
| C | Call price |
| P | Put price at the same strike and expiry |
| S | Current stock price |
| K | Strike price |
| r | Riskless interest rate, such as a Treasury bill yield |
| T | Time to expiry, in years |
| PV(K) | Present value of the strike, K discounted at r for T |
With dividends expected before expiry, subtract their present value from the stock price: C - P = S - PV(D) - PV(K).
Why it holds
Compare two portfolios.
- Portfolio 1: buy one call and hold cash equal to the present value of the strike.
- Portfolio 2: buy one put and one share of stock.
At expiry, if the stock is above the strike, Portfolio 1 exercises the call and uses the cash to pay the strike, ending with one share. Portfolio 2's put expires worthless and it holds one share. If the stock is below the strike, Portfolio 1's call expires and it holds cash equal to K. Portfolio 2 exercises the put, selling the share for K. Either way, the two portfolios end with the same value.
Two portfolios with identical payoffs must cost the same today. So C + PV(K) = P + S, which rearranges to the formula.
A worked example
Now suppose the call trades at $6.50 instead. The call is rich by $0.58 relative to parity. A trader could sell the call, buy the put and buy the stock (a conversion), locking in the gap before costs. Enough traders doing this pushes prices back into line.
Synthetic positions
Rearranging the formula shows how options can copy other positions:
| Synthetic position | Built from | Behaves like |
|---|---|---|
| Synthetic long stock | Long call, short put, same strike and expiry | Owning the stock with borrowed money |
| Synthetic short stock | Short call, long put | Shorting the stock |
| Synthetic long call | Long stock, long put | A call, the logic behind a protective put |
| Synthetic long put | Short stock, long call | A put |
| Conversion | Long stock, long put, short call | A riskless bond paying K at expiry |
The conversion row is the same idea that makes a collar with matching strikes lock in a fixed outcome.
What a break in parity tells you
On listed US stock options, quoted prices rarely violate parity by more than trading costs. When they appear to, there is usually a reason.
Dividends. An expected dividend lowers the stock's forward price, so calls look cheap and puts look rich against a no-dividend formula. Check the dividend calendar before concluding anything.
Early exercise. Most US equity options are American style. Deep in-the-money puts and calls just before a dividend can be worth exercising early, which pushes parity into a range rather than an exact equation.
Cost to borrow. This is the most useful signal. When a stock is hard to borrow, short sellers turn to puts, and market makers who sell those puts cannot easily hedge by shorting. The put price rises above what parity with zero borrow cost implies. The size of the gap lets you back out an implied borrow rate. A large implied borrow rate often accompanies heavy short interest.
Deal and event risk. In pending mergers, special dividends or spin-offs, contract adjustments and the expected event change the forward price. Our explainer on what happens to options when a company is acquired covers how those adjustments work.
A second example: backing out the borrow cost
A borrow fee that high tells you shares are scarce. That usually means heavy short interest, a small float or a pending event, such as a merger vote or a lockup expiry, that many traders want to hedge. It also changes the economics for anyone holding the stock: shares lent out earn the fee, and buyers of the put are paying for it.
How to use parity when reading a chain
Parity gives quick checks when you look at an option chain:
- If the call and put at the money cost about the same, the forward price is close to the stock price, meaning low rates, no dividend or both.
- If puts are rich at every strike, look for a dividend or a high borrow cost.
- If implied volatility differs between a call and put at the same strike, parity says it should not, after dividends and borrow. The gap is a sign of borrow cost or stale quotes.
- If you want the market's forward price, compute S - PV(D) from C - P + PV(K) at an at-the-money strike.
Parity is also why calls and puts at the same strike share one implied volatility in a clean market, and why their Greeks are linked: the delta of a call minus the delta of the put at the same strike is close to one.
For daily coverage of options around earnings and events, see the market page. Dombey's Options Research applies these checks before each catalyst; see the research archive.
Where this goes wrong
- Using stale or wide quotes. Bid-ask spreads on illiquid options can make parity look broken when it is not. Use mid-prices and check volume.
- Forgetting the dividend. A missed dividend is the most common reason a calculation looks off.
- Ignoring early exercise. American-style options do not follow the European formula exactly.
- Assuming free borrowing. The formula assumes you can short the stock and earn the riskless interest rate on cash. Retail accounts rarely can.
- Chasing small gaps. Commissions, spreads, margin and borrow fees usually exceed any apparent profit for individual traders.
- Missing contract adjustments. After a special dividend, spin-off or merger, an adjusted contract may deliver something other than 100 shares.
The bottom line
Put-call parity says a call minus a put equals the stock minus the present value of the strike, for options with the same strike and expiry. It holds because two portfolios with the same payoff must cost the same. Dividends, early exercise and borrowing costs adjust it, and those adjustments are where the useful information lies. When puts look expensive relative to calls, check the borrow and the dividend calendar before reading it as sentiment.