

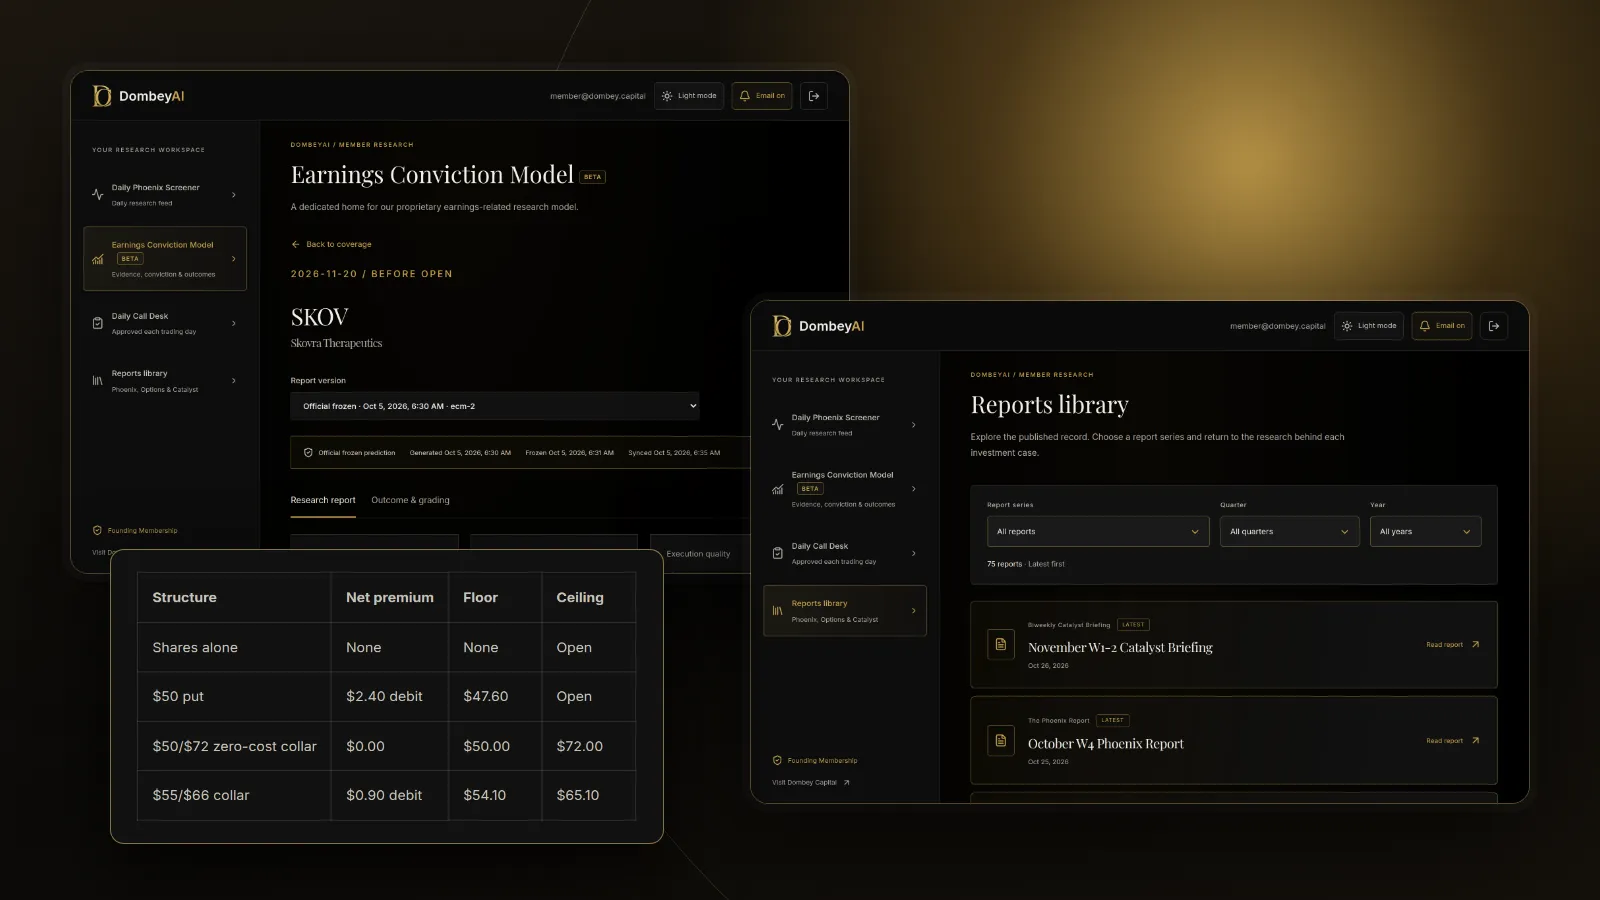
How a collar works
A collar has three parts:
- Long stock, usually in lots of 100 shares.
- A long put at a strike below the current price, which gives the right to sell the shares at that strike.
- A short call at a strike above the current price, which gives someone else the right to buy the shares at that strike.
At expiration:
- Below the put strike, the put offsets further losses on the stock.
- Between the strikes, both options expire worthless and the position moves with the stock.
- Above the call strike, the shares are likely to be called away at the call strike.
The net premium is the call premium received minus the put premium paid. A net credit lowers the effective cost of the shares; a net debit raises it.
Collar payoff at a glance
| Stock at expiration | Stock | Put | Call | Position value per share |
|---|---|---|---|---|
| Below the put strike | Falls | Gains | Expires worthless | Put strike plus or minus net premium |
| Between the strikes | Moves | Expires worthless | Expires worthless | Stock price plus or minus net premium |
| Above the call strike | Rises | Expires worthless | Loses | Call strike plus or minus net premium |
The floor and ceiling are fixed when the collar is opened. Everything else follows from the two strikes and the net premium.
A worked example
The strikes in the example are not symmetric around $60. Before a binary event, puts and calls are both expensive, and skew often makes downside puts cost more than upside calls the same distance away. That pushes the call strike of a zero-cost collar closer to the stock price, or the put strike further away. Our explainer on options skew covers why.
Collars around a catalyst
A collar fits a specific situation: you hold a stock you want to keep, a dated event could move it sharply, and you would accept giving up some upside to avoid a large loss.
- If the event is binary and the downside is large, a collar sets a hard floor. See how to size a position before a binary event.
- If you want to keep all the upside, a protective put does that at the cost of its premium.
- If you mainly want income and accept the downside, a covered call sells the call without buying the put.
- If you have no position and want exposure with a defined risk, a vertical spread is closer to the goal.
Choose the expiration with the event in mind. Options that expire just after the event are cheapest in time value but leave no protection if the outcome is delayed. A decision that slips by a month can leave a collar expiring before the news.
Implied volatility falls after most events, the effect known as IV crush. Because the collar is long one option and short another, much of that effect cancels, which is one reason collars are cheaper to hold through an event than a put alone.
Choosing the strikes
The two strikes trade off against each other:
| Choice | Effect on floor | Effect on ceiling | Net premium |
|---|---|---|---|
| Put strike closer to the price | Higher floor | Unchanged | More expensive |
| Put strike further away | Lower floor | Unchanged | Cheaper |
| Call strike closer to the price | Unchanged | Lower ceiling | More credit |
| Call strike further away | Unchanged | Higher ceiling | Less credit |
Start from the loss you cannot accept, set the put strike there, then find the call strike that pays for it. If that call strike is too close to the current price, the event may not be worth hedging with a collar, or a net debit collar with a higher ceiling may fit better. The option greeks show how each leg responds to the stock, time and volatility.
A collar or simply selling
The obvious alternative to a collar is selling some or all of the shares before the event. Selling removes the risk completely, needs no option market and has no assignment or expiry problems. It also gives up the upside entirely and may realize a taxable gain.
A collar makes sense when there is a reason to keep owning the shares: a large unrealized gain, a lockup or holding restriction, a view that the stock is undervalued over a longer period, or voting rights that matter in a contest or merger vote. If none of these applies, selling a portion of the position can achieve much the same risk reduction with fewer moving parts.
Some investors combine the two: they sell part of the position and collar the rest. That keeps exposure to a good outcome on the shares they retain while capping the loss on the position as a whole.
Pros and cons of a collar
Pros
- The worst outcome is known before the event.
- A zero-cost collar needs no cash outlay.
- Less exposure to falling implied volatility than a put alone.
Cons
- Upside above the call strike is given up.
- Three positions, two option markets and two bid-ask spreads to pay.
- The short call can be assigned early, especially before an ex-dividend date.
Where this goes wrong
- Early assignment. American-style equity calls can be exercised at any time. A deep in-the-money call is often assigned before an ex-dividend date, which removes the shares and leaves the put on its own.
- Event timing. If the catalyst slips past expiration, the collar expires and the position is unhedged when the news arrives.
- Liquidity. Options on smaller stocks can have wide markets, so the zero-cost collar on screen may cost money to execute. Our explainer on options liquidity covers how to read the quotes.
- Corporate actions. In a merger or special dividend, contract terms can be adjusted. See what happens to options when a company is acquired.
- Tax treatment. Tight collars on appreciated stock can trigger constructive sale or straddle rules.
For daily coverage of stocks moving on earnings, rulings and other catalysts, see Dombey's market coverage.
The bottom line
A collar holds a stock with a bought put below the price and a sold call above it, fixing a floor and a ceiling for the life of the options. A zero-cost collar uses the call premium to pay for the put, so protection into an event costs upside rather than cash. Before a catalyst, skew and high implied volatility shape which strikes are available. Match the expiration to the event date, and plan for assignment, liquidity and tax effects before opening the position.